Skip to main content Skip to search
SMSF investment strategy

SMSF investment strategy review: A Guide for Trustees

Every self-managed super fund (SMSF) must have an investment strategy, and superannuation law requires trustees to formulate it, review it regularly, and give effect to it, having regard to the whole of the circumstances of the fund. Reviewing your SMSF investment strategy is not a tick-a-box exercise. It is how you make sure the fund’s assets still match the members’ retirement needs, and it is one of the things your auditor will check each year.

The law does not set a fixed timeframe for what “review regularly” means. It is widely accepted, and consistent with the ATO’s expectations, that the review should happen at least once a year. This guide explains how often to review your investment strategy, what the strategy must cover, and how to document it so your fund stays compliant.

Why Review Your SMSF Investment Strategy?

Superannuation law requires SMSF trustees to formulate, regularly review, and give effect to an investment strategy for the fund. The obligation is ongoing, not a one-off task completed when the fund is set up.

Whichever way you approach it, you need to be able to show your fund’s auditor that you have reviewed the investment strategy and documented any decisions made. That documentation should record either the changes you decided were necessary, or your conclusion that the existing strategy remains appropriate. Without that evidence, the review effectively did not happen as far as the audit is concerned.

How Often Should an SMSF Investment Strategy Be Reviewed?

At a minimum, the review should take place at least annually.

Some trustees carry out the review leading up to, or at the start of, a new financial year. Others do it as part of reviewing the completed financial accounts from the previous year. Neither approach is right or wrong, and you should consider what suits your situation. The important point is that the review is done and documented each year, ready for the auditor.

When Else Should You Review Your Investment Strategy?

Beyond the annual review, there are other times when it is appropriate to revisit the strategy. These include when:

  • there is a market correction;
  • a member joins or leaves the fund; or
  • a member starts a pension in the fund.

Each of these events can change the fund’s risk profile, cashflow needs, or liquidity requirements, which is why they are natural triggers for a fresh look at the strategy.

What Goes Into an SMSF Investment Strategy?

An investment policy is generally made up of two parts.

The first is the investment objective. This outlines the fund’s goals and expected outcomes, for example achieving a certain level of return over a certain period. It usually takes into account the age of the members, their retirement needs, and their investment risk profile.

The second is the investment strategy itself. This outlines how the fund will achieve the stated objectives, for example by setting investment asset ranges or naming the specific assets the fund will hold.

What Must Trustees Consider in the Investment Strategy?

When reviewing the strategy, trustees must give consideration to:

  • the risk and likely return of the fund’s investments, having regard to the fund’s objectives and expected cashflow requirements;
  • the composition of the fund’s investments, including the risk that comes from inadequate diversification;
  • the liquidity of the investments, having regard to expected cashflow requirements;
  • the fund’s ability to discharge its existing and prospective liabilities; and
  • whether the fund should hold insurance cover for one or more members.

These points must be considered, but it is up to the trustees to decide how they apply them based on the circumstances of the fund.

Does an SMSF Need a Diversified Investment Strategy?

Diversification must be considered, but considering it does not mean you are required to have a diversified strategy.

Many funds hold just a property and a bank account, and that may be perfectly appropriate for those funds. The key is documentation. If the fund is concentrated, the trustees should record what consideration they gave to diversification, why the lack of diversification is appropriate, and why they chose those particular assets.

Do You Need Insurance for Members?

There is no legal requirement to hold insurance cover for the members of an SMSF. However, trustees do need to document that insurance has been considered, even if the decision is not to hold any.

How Does Starting a Pension Change Your Investment Strategy?

A member starting a pension is a common reason to review the strategy, because it usually changes the liquidity considerations and investment profile of the fund.

While members are all in the pre-retirement growth phase, expenses tend to be more predictable, and many funds do not need to hold large cash reserves. Once members reach the point of accessing their benefits, whether as pension payments, lump sums, or both, cashflow, liquidity, and a potential cash buffer become far more important.

It is not unusual, in the lead-up to the end of a financial year, for trustees to find they do not have the cash to satisfy even the minimum pension requirements. There can be several reasons for this, but it should raise questions about whether the current investment strategy is still appropriate and whether the fund’s asset holdings need to be reviewed.

Example: The One-Property, One-Bank-Account Fund

Consider a fund that holds a single property and a bank account. This may have been a reasonable strategy during the growth phase. In the drawdown phase, the question is whether it still works.

Australian investors often have an affinity for bricks and mortar, but that does not make property appropriate in every situation. If the rental income from the property cannot support the members’ retirement needs and minimum pension withdrawals, something has to change. The same issue applies to any asset that cannot be sold easily, such as holdings in unlisted companies or trusts.

Example: A Member Starts a Pension

A fund has operated for years with all members in the growth phase, holding mostly long-term assets. One member then starts an account-based pension and must be paid at least the minimum pension each year. The trustees review the strategy, consider the fund’s new cashflow and liquidity needs, adjust the asset mix or build a cash buffer, and document the reasons for the change. The review is what keeps the fund both compliant and able to meet its payments.

Key Questions for Trustees Reviewing Their Investment Strategy

Before signing off on the review, trustees can work through the following:

  • Have you reviewed the investment strategy at least once this year?
  • Does your documentation show either the changes made or that the existing strategy remains appropriate?
  • Have you considered risk, return, diversification, liquidity, and the fund’s ability to meet its liabilities?
  • If the fund is concentrated, have you documented why that is appropriate?
  • Have you documented whether insurance for members was considered?
  • Has anything changed, such as a member joining or leaving, a pension starting, or a market correction, that calls for a review?
  • Can the fund meet its minimum pension payments and expected cashflow from its current assets?

Frequently Asked Questions

Does an SMSF have to review its investment strategy every year?

The law says the strategy must be reviewed “regularly” without setting a fixed timeframe. At least once a year is widely accepted and consistent with the ATO’s expectations.

Who is responsible for reviewing the investment strategy?

The trustees are responsible. They must also be able to show the fund’s auditor that the review was carried out and documented.

Does an SMSF investment strategy have to be diversified?

No. Diversification must be considered, but a concentrated fund, such as one holding a property and a bank account, can be appropriate if the trustees document why.

Is insurance for members compulsory in an SMSF?

No. There is no requirement to hold insurance for members, but trustees must document that they considered it.

What happens if the fund cannot meet its minimum pension payments?

It is a warning sign that the investment strategy may need review, particularly around liquidity and whether the asset mix still suits the drawdown phase.

When should the strategy be reviewed outside the annual review?

After events such as a market correction, a member joining or leaving the fund, or a member starting a pension.

Need Help?

If you are unsure whether your SMSF’s investment strategy still suits the fund, or whether it needs reviewing after a change such as a member starting a pension, Pitt Martin Group can help you review and document your strategy, weigh up diversification, liquidity and insurance, and prepare the evidence your auditor will expect.

As Sydney tax accountants, we assist trustees with SMSF compliance, investment strategy reviews and practical superannuation advice.

Pitt Martin Group is a firm of Chartered Accountants, providing services including taxation, accounting, business consulting, self-managed superannuation funds, auditing and mortgage & finance. We spend hundreds of hours each year on training and researching new tax laws to ensure our clients can maximize legitimate tax benefit. Our contact information are phone +61292213345 or email info@pittmartingroup.com.au. Pitt Martin Group, Sydney tax accountants, is located in the convenient transportation hub of Sydney’s central business district. Our honours include the 2018 CPA NSW President’s Award for Excellence, the 2020 Australian Small Business Champion Award Finalist, the 2021 Australia’s well-known media ‘Accountants Daily’ the Accounting Firm of the Year Award Finalist and the 2022 Start-up Firm of the Year Award Finalist, and the 2023 Hong Kong-Australia Business Association Business Award Finalist.

Pitt Martin Group qualifications include over fifteen years of professional experience in accounting industry, Registered Australia Tax Agents, membership certification of the Chartered Accountants Australia and New Zealand (CA ANZ), certified External Examiner of the Law Societies of New South Wales, Victoria, and Western Australia Law Trust Accounts, membership certification of the Finance Brokers Association of Australia Limited (FBAA), Registered Agents of the Australian Securities and Investments Commission (ASIC), certified Advisor of accounting software such as XERO, QUICKBOOKS, MYOB, etc.

This content is for reference only and does not constitute advice on any individual or group’s specific situation. Any individual or group should take action only after consulting with professionals. Due to the timeliness of tax laws, we have endeavoured to provide timely and accurate information at the time of publication, but cannot guarantee that the content stated will remain applicable in the future. Please indicate the source when forwarding this content.

Read more
SMSF Property Valuation

SMSF Property Valuation and FY2026 Audit Guide

SMSF property valuation is an important part of the annual compliance and audit process for self-managed super funds. For many SMSF trustees, property is one of the largest assets the fund holds, making an accurate and well-supported market valuation particularly important at audit time.

Unlike shares or cash, property does not have a live market price you can simply look up on 30 June. Yet every SMSF asset must be reported at its market value each financial year, and your fund auditor needs to see clear, objective evidence supporting the value you have used.

The good news is that a property audit becomes far smoother when trustees prepare the right evidence in advance, rather than scrambling once the auditor asks for it. This guide explains what is required, what evidence your auditor will look for, and the steps trustees can take now to make the financial year 2026 (FY2026) audit as painless as possible.

Why Is Property Harder to Audit Than Other SMSF assets?

Superannuation law requires that all SMSF assets are valued at market value each 30 June. For assets with a ready market, such as ASX-listed shares or managed funds, this is straightforward, because a reliable closing price is readily available.

Property is different. There is no daily quoted price, values can move significantly from year to year, and each property is unique. Because of this, trustees need to actively determine the market value and be able to back it up with supportable evidence. This is where many audits slow down. Often the value itself is fine; it is the supporting documentation that is missing or incomplete.

Who Is Responsible for Valuing SMSF assets?

The trustees are responsible for determining the market value of the fund’s assets, including property. This responsibility cannot be handed to the accountant or the auditor. The auditor’s role is to review the valuation and the evidence behind it, not to set the value.

After the fund’s annual financial statements are prepared, the auditor will ask to see objective and supportable evidence showing how the trustees arrived at the reported market value. If that evidence is not available, the auditor may be unable to sign off without qualification, which can lead to delays and additional cost.

When Do SMSF Assets Need to Be Valued?

SMSF assets, including property, must be valued as at 30 June each year for the fund’s financial statements and annual return. Even though your FY2026 audit may not take place for several months, the valuation still needs to reflect the market value at that 30 June date. Gathering evidence close to year end, while it is current, is far easier than trying to reconstruct it later.

Should You Use an Independent Valuer for SMSF assets?

Trustees have the option to engage a qualified independent valuer, and it is worth seriously considering where:

  • the property represents a significant portion of the fund’s total value; or
  • the property is unusual or otherwise difficult to value.

An independent valuation is not compulsory in every year, but it provides strong, defensible evidence and can remove a lot of uncertainty from the audit. For high-value or hard-to-value properties, the cost of a valuer is often small compared with the risk of an audit issue.

What Evidence Supports an SMSF Assets Valuation?

Where trustees choose not to use an independent valuer, they generally need to support the valuation with evidence drawn from more than one source. A single data point is rarely enough on its own.

For property, acceptable evidence typically includes:

  • Recent comparable sales: generally at least three sales of genuinely comparable properties, similar in size and location to the fund’s property.
  • A real estate agent appraisal: ideally one that also sets out the comparable sales it is based on.
  • Net income yields for commercial property: useful supporting evidence, but generally not sufficient on its own.

The Australian Taxation Office (ATO) sets out helpful guidance on acceptable methods and evidence in its Guide to valuing SMSF assets, which is a useful reference point for trustees.

Example: Valuing a Residential Property Held by an SMSF

An SMSF owns a residential unit. Rather than commission a full valuation every year, the trustees gather three recent sales of comparable units in the same complex and suburb, along with a written appraisal from a local real estate agent that references those sales. Together, this gives the auditor multiple, consistent sources supporting the reported market value, so the audit proceeds without a valuation query.

Can an SMSF Rent Its Property to a Related Party?

Where an SMSF holds property that meets the business real property (BRP) definition, it is possible to lease that property to a business operated by a member or a related party of the fund. This is a common and legitimate arrangement. For example, a fund might own the premises its members’ business trades from.

However, the fact that a related-party lease is permitted does not mean trustees can charge whatever rent they like. Any lease with a related party must be on arm’s length (commercial) terms.

A simple way to test this is to ask: would every term of this lease be agreed to if the tenant were a completely unrelated third party? If the rent is below market, or the terms are unusually favourable, the arrangement is unlikely to satisfy the arm’s length requirement.

What Evidence Does an Auditor Need for a Related-Party Lease?

To demonstrate that a related-party leasing arrangement is on arm’s length terms, the auditor should be provided with:

  • A properly documented lease setting out the terms in writing.
  • A rent appraisal from the time the lease was first entered into, supporting the rent as a market rate.
  • Evidence that the arrangement is actually operating in line with the lease terms, such as rent being paid on time and in the agreed amount.
  • Evidence that, where a prior lease term has expired, the rent has been reset to market value and backed by a new rent appraisal.

Example: Leasing Business Premises to a Related Party

An SMSF owns a commercial warehouse that meets the BRP definition and leases it to a company owned by the fund’s members. The trustees keep a signed lease, obtained a rent appraisal when the lease commenced, and can show consistent rent payments matching the lease. When the term expired, they obtained a fresh appraisal and reset the rent to the current market rate. Because the paperwork is complete and current, the auditor can readily confirm the arrangement is on arm’s length terms.

Key Questions for SMSF Trustees Before Audit

Before your SMSF audit, it helps to work through the following:

  1. Has each property been valued at market value as at 30 June?
  2. Is the valuation supported by evidence from more than one source?
  3. Do you have at least three genuinely comparable recent sales, or a current appraisal?
  4. Would an independent valuation be appropriate given the property’s value or complexity?
  5. If the property is leased to a related party, is the lease properly documented?
  6. Was a rent appraisal obtained when the lease commenced?
  7. Is the rent being paid in line with the lease?
  8. Has the rent been reset to market value at the end of any expired term, supported by a new appraisal?

How to Prepare Your SMSF Assets for the FY2026 Audit

Although your FY2026 audit may still be some months away, the smoothest audits are the ones where trustees are proactive. Rather than waiting for the auditor’s request, trustees can:

  1. Gather comparable sales and appraisals close to 30 June, while the information is current.
  2. Confirm whether an independent valuation is warranted for any significant or hard-to-value property.
  3. Review related-party leases to ensure they are documented, current, and on market terms.
  4. Store all valuation and lease evidence in one place, ready to hand to the auditor.

Taking these steps early means fewer queries, faster sign-off, and less stress at audit time.

Frequently Asked Questions

Does an SMSF have to value its property every year?

Yes. All SMSF assets, including property, must be valued at market value each 30 June for the fund’s financial statements and annual return.

Who decides the market value of SMSF property?

The trustees are responsible for determining the market value used for an SMSF property valuation. The auditor reviews the value and the supporting evidence but does not set it.

Does an SMSF need an independent valuation of property each year?

Not necessarily. Trustees can support a valuation with evidence such as comparable sales and agent appraisals. However, an independent valuation should be considered where the property is a significant part of the fund or is difficult to value.

How many comparable sales does an SMSF need?

Generally at least three sales of genuinely comparable properties, similar in size and location, are expected as supporting evidence.

Can an SMSF lease property to a related party?

Yes, where the property meets the business real property definition. The lease must be on arm’s length (commercial) terms, supported by a rent appraisal.

What rent can an SMSF charge a related party?

The rent must reflect market value, meaning the same rent an unrelated third party would pay. Charging below-market rent to a related party can create compliance problems.

When should trustees start preparing for the audit?

As early as possible. Gathering valuation and lease evidence soon after 30 June, rather than waiting for the auditor’s request, makes for a much smoother audit.

Need Help?

Pitt Martin Group can assist SMSF trustees with SMSF accounting, annual compliance and audit preparation, including reviewing property valuation evidence and related-party lease documentation. If you are preparing for your FY2026 SMSF audit or are unsure whether your property valuation evidence is sufficient, contact our Sydney SMSF accountants for professional assistance.

Pitt Martin Group is a firm of Chartered Accountants, providing services including taxation, accounting, business consulting, self-managed superannuation funds, auditing and mortgage & finance. We spend hundreds of hours each year on training and researching new tax laws to ensure our clients can maximize legitimate tax benefit. Our contact information are phone +61292213345 or email info@pittmartingroup.com.au. Pitt Martin Group, Sydney tax accountants, is located in the convenient transportation hub of Sydney’s central business district. Our honours include the 2018 CPA NSW President’s Award for Excellence, the 2020 Australian Small Business Champion Award Finalist, the 2021 Australia’s well-known media ‘Accountants Daily’ the Accounting Firm of the Year Award Finalist and the 2022 Start-up Firm of the Year Award Finalist, and the 2023 Hong Kong-Australia Business Association Business Award Finalist.

Pitt Martin Group qualifications include over fifteen years of professional experience in accounting industry, Registered Australia Tax Agents, membership certification of the Chartered Accountants Australia and New Zealand (CA ANZ), certified External Examiner of the Law Societies of New South Wales, Victoria, and Western Australia Law Trust Accounts, membership certification of the Finance Brokers Association of Australia Limited (FBAA), Registered Agents of the Australian Securities and Investments Commission (ASIC), certified Advisor of accounting software such as XERO, QUICKBOOKS, MYOB, etc.

This content is for reference only and does not constitute advice on any individual or group’s specific situation. Any individual or group should take action only after consulting with professionals. Due to the timeliness of tax laws, we have endeavoured to provide timely and accurate information at the time of publication, but cannot guarantee that the content stated will remain applicable in the future. Please indicate the source when forwarding this content.
Read more
Changes to SMSF Borrowing Rules: New Restrictions on Property Purchases

Changes to SMSF Borrowing Rules: New Restrictions on Property Purchases

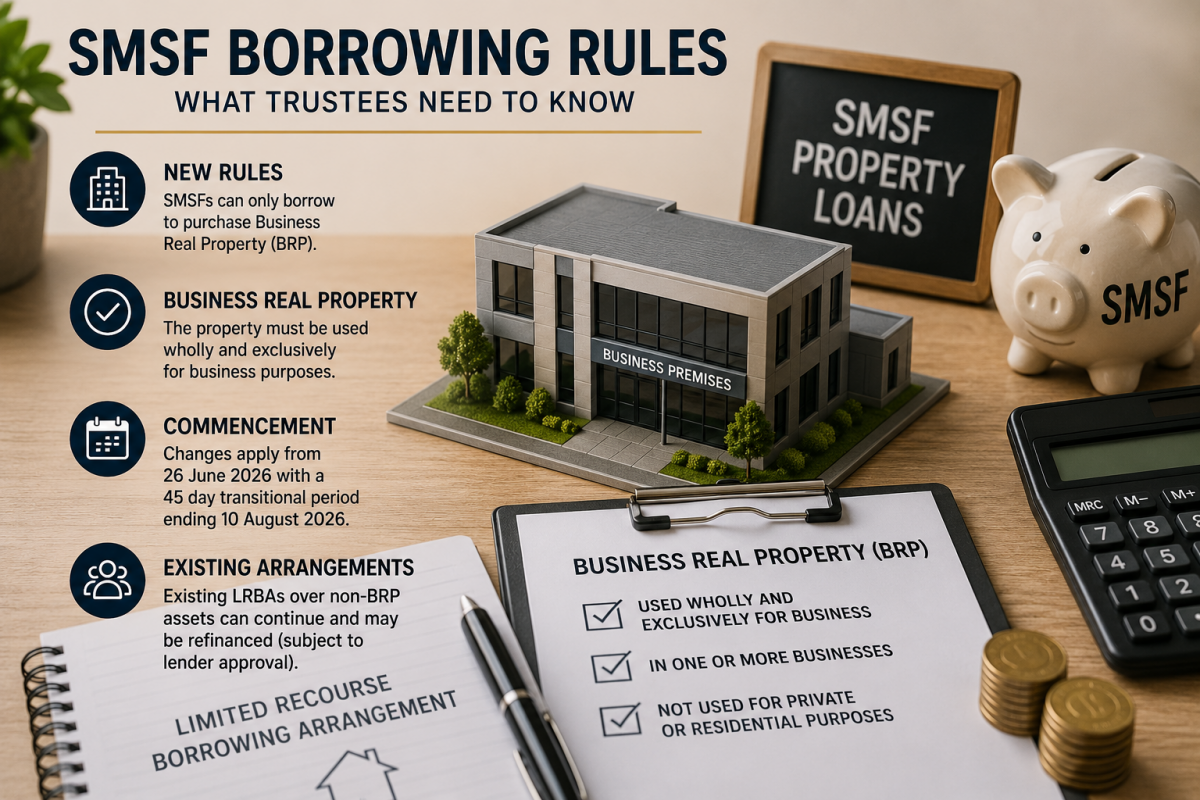
Significant changes to Self-Managed Super Fund (SMSF) borrowing rules have changed the types of property that SMSFs can acquire using a Limited Recourse Borrowing Arrangement (LRBA).

The changes became law on 26 June 2026 and, following a 45-day transitional period ending on 10 August 2026, generally restrict new SMSF property borrowing to property that meets the definition of business real property (BRP).

For SMSF trustees considering purchasing property through their super fund, understanding the new rules is essential before entering into a contract or arranging finance.

What Has Changed With SMSF Borrowing Rules?

SMSFs have traditionally been permitted to borrow in limited circumstances, including through an LRBA to acquire a single acquirable asset.

Property has been one of the most common assets purchased using these arrangements. Previously, there was no specific legislative restriction requiring the property acquired under an LRBA to be commercial or business property.

The new rules significantly narrow this position.

Where an SMSF uses borrowing to purchase real property under the new rules, the property generally needs to satisfy the business real property definition.

In practical terms, this means SMSF trustees considering an LRBA need to determine whether the property qualifies as business real property before proceeding with the purchase.

What Is Business Real Property for an SMSF?

Business real property is broadly real property that is used wholly and exclusively in one or more businesses.

An important point is that the test focuses primarily on how the property is actually used, rather than simply its zoning, appearance or original design.

This means the distinction is not necessarily as simple as:

  • Residential property = not eligible
  • Commercial property = eligible

The actual use of the property can be critical.

For example, a residential-style terrace house that is used wholly and exclusively as a medical practice may potentially satisfy the business real property requirements, despite originally being designed as a residence.

Conversely, a property that appears commercial may not necessarily qualify if it is not used wholly and exclusively for business purposes.

Can an SMSF Still Borrow to Buy Residential Property?

Under the new SMSF borrowing rules, an SMSF will generally not be able to use a new LRBA to purchase ordinary residential investment property that does not satisfy the business real property definition.

However, describing the changes simply as a “ban on SMSFs borrowing to buy residential property” can be misleading.

The relevant issue is the use of the property.

A residentially designed property may potentially qualify if it is used wholly and exclusively for business purposes and otherwise satisfies the business real property requirements.

Specialist advice should be obtained before relying on this treatment.

What About Mixed-Use Property?

Mixed-use properties require particular attention.

The business real property definition generally requires the property to be used wholly and exclusively for business purposes.

For example, consider a property on a single title containing:

  • a retail shop on the ground floor; and
  • a residential apartment upstairs.

Even though part of the property is clearly commercial, the residential component may prevent the entire property from satisfying the business real property definition.

SMSF trustees considering mixed-use properties should therefore obtain advice before signing a contract or entering into an LRBA.

When Did the New SMSF Borrowing Rules Start?

The changes became law on 26 June 2026.

However, the legislation provided a 45-day transitional period ending on 10 August 2026.

The transitional provisions may allow certain arrangements involving non-business real property that were already being implemented to continue, including circumstances where settlement takes place after 10 August 2026, provided the relevant arrangement to purchase the property was entered into on or before the transitional deadline.

Whether a particular transaction qualifies for the transitional treatment will depend on the specific circumstances and documentation.

SMSF trustees who entered into an arrangement involving non-BRP property before the deadline but had not completed settlement by 10 August 2026 should obtain specialist SMSF legal advice.

What Happens to Existing SMSF LRBAs?

Importantly, the new rules do not automatically require existing SMSF borrowing arrangements involving non-business real property to be unwound.

Existing LRBAs over non-BRP assets can generally continue under the updated rules.

The legislation also allows existing arrangements to be refinanced, subject to the relevant legislative requirements as well as lender availability and credit approval.

This is particularly important for SMSFs that already hold residential investment property through an LRBA.

Trustees should nevertheless obtain advice before refinancing or materially changing an existing borrowing arrangement, as changes to the structure or terms may have unintended SMSF compliance consequences.

Key Questions for SMSF Trustees

Before using an SMSF to borrow for a property purchase, trustees should consider:

  1. Does the property qualify as business real property?
  2. Is the property used wholly and exclusively for business purposes?
  3. Is there any residential or private use of the property?
  4. Does the proposed borrowing satisfy the LRBA requirements?
  5. Does the property meet the single acquirable asset rules?
  6. Is the purchase permitted under the SMSF’s trust deed and investment strategy?
  7. Are related-party acquisition and leasing rules relevant?
  8. If the arrangement began before 10 August 2026, do the transitional provisions apply?

These issues should ideally be reviewed before the SMSF signs a property contract, as correcting an incorrectly structured SMSF property transaction after signing can be difficult and costly.

Example: Residential Investment Property

An SMSF wants to borrow $600,000 under an LRBA to purchase an apartment that will be rented to an unrelated family as their home.

The apartment is being used for residential purposes rather than wholly and exclusively in a business.

Under the new borrowing restrictions, the property would generally not satisfy the business real property requirement for a new LRBA.

Example: Residential-Style Property Used as a Medical Practice

An SMSF is considering purchasing a terrace house that has been converted into medical consulting rooms.

Although the building was originally designed as residential accommodation, it is now used wholly and exclusively to operate a medical practice.

Subject to the particular circumstances and the other SMSF requirements being satisfied, the property may potentially qualify as business real property.

This illustrates why the new rules should not simply be viewed as a distinction between “residential” and “commercial” property.

What Should SMSF Trustees Do Before Borrowing?

SMSF property transactions involving LRBAs are already highly regulated, and the new borrowing restrictions add another important consideration.

Before entering into a new LRBA, trustees should obtain appropriate SMSF, legal, tax and financial advice to confirm that:

  • the proposed property satisfies the business real property requirements;
  • the LRBA has been correctly structured;
  • the acquisition complies with the SIS Act and related SMSF rules;
  • the fund’s trust deed and investment strategy permit the transaction; and
  • any related-party transactions are appropriately structured.

This review should take place before contracts and borrowing documents are signed.

Frequently Asked Questions

Can an SMSF still borrow money to buy property?

Yes. SMSFs can still borrow in limited circumstances through an LRBA, but the new rules restrict the types of real property that can be acquired using new borrowing arrangements.

Can an SMSF borrow to buy a residential investment property?

Generally, a new LRBA cannot be used to acquire ordinary residential investment property that does not qualify as business real property.

Can an SMSF borrow to buy commercial property?

Potentially, yes. However, simply describing a property as “commercial” does not automatically mean it qualifies. The property needs to satisfy the relevant business real property requirements.

Can an SMSF buy business premises using an LRBA?

Potentially, yes, provided the property qualifies as business real property and all other LRBA, SMSF and superannuation law requirements are satisfied.

Can an SMSF keep residential property already purchased through an LRBA?

The updated rules allow existing LRBAs involving non-BRP assets to continue, subject to the applicable requirements.

Can an existing SMSF residential property loan be refinanced?

Existing arrangements may be refinanced under the updated rules, subject to the legislative requirements, lender availability and credit approval.

Does property zoning determine whether it is business real property?

Not necessarily. The business real property test focuses significantly on the use of the property, rather than simply its zoning, appearance or original design.

Need Advice About an SMSF Property Purchase?

The changes to SMSF borrowing rules make it increasingly important to review a proposed property acquisition before signing a contract or arranging finance.

If you are considering purchasing property through your SMSF, particularly using an LRBA, professional advice can help determine whether the property qualifies under the new rules and whether the proposed structure complies with Australia’s superannuation and tax requirements.

Need Help?

By working with us as your professional tax accountant and mortgage broker, you can be confident that your loans are structured to protect your tax position, maximise deductions, and avoid costly mistakes, giving you greater peace of mind and more control over your financial future.

Pitt Martin Group is a firm of Chartered Accountants, providing services including taxation, accounting, business consulting, self-managed superannuation funds, auditing and mortgage & finance. We spend hundreds of hours each year on training and researching new tax laws to ensure our clients can maximize legitimate tax benefit. Our contact information are phone +61292213345 or email info@pittmartingroup.com.au. Pitt Martin Group is located in the convenient transportation hub of Sydney’s central business district. Our honours include the 2018 CPA NSW President’s Award for Excellence, the 2020 Australian Small Business Champion Award Finalist, the 2021 Australia’s well-known media ‘Accountants Daily’ the Accounting Firm of the Year Award Finalist and the 2022 Start-up Firm of the Year Award Finalist, and the 2023 Hong Kong-Australia Business Association Business Award Finalist.

Pitt Martin Group qualifications include over fifteen years of professional experience in accounting industry, Registered Australia Tax Agents, membership certification of the Chartered Accountants Australia and New Zealand (CA ANZ), certified External Examiner of the Law Societies of New South Wales, Victoria, and Western Australia Law Trust Accounts, membership certification of the Finance Brokers Association of Australia Limited (FBAA), Registered Agents of the Australian Securities and Investments Commission (ASIC), certified Advisor of accounting software such as XERO, QUICKBOOKS, MYOB, etc.

This content is for reference only and does not constitute advice on any individual or group’s specific situation. Any individual or group should take action only after consulting with professionals. Due to the timeliness of tax laws, we have endeavoured to provide timely and accurate information at the time of publication, but cannot guarantee that the content stated will remain applicable in the future. Please indicate the source when forwarding this content.
Read more
SMSF 2026–27 Checklist

SMSF 2026–27 Checklist: Key Trustee Actions

With the 2026–27 financial year now underway, this SMSF 2026–27 checklist highlights the key actions trustees should take to keep their funds compliant and well positioned. Completing the items in this SMSF 2026–27 checklist early can help reduce year-end pressure, minimize compliance risks and identify valuable planning opportunities. The checklist below summarizes the major legislative changes, reporting obligations and practical considerations trustees should review during the new financial year.

1. Review Transfer Balance Cap and Pension Planning

• General transfer balance cap increases: From 1 July 2026, the general transfer balance cap (TBC) rises from $2.0 million to $2.1 million. Trustees should determine whether members are entitled to additional personal TBC indexation, particularly where retirement pensions commenced before previous indexation dates.

Although the Australian Taxation Office (ATO) calculates each member’s personal transfer balance cap, its assessment depends on transfer balance account (TBA) events that have already been reported. Pension commencements, commutations and other reportable transactions completed before 30 June 2026 should therefore be lodged promptly to ensure any entitlement to indexation is calculated accurately.

• Review legacy pensions: The temporary five-year measure allowing certain legacy pensions to be exited remains available between 7 December 2024 and 6 December 2029. Trustees responsible for lifetime, life expectancy or market-linked pensions should first confirm that the trust deed authorises the proposed strategy. Any decision should also consider the potential impact of Division 296 together with the relevant commutation requirements before implementation.

2. Updating Contribution Strategies in the SMSF 2026–27 Checklist

• Contribution caps have increased: From the 2026–27 financial year, the concessional contribution cap becomes $32,500 while the standard non-concessional contribution cap increases to $130,000. Eligibility to make non-concessional contributions remains subject to the member’s total superannuation balance (TSB) at 30 June 2026 being below $2.1 million. Trustees should review planned contributions carefully to reduce the likelihood of exceeding applicable caps.

• Check bring-forward eligibility: Before applying the bring-forward provisions during 2026–27, trustees should confirm each member’s TSB at 30 June 2026 because both eligibility thresholds and available bring-forward periods have changed.

The increase in the standard non-concessional cap also raises the maximum bring-forward amount from $360,000 to $390,000. However, members who activated the bring-forward provisions during either the 2024–25 or 2025–26 financial years do not automatically gain access to this higher contribution limit.

3. Monitor Pension Requirements and ECPI Risks

• Meet annual pension obligations: Trustees should verify that each pension satisfies the minimum annual payment requirements based on the member’s age. Failure to pay the required minimum amount before year-end may affect pension compliance and jeopardise the fund’s entitlement to exempt current pension income.

Members receiving a transition to retirement income stream should also ensure total annual withdrawals remain within both the minimum and 10% maximum payment limits. Where a member turns 65 during 2026–27, the income stream automatically enters retirement phase, potentially affecting their transfer balance cap position. Professional advice before that milestone may help avoid unintended outcomes.

• Follow correct pension procedures: Pension commencements and commutations should always be completed using the required administrative processes. Errors may trigger additional transfer balance account events or unexpected tax consequences. Trustees should also ensure all reportable TBA events are lodged with the ATO within the prescribed reporting deadlines.

4. Related-Party Loan Reviews in the SMSF 2026–27 Checklist

• Confirm related-party loan compliance: Trustees with related-party borrowing arrangements should review the requirements outlined in ATO Practical Compliance Guideline PCG 2016/5. This guideline sets out the conditions that generally need to be satisfied for a loan to fall within the ATO’s safe harbour provisions, including benchmark interest rates and other commercial terms.

The applicable interest rate should be reviewed each year using the benchmark released during May immediately before the start of the new financial year. For the 2025–26 financial year, the safe harbour rates were 8.95% for property loans and 10.95% for loans relating to listed securities.

Following recent increases in the Reserve Bank of Australia’s cash rate, the benchmark interest rates have increased to 9.35% for property-backed loans and 11.35% for listed securities. Trustees relying on the safe harbour provisions should recalculate minimum repayments to ensure loan arrangements remain compliant throughout the 2026–27 financial year.

5. Review Payroll and Super Contribution Processes

• Ensure New Payments Platform readiness: From 1 July 2026, employers and superannuation funds must be capable of receiving contributions through the New Payments Platform (NPP). Trustees should verify that the fund’s nominated bank account supports Osko, PayID and other approved NPP payment methods so employer contributions can be processed without disruption.

• Prepare for Member Verification Requests: Employers will begin using Member Verification Requests (MVRs) to confirm whether an SMSF can accept employer contributions before payments are made. Trustees should ensure these requests can be monitored and answered within the required timeframe.

Generally, SuperStream messages are received through the administration platform used by the fund’s accountant or administrator. Members should therefore advise their SMSF adviser whenever an employer intends to submit an MVR so the request can be identified and managed promptly.

• Review obligations for closely held employees: Where an SMSF receives employer contributions for related employees, trustees should determine whether any available SuperStream exemptions apply and confirm payroll systems comply with the latest reporting obligations. Late lodgements may result in penalties. Trustees should also remember that overdue SMSF Annual Returns may cause the ATO to remove the fund from the SMSF Lookup register, preventing employers from directing compulsory contributions to the fund until its compliance status is restored.

6. Consider Division 296 Transitional Rules

• Assess transitional arrangements carefully: The 2026–27 financial year introduces specific transitional provisions for Division 296, with the relevant total superannuation balance measured at 30 June 2027. Trustees should evaluate whether adopting a Division 296 cost base based on market values at 30 June 2026 would be appropriate for the fund’s circumstances.

This election is not required until the 2027 SMSF Annual Return is lodged. However, because it applies to all eligible fund assets and may influence future capital gains, capital losses and subsequent tax calculations, trustees should fully understand its consequences before proceeding. Professional advice is strongly recommended before making the election.

7. Finish Your SMSF 2026–27 Checklist with Good Housekeeping Practices

• Review trustee structure and documentation: Funds operating with individual trustees may wish to consider whether moving to a corporate trustee structure would provide governance or administrative benefits. Any structural changes should be discussed with an adviser and reported to the ATO, ASIC and other relevant authorities within the required timeframes.

• Maintain thorough records: Trustees should retain comprehensive documentation supporting trustee decisions, market valuations, contribution timing, elections, employer correspondence and other significant transactions. Well-maintained records assist with the annual audit process and provide valuable evidence if the ATO reviews the fund.

Taking action early can help minimise year-end stress and reduce compliance risks. Please contact us if you would like to discuss any of the matters outlined above or how they may affect your SMSF.

Need Help?

By working with us as your professional tax accountant and mortgage broker, you can be confident that your loans are structured to protect your tax position, maximise deductions, and avoid costly mistakes, giving you greater peace of mind and more control over your financial future.

Pitt Martin Group is a firm of Chartered Accountants, providing services including taxation, accounting, business consulting, self-managed superannuation funds, auditing and mortgage & finance. We spend hundreds of hours each year on training and researching new tax laws to ensure our clients can maximize legitimate tax benefit. Our contact information are phone +61292213345 or email info@pittmartingroup.com.au. Pitt Martin Group is located in the convenient transportation hub of Sydney’s central business district. Our honours include the 2018 CPA NSW President’s Award for Excellence, the 2020 Australian Small Business Champion Award Finalist, the 2021 Australia’s well-known media ‘Accountants Daily’ the Accounting Firm of the Year Award Finalist and the 2022 Start-up Firm of the Year Award Finalist, and the 2023 Hong Kong-Australia Business Association Business Award Finalist.

Pitt Martin Group qualifications include over fifteen years of professional experience in accounting industry, Registered Australia Tax Agents, membership certification of the Chartered Accountants Australia and New Zealand (CA ANZ), certified External Examiner of the Law Societies of New South Wales, Victoria, and Western Australia Law Trust Accounts, membership certification of the Finance Brokers Association of Australia Limited (FBAA), Registered Agents of the Australian Securities and Investments Commission (ASIC), certified Advisor of accounting software such as XERO, QUICKBOOKS, MYOB, etc.

This content is for reference only and does not constitute advice on any individual or group’s specific situation. Any individual or group should take action only after consulting with professionals. Due to the timeliness of tax laws, we have endeavoured to provide timely and accurate information at the time of publication, but cannot guarantee that the content stated will remain applicable in the future. Please indicate the source when forwarding this content.
Read more
SMSF year end review checklist before 30 June

SMSF Year-End Review: Key Matters Before 30 June

As the end of the financial year approaches, SMSF trustees and members should take time to review their affairs before 30 June. Addressing important matters before SMSF year-end review can help minimize compliance risks, maintain access to available tax concessions and ensure planning opportunities are not missed. The checklist below outlines several areas that may deserve attention before the financial year closes.

Contribution Timing in Your SMSF Year-End Review

• Ensure money reaches the fund before SMSF year-end: For contribution limit and deduction purposes, the relevant date is generally when funds are received by the SMSF rather than when a payment instruction is submitted.

Where money is transferred between separate banking institutions, additional time should be allowed for processing and settlement delays.

• Personally deductible contributions: A member who intends to claim a tax deduction for a personal super contribution must provide the required notice to the trustee and receive acknowledgement from the fund within the prescribed timeframe. In most situations, this must occur before the earlier of lodging the member’s income tax return or 30 June of the following financial year.

• Planning to start a pension shortly after year-end? If retirement income payments are expected to commence early in the next financial year, the deduction notice process should generally be completed first. Otherwise, the contribution may no longer qualify for a personal deduction.

Year-End Planning Opportunities for SMSF Members

• Accessing unused concessional limits: Members with a total superannuation balance below $500,000 at the previous 30 June may be eligible to utilise concessional contribution capacity carried forward from earlier years. This can allow larger deductible contributions to be made in the current year.

This strategy may be particularly valuable where an individual expects to realise a significant capital gain during the 2025–26 income year.

• Using the SMSF allocation timing concession: In certain circumstances, a contribution received during June may be held temporarily in an unallocated reserve before being allocated to a member during July. If implemented correctly, the contribution may count towards the following year’s limits rather than the current year’s cap.

Often referred to as a reserving arrangement, this strategy requires appropriate documentation, trustee resolutions and a trust deed that permits its use. When applied correctly, it may provide additional tax planning flexibility.

After-Tax Contributions in an SMSF Year-End Review

• Bring-forward provisions: Eligibility to access the bring-forward rules depends on a member’s total superannuation balance as at the previous SMSF year-end.

For eligible individuals, it may be possible to contribute more than the standard annual after-tax limit by utilising future years’ contribution capacity.

• Contributions for a spouse and government incentives: Contributions made to a spouse’s super account may provide access to a tax offset where eligibility conditions are satisfied. Lower-income earners who make personal after-tax contributions may also qualify for a government co-contribution if the relevant income requirements are met.

Contribution Limit Changes for Your SMSF Review

The following contribution limits currently apply during the 2025–26 financial year:

• Concessional contributions: $30,000.

• Non-concessional contributions: $120,000.

From 1 July 2026, these limits will increase to:

• Concessional contributions: $32,500.

• Non-concessional contributions: $130,000.

Retirement Planning and Transfer Balance Cap Review

• Required minimum pension payments: Where account-based pensions are being paid from the SMSF, trustees should ensure the minimum annual payment has been made to each pension member before SMSF year-end. Failing to satisfy this requirement may create administrative difficulties and affect valuable tax concessions.

• Other retirement income products may also require minimum annual payments. Certain arrangements impose maximum payment limits, and exceeding those limits may produce adverse consequences.

• Retirement transfer threshold planning: The general transfer balance cap will increase from 1 July 2026.

Members considering commencing a retirement pension near the end of the financial year should carefully consider timing. Whether the pension begins before or after 1 July 2026 may affect the amount that can be transferred into the tax-free retirement phase.

• Current general transfer balance cap for 2025–26: $2.0 million. This amount is scheduled to increase to $2.1 million from 1 July 2026.

• Not all members will have access to the full threshold. Depending on previous transfer balance account events, an individual’s personal limit may be lower.

Valuations and Compliance in Your SMSF Year-End Review

• Market value evidence: Trustees should ensure fund assets are supported by evidence demonstrating market value as close as practical to 30 June. Particular attention should be given to property holdings, connected-party assets and investments that are not publicly traded.

• Related-party dealings: Review leasing arrangements, rental agreements and services involving related parties to ensure they remain appropriately documented and reflect commercial terms.

• Pension records and trustee documentation: Pension commencements, commutations and benefit payments should be supported by properly executed documentation together with trustee resolutions and records.

Need Help?

By working with us as your professional tax accountant and mortgage broker, you can be confident that your loans are structured to protect your tax position, maximise deductions, and avoid costly mistakes, giving you greater peace of mind and more control over your financial future.

Pitt Martin Group is a firm of Chartered Accountants, providing services including taxation, accounting, business consulting, self-managed superannuation funds, auditing and mortgage & finance. We spend hundreds of hours each year on training and researching new tax laws to ensure our clients can maximize legitimate tax benefit. Our contact information are phone +61292213345 or email info@pittmartingroup.com.au. Pitt Martin Group is located in the convenient transportation hub of Sydney’s central business district. Our honours include the 2018 CPA NSW President’s Award for Excellence, the 2020 Australian Small Business Champion Award Finalist, the 2021 Australia’s well-known media ‘Accountants Daily’ the Accounting Firm of the Year Award Finalist and the 2022 Start-up Firm of the Year Award Finalist, and the 2023 Hong Kong-Australia Business Association Business Award Finalist.

Pitt Martin Group qualifications include over fifteen years of professional experience in accounting industry, Registered Australia Tax Agents, membership certification of the Chartered Accountants Australia and New Zealand (CA ANZ), certified External Examiner of the Law Societies of New South Wales, Victoria, and Western Australia Law Trust Accounts, membership certification of the Finance Brokers Association of Australia Limited (FBAA), Registered Agents of the Australian Securities and Investments Commission (ASIC), certified Advisor of accounting software such as XERO, QUICKBOOKS, MYOB, etc.

This content is for reference only and does not constitute advice on any individual or group’s specific situation. Any individual or group should take action only after consulting with professionals. Due to the timeliness of tax laws, we have endeavoured to provide timely and accurate information at the time of publication, but cannot guarantee that the content stated will remain applicable in the future. Please indicate the source when forwarding this content.
Read more
EV Home Charging Rate

ATO Increases EV Home Charging Rate to 5.47 Cents per Kilometre from 2026

Key Takeaways

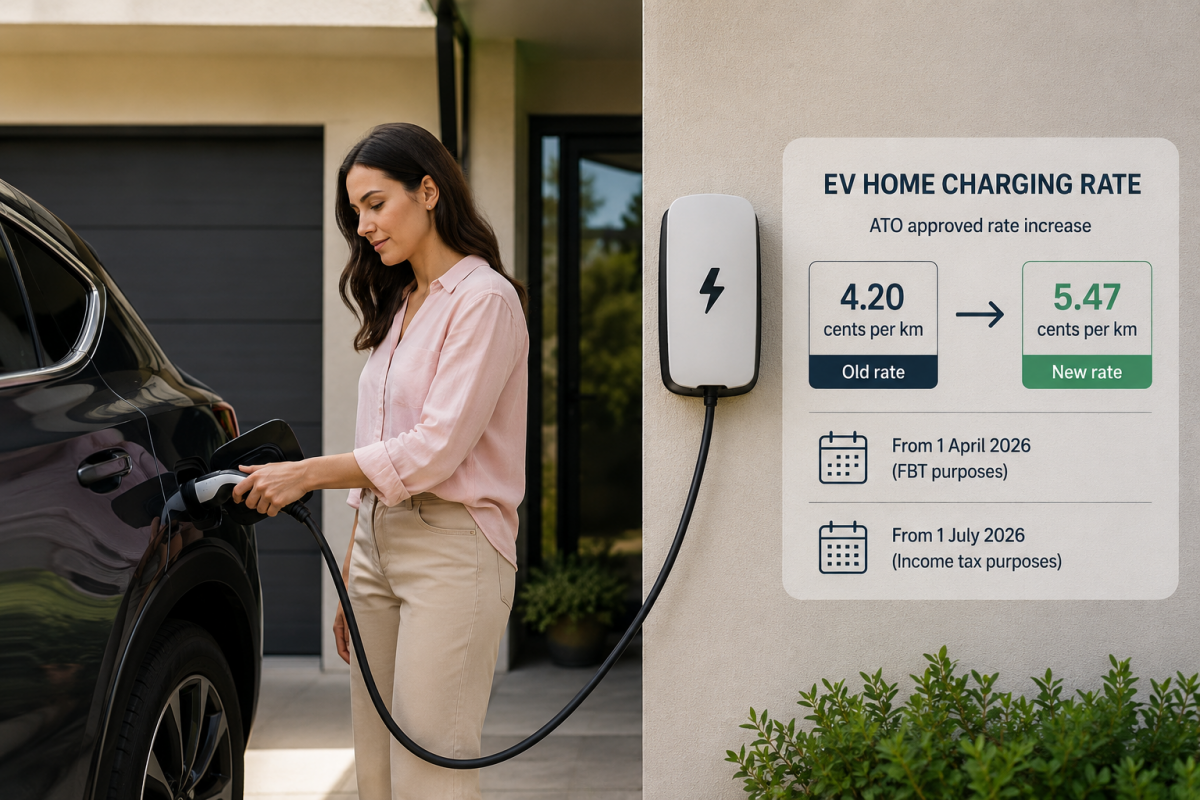
  • The ATO’s standard EV home charging rate will increase from 4.20 cents to 5.47 cents per kilometre.
  • The new rate applies from 1 April 2026 for Fringe Benefits Tax (FBT) purposes.
  • The new rate applies from 1 July 2026 for income tax deductions.
  • Employers providing EVs through novated leases, salary packaging arrangements or company vehicles may see changes to their FBT calculations.
  • Individuals claiming work-related electric vehicle expenses using the logbook method may be entitled to larger deductions.
  • Minimal record-keeping is required to use the ATO’s simplified method.

The Australian Taxation Office (ATO) has announced changes to the approved EV home charging rate, which may affect taxpayers and employers using electric vehicles (EVs) or plug-in hybrid electric vehicles (PHEVs) for work-related purposes where charging occurs at home.

For fringe benefits tax (FBT) purposes, the revised rate will apply from 1 April 2026, while income tax claims will adopt the change from 1 July 2026. Under the update, the approved home-charging electricity rate will increase from 4.20 cents per kilometre to 5.47 cents per kilometre.

Where household electricity bills do not separately identify EV charging usage, the ATO allows taxpayers to rely on this simplified cents-per-kilometre calculation method. This removes the need to track electricity consumption in kilowatt hours or install specialized charging measurement equipment. Instead, taxpayers can estimate charging costs by multiplying the approved rate by the distance travelled by the vehicle.

The revised amount reflects higher electricity prices and is intended to provide businesses and individuals with a more commercially realistic charging allowance.

Home Charging Electricity Rate Impact on Employers

Employers supplying EVs or PHEVs through salary packaging arrangements, novated leasing structures, or company-owned vehicles may see changes to their FBT calculations as a result of the increased EV home charging rate. In practice, the update may:

• Increase the taxable value of the benefit when the operating cost method is adopted.

• Result in larger employee recipient contributions, potentially reducing the employer’s FBT liability.

• Affect the calculation of reportable fringe benefits amounts.

Claiming Deductions for Electric Vehicle Charging Costs

Taxpayers using the logbook method to claim work-related vehicle expenses may apply the new rate to the business-use portion of kilometres travelled from the commencement of the 2026–27 income year. Earlier periods, including years dating back to 2022, must continue using the previous 4.20-cent rate.

Records Required for EV Charging Expense Claims

Only limited records are required to support these claims. Taxpayers should retain:

• Odometer readings taken at the beginning and end of the relevant income or FBT year where possible.

• A compliant logbook identifying business and private travel if using the operating cost or logbook method.

• At least one electricity bill demonstrating that home electricity expenses are incurred.

• For PHEVs, petrol receipts should also be retained. Fuel expenses must be calculated separately using the manufacturer’s hybrid fuel consumption figures, while the ATO home-charging rate applies solely to electric kilometres travelled.

Tip: Many newer EV models now report the proportion of charging completed at home compared with public charging stations. Using this information may improve calculation accuracy and potentially increase deductions.

Example of the Revised Home Charging Rate

If an employee owns an EV and travels 25,000 kilometres for employment purposes during the 2026–27 income year, the home-charging expense calculation would be:

Home-charging cost = 25,000 × 5.47c = $1,367.50 (previously $1,050).

Compared with the earlier rate, the additional $317.50 may assist in lowering the employee’s taxable income for the relevant year.

Preparing for the New Electric Vehicle Charging Rules

• The existing lower rate should continue to be used for the FBT year ending 31 March 2026 and for income tax deductions relating to the year ending 30 June 2026.

• The revised rate should only be applied for the current FBT year and for income years commencing from 1 July 2026.

The adoption of electric vehicles continues to grow, and the updated ATO rate is expected to deliver improved tax outcomes for many taxpayers while maintaining a straightforward compliance process. Whether you operate a vehicle fleet, offer salary packaging arrangements, or claim motor vehicle expenses personally, now is an ideal time to assess the potential benefits. Our team can help you evaluate the impact and ensure you maximise all available tax concessions and deductions.

Need Help?

By working with us as your professional tax accountant and mortgage broker, you can be confident that your loans are structured to protect your tax position, maximise deductions, and avoid costly mistakes, giving you greater peace of mind and more control over your financial future.

Pitt Martin Group is a firm of Chartered Accountants, providing services including taxation, accounting, business consulting, self-managed superannuation funds, auditing and mortgage & finance. We spend hundreds of hours each year on training and researching new tax laws to ensure our clients can maximize legitimate tax benefit. Our contact information are phone +61292213345 or email info@pittmartingroup.com.au. Pitt Martin Group is located in the convenient transportation hub of Sydney’s central business district. Our honours include the 2018 CPA NSW President’s Award for Excellence, the 2020 Australian Small Business Champion Award Finalist, the 2021 Australia’s well-known media ‘Accountants Daily’ the Accounting Firm of the Year Award Finalist and the 2022 Start-up Firm of the Year Award Finalist, and the 2023 Hong Kong-Australia Business Association Business Award Finalist.

Pitt Martin Group qualifications include over fifteen years of professional experience in accounting industry, membership certification of the Chartered Accountants Australia and New Zealand (CA ANZ), membership certification of the Australian Society of Certified Practising Accountants (CPA), Registered Australia Tax Agents, certified External Examiner of the Law Societies of New South Wales, Victoria, and Western Australia Law Trust Accounts, membership certification of the Finance Brokers Association of Australia Limited (FBAA), Registered Agents of the Australian Securities and Investments Commission (ASIC), certified Advisor of accounting software such as XERO, QUICKBOOKS, MYOB, etc.

This content is for reference only and does not constitute advice on any individual or group’s specific situation. Any individual or group should take action only after consulting with professionals. Due to the timeliness of tax laws, we have endeavoured to provide timely and accurate information at the time of publication, but cannot guarantee that the content stated will remain applicable in the future. Please indicate the source when forwarding this content.
Read more
CGT Business Sale Valuation

Business Sale Valuation: Kilgour Case Tax Explanation

The methodology applied to assets in a business sale valuation – or a partial disposal of one – carries significant consequences for the tax position of parties involved. A ruling by the Full Federal Court, Kilgour v Commissioner of Taxation [2025] FCAFC 183, establishes important judicial guidance on the proper determination of “market value” within the capital gains tax framework.

Practitioners and business owners engaged in sale transactions, structural reorganizations, or succession planning would do well to absorb the Court’s reasoning: tax valuations carry little weight unless they faithfully reflect the commercial circumstances of the transaction rather than resting on abstract assumptions.

Business Sale Valuation: The Facts in Issue

The dispute arose from a 2016 transaction in which three family trusts sold their shares in Punters Paradise Pty Ltd—an online wagering business—to News Corp for approximately $31 million. Shareholding was distributed as follows:

  • Pettett Trust: 60%
  • Kilgour Family Trust: 20%
  • Reuhl Family Trust: 20%

The business sale evaluation proceeded on arm’s length terms, subject to due diligence and included a working-capital adjustment on completion.

Each 20% minority holder sought access to the small business CGT concessions, requiring net assets to remain below a $6 million threshold. They argued that an interest of that size would naturally attract a material discount when assessed independently.

The Commissioner rejected this, contending that each 20% parcel formed part of a unified 100% transaction and should be valued at 20% of the $31 million consideration. The Court upheld this approach.

The Court’s Reasoning on Market Value

The Court reaffirmed the “willing buyer/willing seller” standard from Spencer v Commonwealth, anchoring it in the commercial realities before it. Two significant points emerge.

1. Foreseeable circumstances inform the valuation date

The statutory provisions require value to be assessed “just before” the contract is executed. The Court held that a valuer cannot disregard circumstances within contemplation at that point. As completion was a practical certainty, the negotiated consideration was the most reliable indicator of market value.

A purchaser’s willingness to pay a premium—whether for control, synergies, or strategic positioning—forms part of the valuation context and cannot be excluded.

2. Transactional terms prevail over theoretical discount adjustments

The taxpayers relied on conventional minority discount principles. The Court rejected this as commercially artificial, noting three features:

  • The shareholders had agreed to divest simultaneously and as a unified whole.
  • The purchaser sought complete ownership, making fragmented acquisitions irrelevant.
  • A 100% sale inherently supports the full attributed value of each parcel, regardless of size.

A notional purchaser would have had no rational basis for applying a minority discount. Each interest derived its value from participation in the aggregate transaction. Coordinated disposals can result in interests being valued above what a disaggregated analysis produces.

Business Sale Valuation Considerations for Owners and Advisers

  • Minority interests may carry greater value than assumed. Where a purchaser is motivated by control or synergistic benefits, the market value of a modest shareholding may exceed what a mechanical discount suggests. Advisers must ensure the full commercial context informs every business sale valuation exercise.
  • Contemporaneous records are essential. Documentation gathered during the transaction—negotiation correspondence, independent valuations, and evidence of the purchaser’s rationale—will be central to substantiating a tax position where CGT concessions are in issue.
  • CGT concession eligibility warrants early analysis. Owners intending to rely on small business concessions should review their position before binding steps are taken, including execution of heads of agreement. Structural adjustments may produce different outcomes, though anti-avoidance provisions must be assessed carefully.
  • Shareholder expectations must be aligned. Minority holders in private or family enterprises often assume their interests will be assessed in isolation. Kilgour confirms courts examine the transaction as a whole, and collective conduct among co-owners shapes how interests are valued.

Concluding Observations

Kilgour reinforces a foundational principle: a business sale valuation disconnected from genuine commercial conditions is unlikely to withstand scrutiny. Business owners and advisers should engage well before contractual commitments are made, ensuring business sale valuations are properly constructed and documented. Where CGT concessions are at stake, the difference between a defensible and an ill-considered valuation may prove both substantial and irreversible.

Need Help?

By working with us as your professional tax accountant and mortgage broker, you can be confident that your loans are structured to protect your tax position, maximise deductions, and avoid costly mistakes, giving you greater peace of mind and more control over your financial future.

Pitt Martin Group is a firm of Chartered Accountants, providing services including taxation, accounting, business consulting, self-managed superannuation funds, auditing and mortgage & finance. We spend hundreds of hours each year on training and researching new tax laws to ensure our clients can maximize legitimate tax benefit. Our contact information are phone +61292213345 or email info@pittmartingroup.com.au. Pitt Martin Group is located in the convenient transportation hub of Sydney’s central business district. Our honours include the 2018 CPA NSW President’s Award for Excellence, the 2020 Australian Small Business Champion Award Finalist, the 2021 Australia’s well-known media ‘Accountants Daily’ the Accounting Firm of the Year Award Finalist and the 2022 Start-up Firm of the Year Award Finalist, and the 2023 Hong Kong-Australia Business Association Business Award Finalist.

Pitt Martin Group qualifications include over fifteen years of professional experience in accounting industry, membership certification of the Chartered Accountants Australia and New Zealand (CA ANZ), membership certification of the Australian Society of Certified Practising Accountants (CPA), Registered Australia Tax Agents, certified External Examiner of the Law Societies of New South Wales, Victoria, and Western Australia Law Trust Accounts, membership certification of the Finance Brokers Association of Australia Limited (FBAA), Registered Agents of the Australian Securities and Investments Commission (ASIC), certified Advisor of accounting software such as XERO, QUICKBOOKS, MYOB, etc.

This content is for reference only and does not constitute advice on any individual or group’s specific situation. Any individual or group should take action only after consulting with professionals. Due to the timeliness of tax laws, we have endeavoured to provide timely and accurate information at the time of publication, but cannot guarantee that the content stated will remain applicable in the future. Please indicate the source when forwarding this content.
Read more
inherited property CGT

Inherited Property CGT: New ATO Guidelines

The Australian Taxation Office has released a Preliminary Tax Determination TD 2026/D1 which examines how residential real estate acquired through inherited property CGT is managed. Various sector specialists have labeled this a “hidden inheritance levy,” although the actual situation remains slightly more intricate than that description suggests. This preliminary advice concentrates on one particular facet of the regulations concerning the application of primary residence tax relief to inherited assets, potentially exposing legacy estates and heirs to heavy taxation if not structured correctly.

Below is what you should understand in functional terms.

Why TD 2026/D1 Is Significant

Under existing statutes, legal personal representatives or successors can potentially dispose of a departed person’s previous family residence without incurring inherited property CGT if specific criteria are satisfied. This tax break is exceptionally lucrative for dwellings held over decades, where accumulated paper profits might be immense.

To secure a total tax waiver, you generally must ensure the asset is sold within two years of the passing date (though the Commissioner may potentially prolong this window) or that the home served as the primary dwelling of certain eligible parties from the time of death until the final sale.

These eligible parties might include the surviving partner of the deceased individual, the successor disposing of a stake in the asset, or any person granted a right to reside in the dwelling via the deceased’s final testament.

The preliminary ATO guidance emphasizes this final category. Specifically, it questions what constitutes having “a right to occupy the dwelling under the deceased’s will.” To summarize, the ATO’s interpretation is that:

  • The entitlement to inhabit the property must be explicitly bestowed in the testament to a designated person.
  • Wide-ranging autonomous powers granted to executors, separate legal pacts, or even testamentary trusts (TTs) are considered inadequate in the Tax Office’s perspective.

For instance:

  • A testament granting an executor the choice to permit a member of family to inhabit the residence fails to satisfy this criterion.
  • A trustee of a TT who permits a successor to reside in the dwelling is viewed as independent of the testament and might spark inherited property CGT upon disposal.

Various legal and property professionals caution that this could compel households to offload residences within two years of a passing to avoid CGT, particularly in premium locations. Reflect on this: inheriting a $2 million residence with a capital increase of $1.5 million might expose the successors to $300,000–$600,000 in liabilities, depending on available concessions and income brackets.

Nevertheless, it remains vital to recognize that alternative methods exist for the asset disposal to qualify for a complete CGT exemptions.

Practical Strategies to Reduce CGT on Inherited Property

While awaiting the Taxation Office to conclude its advice in this field, there are maneuvers you can execute to shield your household’s wealth:

  • Analyze and modify your testament, particularly if you intend to grant specific parties the entitlement to inhabit a dwelling. Does the document currently offer this entitlement to uniquely identified successors?
  • Strategize the sale schedule – The two years waiver period persists, but if you receive a dwelling and plan to keep it longer, compare any possible inherited property CGT risk against incoming rental profits or family requirements. Partial CGT exemptions might still be accessible, but the statutes and math can be difficult.
  • Consult expert advisors, especially if your legacy strategy utilizes TTs. You will typically need to collaborate closely with tax and statutory consultants to organize the strategy effectively.
  • Observe market trends – Estate planning can overlap with market cycles. Rapid disposals might protect CGT exemptions, but this must be balanced against non-tax considerations.

The primary lesson is evident: estate planning is a sophisticated field and must be steered with precision to protect family assets and prevent accidental tax consequences.

Need Help?

By working with us as your professional tax accountant and mortgage broker, you can be confident that your loans are structured to protect your tax position, maximise deductions, and avoid costly mistakes, giving you greater peace of mind and more control over your financial future.

Pitt Martin Group is a firm of Chartered Accountants, providing services including taxation, accounting, business consulting, self-managed superannuation funds, auditing and mortgage & finance. We spend hundreds of hours each year on training and researching new tax laws to ensure our clients can maximize legitimate tax benefit. Our contact information are phone +61292213345 or email info@pittmartingroup.com.au. Pitt Martin Group is located in the convenient transportation hub of Sydney’s central business district. Our honours include the 2018 CPA NSW President’s Award for Excellence, the 2020 Australian Small Business Champion Award Finalist, the 2021 Australia’s well-known media ‘Accountants Daily’ the Accounting Firm of the Year Award Finalist and the 2022 Start-up Firm of the Year Award Finalist, and the 2023 Hong Kong-Australia Business Association Business Award Finalist.

Pitt Martin Group qualifications include over fifteen years of professional experience in accounting industry, membership certification of the Chartered Accountants Australia and New Zealand (CA ANZ), membership certification of the Australian Society of Certified Practising Accountants (CPA), Registered Australia Tax Agents, certified External Examiner of the Law Societies of New South Wales, Victoria, and Western Australia Law Trust Accounts, membership certification of the Finance Brokers Association of Australia Limited (FBAA), Registered Agents of the Australian Securities and Investments Commission (ASIC), certified Advisor of accounting software such as XERO, QUICKBOOKS, MYOB, etc.

This content is for reference only and does not constitute advice on any individual or group’s specific situation. Any individual or group should take action only after consulting with professionals. Due to the timeliness of tax laws, we have endeavoured to provide timely and accurate information at the time of publication, but cannot guarantee that the content stated will remain applicable in the future. Please indicate the source when forwarding this content.
Read more
AI-Generated Tax Advice: Efficiency Boost or Potential Pitfall?

AI-Generated Tax Advice: Efficiency Boost or Potential Pitfall?

For business owners and investors, spare time is scarce. It is hardly surprising that many people now rely on AI tools such as Chat GPT for quick tax guidance on deductions, super contributions or structural ideas. The responses appear confident, arrive in seconds and cost nothing. What might possibly go wrong? Quite a bit.

Australia’s tax and superannuation environment is detailed, highly dependent on individual facts and subject to constant change. AI technology can be a handy starting point but using it as the basis for real decisions can leave you exposed to reviews, penalties and unintended financial consequences. We are increasingly seeing cases where AI-generated guidance has led clients down the wrong path and requires professional correction.

Where AI Can Assist (and Where It Falls Short)

AI is very capable of explaining simple concepts in everyday language. It can outline what negative gearing involves, describe the difference between concessional and non-concessional contributions, or remind you to think about documentation. Rely in AI tools in tax can save time and help you prepare more focused questions.

The difficulty begins when AI shifts from general explanations to something that resembles advice.

Tax and super outcomes depend on your individual circumstances—your income, business structure, age, residency, assets, timing, and long-term objectives. AI tools do not have access to these factors unless you disclose them, and in most cases you should not. Even when detailed information is provided, they cannot exercise professional judgement or weigh risks and trade-offs in the way an experienced adviser can.

The Accuracy Problem: Authoritative, yet Incorrect

AI platforms are known to “hallucinate”, producing statements that sound convincing but are wrong or incomplete. In practice, this can involve:
• Recommending deductions that are unavailable in your situation.
• Calculating capital gains tax incorrectly or overlooking integrity provisions.
• Suggesting super strategies that exceed caps or failing eligibility tests.
• Citing legislation, cases, rulings or concessions that are outdated or entirely fictional.

To a non-expert these mistakes may be invisible, but they are usually obvious to the ATO, the courts and seasoned practitioners.

A recent decision of the Administrative Review Tribunal highlights these dangers. In Smith and Commissioner of Taxation [2026] ARTA 25, the taxpayer appeared to depend on AI tools to locate authorities supporting their position, and the Tribunal dismissed that approach. Some of the cases were imaginary, while others were irrelevant to the issue at hand.

If the user of the tool fails to confirm the cases exist and read them to check relevance, “the Tribunal’s resources are being wasted, as the Tribunal must look for cases that don’t exist and read cases that have no relevance at all”.

ATO Attention is Increasing, not Decreasing

The ATO is not hostile to AI—they use it themselves for analytics and fraud detection. However, for taxpayers, the ATO’s misinformation guidance makes clear that using AI in tax may deliver false, inaccurate, incomplete or outdated material. Their message is simple: check everything or accept the consequences. Surveys indicate many businesses seek AI accounting assistance first, only to have professionals unravel the problems later, burning extra time and money.

ATO AI transparency statement | Australian Taxation Office

Protect yourself from misinformation and disinformation | Australian Taxation Office

Where inaccuracies are identified, the ATO typically revises the return, charges interest, and may also apply penalties—regardless of whether the mistake arose from misunderstanding or from relying on AI-generated tax information rather than any deliberate action.

This issue is becoming particularly apparent in areas such as working-from-home expenses, rental property claims, and compliance obligations for SMSFs.

Superannuation: High Stakes, Minimal Room for Error

Super is an area where AI suggestions can be particularly hazardous. Self-managed funds operate within strict boundaries. AI frequently misses matters such as eligibility, timing, purpose requirements and investment limits. The consequences can include breaches, forced reversals of transactions and penalties that reach thousands of dollars.

Errors in super can also cause permanent damage to retirement savings.

Data Security and Privacy

There is another practical exposure people often forget: entering personal or financial data into AI systems. Once the information is submitted, control over how it may be stored or used is lost. The privacy and fraud risks are simply not worth accepting.

A Better Way: AI with Professional Guidance

AI delivers the greatest value when used as a research and learning tool rather than as the final authority. It can help build general knowledge, but any significant tax or superannuation decision should be assessed in the context of your full financial position and long-term objectives.

In our practice, we encourage clients to ask questions early, explore potential strategies, and discuss them with us before taking action. Addressing issues upfront is almost always simpler and far less costly than fixing problems after the fact.

The bottom line is straightforward: AI can be useful in tax, but it is not your accountant. When safeguarding your wealth and maintaining compliance, personalized professional advice remains critical.

Need Help?

By working with us as your professional tax accountant and mortgage broker, you can be confident that your loans are structured to protect your tax position, maximise deductions, and avoid costly mistakes, giving you greater peace of mind and more control over your financial future.

Pitt Martin Group is a firm of Chartered Accountants, providing services including taxation, accounting, business consulting, self-managed superannuation funds, auditing and mortgage & finance. We spend hundreds of hours each year on training and researching new tax laws to ensure our clients can maximize legitimate tax benefit. Our contact information are phone +61292213345 or email info@pittmartingroup.com.au. Pitt Martin Group is located in the convenient transportation hub of Sydney’s central business district. Our honours include the 2018 CPA NSW President’s Award for Excellence, the 2020 Australian Small Business Champion Award Finalist, the 2021 Australia’s well-known media ‘Accountants Daily’ the Accounting Firm of the Year Award Finalist and the 2022 Start-up Firm of the Year Award Finalist, and the 2023 Hong Kong-Australia Business Association Business Award Finalist.

Pitt Martin Group qualifications include over fifteen years of professional experience in accounting industry, membership certification of the Chartered Accountants Australia and New Zealand (CA ANZ), membership certification of the Australian Society of Certified Practising Accountants (CPA), Registered Australia Tax Agents, certified External Examiner of the Law Societies of New South Wales, Victoria, and Western Australia Law Trust Accounts, membership certification of the Finance Brokers Association of Australia Limited (FBAA), Registered Agents of the Australian Securities and Investments Commission (ASIC), certified Advisor of accounting software such as XERO, QUICKBOOKS, MYOB, etc.

This content is for reference only and does not constitute advice on any individual or group’s specific situation. Any individual or group should take action only after consulting with professionals. Due to the timeliness of tax laws, we have endeavoured to provide timely and accurate information at the time of publication, but cannot guarantee that the content stated will remain applicable in the future. Please indicate the source when forwarding this content.

By Sally Tran @ Pitt Martin Tax

Read more