Skip to main content Skip to search

Archives for English

Discretionary Trusts and the Proposed 30% Minimum Tax

The Australian Government has proposed a significant change to the taxation of discretionary trusts, commonly known as family trusts.

From 1 July 2028, the Government proposes to introduce a 30% minimum tax on the taxable income of discretionary trusts, subject to certain exclusions. The Government has also proposed a three-year rollover period from 1 July 2027 to help eligible businesses and taxpayers restructure their affairs if required.

While discretionary trusts remain a common structure for Australian families, business owners and investors, the proposed changes may affect the way some trusts distribute income and manage their tax affairs.

It is important to note that the proposed 30% minimum tax is not yet law. Treasury is consulting on the design and implementation of the proposed reforms, so some details may change before legislation is introduced.

What Is a Discretionary Trust?

A discretionary trust is a trust structure where the trustee generally has discretion over how trust income and capital are distributed among eligible beneficiaries.

Discretionary trusts are commonly used in Australia for:

  • Operating family businesses
  • Holding investment assets
  • Managing family wealth
  • Asset protection
  • Succession planning
  • Estate planning
  • Distributing income among family members

One of the key features of a discretionary trust is its flexibility. Subject to the trust deed and applicable tax rules, the trustee can generally determine which beneficiaries receive distributions each year.

The proposed 30% minimum tax on discretionary trusts may reduce some of this tax flexibility for affected family groups.

What Is the Proposed 30% Minimum Tax?

Under the Government’s proposal, trustees of discretionary trusts would generally be required to pay a minimum tax rate of 30% on the trust’s taxable income from 1 July 2028.

The proposed measure is intended to ensure that income distributed through discretionary trusts is subject to a minimum level of tax and to reduce opportunities for income splitting.

The Government has stated that the reform is intended to bring the taxation of certain trust income more closely into line with the tax rates applying to Australian workers and families who earn income from employment.

How would the tax paid by the trustee be treated?

The proposal includes a mechanism intended to recognise tax already paid by the trustee.

Where trust income is distributed to individuals or certain other non-corporate beneficiaries, those beneficiaries would generally receive a non-refundable tax offset for the tax paid by the trustee.

However, the proposed treatment is different for corporate beneficiaries. This is an important issue for family groups that currently use companies as beneficiaries of discretionary trusts.

The exact operation of the proposed rules will depend on the final legislation.

Will All Discretionary Trusts Be Affected?

No.

The Government has proposed a number of exclusions from the 30% minimum tax regime.

The proposed exclusions include certain:

  • Fixed trusts
  • Widely held trusts
  • Complying superannuation funds
  • Charitable trusts
  • Deceased estates
  • Special disability trusts
  • Genuine testamentary trusts

The Government has also indicated that primary production income and certain income relating to vulnerable minors would be excluded.

The Government estimates that more than 90% of small businesses are not expected to be affected by the proposed reform. However, the impact on an individual taxpayer will depend on the type of trust, the trust’s activities, the beneficiaries and the way income is distributed.

How Could the Proposed Changes Affect Family Businesses?

The impact is likely to be most relevant for family groups that actively use the flexibility of discretionary trusts for tax and business planning.

For example, some family trusts distribute income to different family members depending on their individual circumstances. Other trusts distribute income to a corporate beneficiary to retain funds within the broader business structure.

The proposed minimum tax may change the tax outcome of these arrangements.

Corporate beneficiaries

The treatment of corporate beneficiaries is likely to be particularly important.

Under the proposal, corporate beneficiaries would generally not receive the same non-refundable tax offset for tax paid by the trustee.

This could result in additional tax being payable where income is distributed from a discretionary trust to a company.

As a result, family groups with a discretionary trust and corporate beneficiary should review how their current structure operates and consider whether the proposed rules could affect future distributions.

However, no changes should be implemented solely on the basis of the current proposal while the legislation remains under development.

Could the Changes Affect Tax Losses?

Potentially.

Many family groups use discretionary trusts as part of a broader structure involving businesses, investments and multiple beneficiaries. The proposed minimum tax could affect the way taxable income and existing tax losses are managed within some structures.

The actual outcome will depend on the nature of the trust’s income, the type of losses involved and the final rules.

This means that taxpayers should consider the overall tax position of the family group, rather than looking at the trust in isolation.

Proposed Rollover Relief for Restructuring

The Government has also proposed three years of rollover relief from 1 July 2027 to assist small businesses and other taxpayers who choose to restructure out of discretionary trusts.

The proposed relief may make it easier for some eligible taxpayers to move from a discretionary trust into an alternative structure, such as a company or fixed trust, without immediately triggering certain income tax or capital gains tax consequences.

However, a trust restructure can involve much more than income tax.

Before changing an existing structure, taxpayers may need to consider:

  • Capital gains tax
  • Stamp duty
  • Existing loans and financing arrangements
  • Bank requirements
  • Asset ownership
  • Commercial contracts
  • Licences and registrations
  • Existing tax attributes
  • Estate planning
  • Asset protection

Professional advice should therefore be obtained before implementing any significant restructure.

When Will the 30% Minimum Tax Start?

The proposed start date is 1 July 2028.

The Government has also proposed rollover relief for three years from 1 July 2027 for eligible taxpayers who choose to restructure their affairs.

This means affected family groups have time to understand the proposed changes and consider their options.

There is generally no need to make immediate structural changes simply because the proposal has been announced.

Is the 30% Minimum Tax on Discretionary Trusts Law Yet?

No.

This is an important point for trustees and business owners.

The 30% minimum tax is currently a proposed tax reform, rather than an enacted law. Treasury released a consultation paper in July 2026 seeking feedback on the implementation and design of the proposed discretionary trust reforms.

The final legislation may therefore differ from the current proposal.

Taxpayers should be careful when making long-term restructuring decisions based on proposed legislation that has not yet been enacted.

What Should Discretionary Trust Trustees Do Now?

For most trustees, the best approach is to review, monitor and plan, rather than immediately restructure.

Consider reviewing:

  1. How your trust currently earns income
    Determine whether the trust mainly receives business income, investment income, capital gains or other types of income.
  2. Who receives trust distributions
    Review whether income is distributed to individuals, companies or other entities.
  3. Whether a corporate beneficiary is used
    If a company regularly receives trust distributions, consider how the proposed minimum tax could affect the overall tax position.
  4. Existing tax losses and carried-forward amounts
    Consider whether the proposed rules could affect the use of existing tax attributes.
  5. The purpose of the trust structure
    Tax is only one consideration. Asset protection, succession planning, estate planning and business flexibility may remain important.
  6. Potential restructuring options
    If the current structure may become less suitable, consider whether a company, fixed trust or another structure could be appropriate.

Any restructuring decision should take into account, tax, legal, commercial and family considerations.

Should You Restructure Your Family Trust Now?

Not necessarily.

The proposed 30% minimum tax on discretionary trusts is an important development, but the legislation has not yet been finalised.

For many families, discretionary trusts provide benefits beyond tax planning. These may include asset protection, succession planning and flexibility in managing family businesses and investments.

Accordingly, the right response will depend on the circumstances of each family group.

Rather than restructuring immediately, trustees should monitor the legislation, understand the potential impact and seek professional advice when the final rules become clearer.

Key Takeaways

The proposed changes represent a significant development for Australian discretionary trusts and family businesses.

The key points are:

  • A 30% minimum tax is proposed for discretionary trusts from 1 July 2028.
  • Certain trusts and types of income are proposed to be excluded.
  • The Government expects more than 90% of small businesses to be unaffected.
  • Corporate beneficiaries may be an important area of concern under the proposed rules.
  • Three years of proposed rollover relief would be available from 1 July 2027 to assist eligible restructures.
  • The proposal is not yet law, and the final rules may change.

For trustees and business owners, now is a good time to review the purpose and structure of existing discretionary trusts and consider whether the proposed reforms could affect future distributions.

If you operate a family business or hold investments through a discretionary trust, we recommend reviewing your structure before making any significant changes. Our team can help you assess the potential tax implications and consider whether your existing structure remains appropriate as the proposed legislation develops.

Need Help?

By working with us as your professional tax accountant and mortgage broker, you can be confident that your loans are structured to protect your tax position, maximise deductions, and avoid costly mistakes, giving you greater peace of mind and more control over your financial future.

Pitt Martin Group is a firm of Chartered Accountants, providing services including taxation, accounting, business consulting, self-managed superannuation funds, auditing and mortgage & finance. We spend hundreds of hours each year on training and researching new tax laws to ensure our clients can maximize legitimate tax benefit. Our contact information are phone +61292213345 or email info@pittmartingroup.com.au. Pitt Martin Group is located in the convenient transportation hub of Sydney’s central business district. Our honours include the 2018 CPA NSW President’s Award for Excellence, the 2020 Australian Small Business Champion Award Finalist, the 2021 Australia’s well-known media ‘Accountants Daily’ the Accounting Firm of the Year Award Finalist and the 2022 Start-up Firm of the Year Award Finalist, and the 2023 Hong Kong-Australia Business Association Business Award Finalist.

Pitt Martin Group qualifications include over fifteen years of professional experience in accounting industry, Registered Australia Tax Agents, membership certification of the Chartered Accountants Australia and New Zealand (CA ANZ), certified External Examiner of the Law Societies of New South Wales, Victoria, and Western Australia Law Trust Accounts, membership certification of the Finance Brokers Association of Australia Limited (FBAA), Registered Agents of the Australian Securities and Investments Commission (ASIC), certified Advisor of accounting software such as XERO, QUICKBOOKS, MYOB, etc.

This content is for reference only and does not constitute advice on any individual or group’s specific situation. Any individual or group should take action only after consulting with professionals. Due to the timeliness of tax laws, we have endeavoured to provide timely and accurate information at the time of publication, but cannot guarantee that the content stated will remain applicable in the future. Please indicate the source when forwarding this content.

By Yvonne Shao @ Pitt Martin Tax

Read more
Navigating the 2026–27 Car Thresholds

Navigating the 2026 – 2027 Car Thresholds: What Every Australian Business Needs to Know

If your business is planning to buy or lease a vehicle in the new financial year, the updated 2026–27 car thresholds from the Australian Taxation Office (ATO) are worth a look before you sign anything. They shape three things that matter to your bottom line: depreciation, GST recovery, and whether Luxury Car Tax (LCT) applies.

For vehicles first used or leased from 1 July 2026, the car limit, GST credit cap, and LCT thresholds have all increased with indexation. Understanding how they interact can help you time a purchase and avoid surprises at tax time.

The Car Limit: The Depreciation Cap

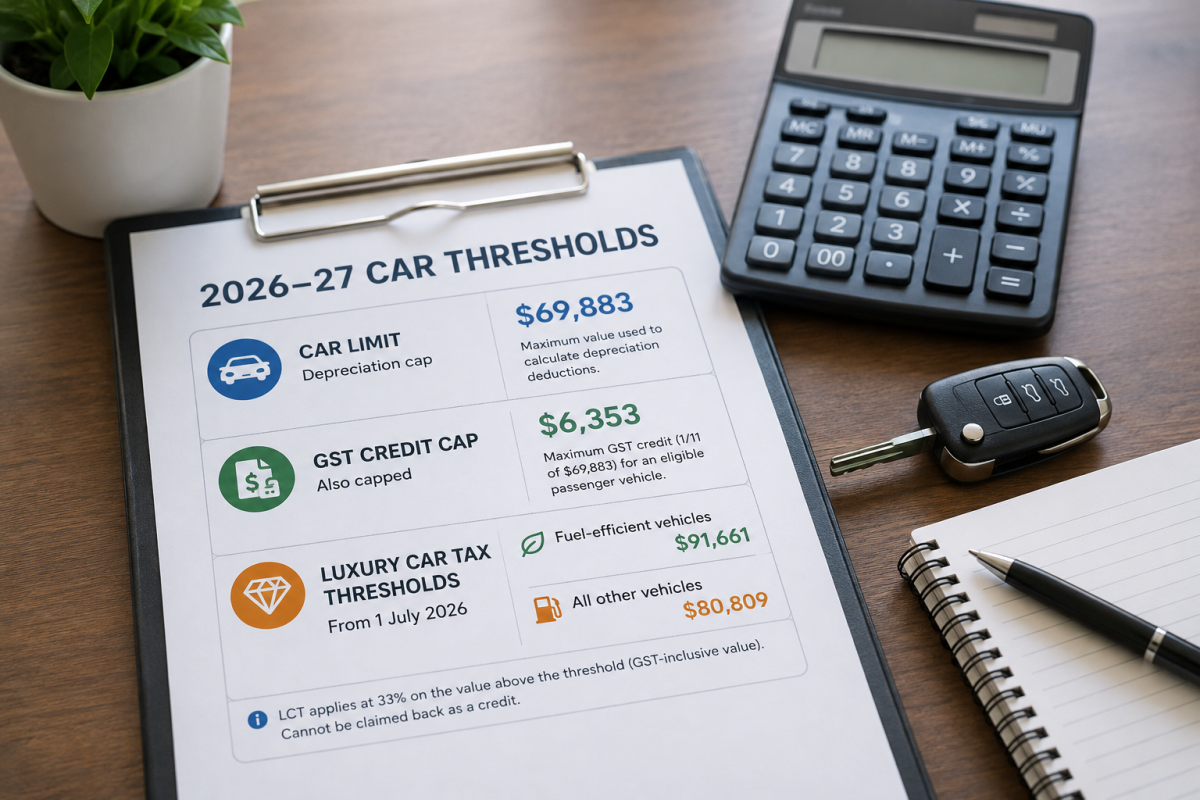
For 2026–27, the ATO car limit is $69,883, the maximum value used to calculate depreciation deductions for a passenger vehicle, regardless of actual purchase price. Buy above this and the excess generally cannot be depreciated. There may be good commercial reasons to buy something pricier, but beyond the car limit, extra spend typically produces no additional tax benefit.

A few points worth noting:

  • Mixed use: If a vehicle is used for both business and private purposes, you can only claim the business-use portion. A valid logbook, kept for a continuous 12-week period with odometer readings, is essential evidence if the ATO reviews your claim.
  • Depreciation method: Businesses may be eligible for simplified small business depreciation rules, allowing accelerated deductions. Confirm eligibility with your tax agent before purchase.
  • Timing: The applicable car limit is set by the income year the car is first used or held ready for use, not the invoice date. This matters if delivery slips past 1 July.

GST Credits: Also Capped

Businesses registered for GST can generally claim GST credits on vehicles bought for business use, but this is also capped by reference to the car limit. Once the price exceeds the limit, the credit is capped at one-eleventh of the limit, not one-eleventh of the actual price.

For 2026–27, the maximum GST credit on an eligible passenger vehicle is $6,353 (one-eleventh of $69,883), regardless of actual cost, and this applies to fuel-efficient and non-fuel-efficient vehicles alike.

Some flow-on consequences:

  • Selling later: GST is generally payable on the full sale price when the vehicle is sold, even though the credit claimed at purchase was capped. This asymmetry can catch owners off guard.
  • BAS reporting: Only the car-limit amount (or its business-use proportion) is reported at label G10, with the capped credit at label 1B.
  • Time limits: GST credits must generally be claimed within four years, so reconcile purchases promptly.
  • Cash flow: The credit is often a meaningful short-term benefit, worth weighing against financing or leasing.

Luxury Car Tax Thresholds Rise From 1 July 2026

Luxury car tax rate and thresholds (LCT) is a separate consideration, with its own thresholds, also increased for 2026–27:

  • $91,661 for fuel-efficient vehicles
  • $80,809 for all other vehicles

Where the GST-inclusive value exceeds the relevant threshold, LCT generally applies at 33% on the value above it. Unlike GST, LCT cannot be claimed back as a credit, even for vehicles used entirely for business.

The gap between the two thresholds is increasingly relevant: more hybrid, plug-in hybrid and electric models now qualify for the higher threshold, reducing LCT versus an equivalent petrol or diesel model. This is worth weighing for fleets or client-facing vehicles. Check the current ATO definition before assuming a model qualifies, as the eligibility test has tightened in recent years.

Planning Ahead

Since these thresholds apply to any vehicle first used or leased from 1 July 2026, now is a good time to review planned purchases. Before committing, work through:

  • Total after-tax cost of ownership: depreciation, GST credits, LCT, financing, insurance and running costs, not just the drive-away price.
  • Buy versus lease: Outright purchase, chattel mortgage, novated leasing and operating leases each carry different depreciation, GST and cash flow implications, depending on turnover, cash position and vehicle use.
  • Business-use percentage: the records needed to support it, including a logbook, odometer readings, and trip diary where relevant.
  • Cash flow timing: whether to bring a purchase forward before 30 June or defer until after 1 July.

Key Takeaways

A business vehicle can be a significant investment. While tax considerations should not be the sole factor in your decision, they can play an important role in determining the overall cost of ownership.

Before making a purchase, it is worth speaking with your accountant to assess the potential tax implications based on your individual circumstances. Planning ahead can help you make the most of available tax concessions, avoid unexpected costs and ensure the purchase supports your broader business strategy.

For more information, refer to the ATO’s Small Business Newsroom: Car thresholds from 1 July | Australian Taxation Office, or contact our team to discuss how these changes may apply to your business.

Need Help?

By working with us as your professional tax accountant and mortgage broker, you can be confident that your loans are structured to protect your tax position, maximise deductions, and avoid costly mistakes, giving you greater peace of mind and more control over your financial future.

Pitt Martin Group is a firm of Chartered Accountants, providing services including taxation, accounting, business consulting, self-managed superannuation funds, auditing and mortgage & finance. We spend hundreds of hours each year on training and researching new tax laws to ensure our clients can maximize legitimate tax benefit. Our contact information are phone +61292213345 or email info@pittmartingroup.com.au. Pitt Martin Group is located in the convenient transportation hub of Sydney’s central business district. Our honours include the 2018 CPA NSW President’s Award for Excellence, the 2020 Australian Small Business Champion Award Finalist, the 2021 Australia’s well-known media ‘Accountants Daily’ the Accounting Firm of the Year Award Finalist and the 2022 Start-up Firm of the Year Award Finalist, and the 2023 Hong Kong-Australia Business Association Business Award Finalist.

Pitt Martin Group qualifications include over fifteen years of professional experience in accounting industry, Registered Australia Tax Agents, membership certification of the Chartered Accountants Australia and New Zealand (CA ANZ), certified External Examiner of the Law Societies of New South Wales, Victoria, and Western Australia Law Trust Accounts, membership certification of the Finance Brokers Association of Australia Limited (FBAA), Registered Agents of the Australian Securities and Investments Commission (ASIC), certified Advisor of accounting software such as XERO, QUICKBOOKS, MYOB, etc.

This content is for reference only and does not constitute advice on any individual or group’s specific situation. Any individual or group should take action only after consulting with professionals. Due to the timeliness of tax laws, we have endeavoured to provide timely and accurate information at the time of publication, but cannot guarantee that the content stated will remain applicable in the future. Please indicate the source when forwarding this content.

By Nora Pham @ Pitt Martin Tax

Read more
Changes to SMSF Borrowing Rules: New Restrictions on Property Purchases

Changes to SMSF Borrowing Rules: New Restrictions on Property Purchases

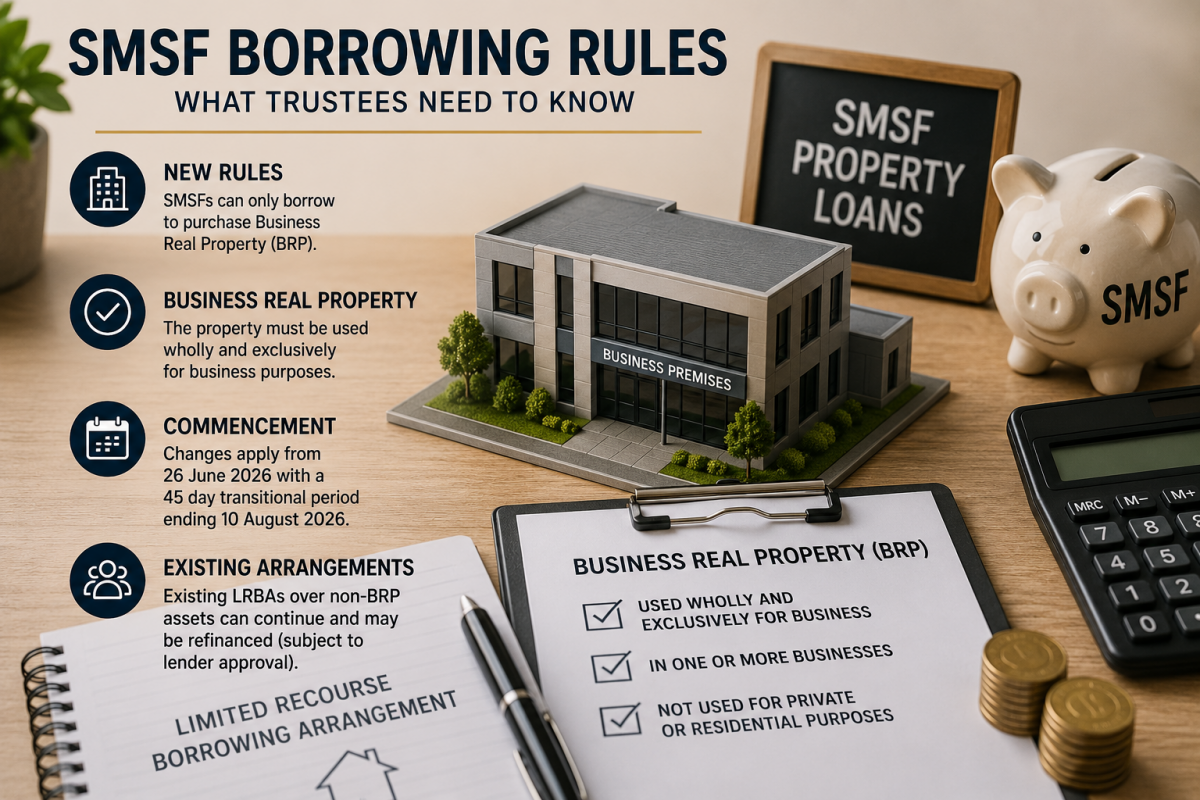
Significant changes to Self-Managed Super Fund (SMSF) borrowing rules have changed the types of property that SMSFs can acquire using a Limited Recourse Borrowing Arrangement (LRBA).

The changes became law on 26 June 2026 and, following a 45-day transitional period ending on 10 August 2026, generally restrict new SMSF property borrowing to property that meets the definition of business real property (BRP).

For SMSF trustees considering purchasing property through their super fund, understanding the new rules is essential before entering into a contract or arranging finance.

What Has Changed With SMSF Borrowing Rules?

SMSFs have traditionally been permitted to borrow in limited circumstances, including through an LRBA to acquire a single acquirable asset.

Property has been one of the most common assets purchased using these arrangements. Previously, there was no specific legislative restriction requiring the property acquired under an LRBA to be commercial or business property.

The new rules significantly narrow this position.

Where an SMSF uses borrowing to purchase real property under the new rules, the property generally needs to satisfy the business real property definition.

In practical terms, this means SMSF trustees considering an LRBA need to determine whether the property qualifies as business real property before proceeding with the purchase.

What Is Business Real Property for an SMSF?

Business real property is broadly real property that is used wholly and exclusively in one or more businesses.

An important point is that the test focuses primarily on how the property is actually used, rather than simply its zoning, appearance or original design.

This means the distinction is not necessarily as simple as:

  • Residential property = not eligible
  • Commercial property = eligible

The actual use of the property can be critical.

For example, a residential-style terrace house that is used wholly and exclusively as a medical practice may potentially satisfy the business real property requirements, despite originally being designed as a residence.

Conversely, a property that appears commercial may not necessarily qualify if it is not used wholly and exclusively for business purposes.

Can an SMSF Still Borrow to Buy Residential Property?

Under the new SMSF borrowing rules, an SMSF will generally not be able to use a new LRBA to purchase ordinary residential investment property that does not satisfy the business real property definition.

However, describing the changes simply as a “ban on SMSFs borrowing to buy residential property” can be misleading.

The relevant issue is the use of the property.

A residentially designed property may potentially qualify if it is used wholly and exclusively for business purposes and otherwise satisfies the business real property requirements.

Specialist advice should be obtained before relying on this treatment.

What About Mixed-Use Property?

Mixed-use properties require particular attention.

The business real property definition generally requires the property to be used wholly and exclusively for business purposes.

For example, consider a property on a single title containing:

  • a retail shop on the ground floor; and
  • a residential apartment upstairs.

Even though part of the property is clearly commercial, the residential component may prevent the entire property from satisfying the business real property definition.

SMSF trustees considering mixed-use properties should therefore obtain advice before signing a contract or entering into an LRBA.

When Did the New SMSF Borrowing Rules Start?

The changes became law on 26 June 2026.

However, the legislation provided a 45-day transitional period ending on 10 August 2026.

The transitional provisions may allow certain arrangements involving non-business real property that were already being implemented to continue, including circumstances where settlement takes place after 10 August 2026, provided the relevant arrangement to purchase the property was entered into on or before the transitional deadline.

Whether a particular transaction qualifies for the transitional treatment will depend on the specific circumstances and documentation.

SMSF trustees who entered into an arrangement involving non-BRP property before the deadline but had not completed settlement by 10 August 2026 should obtain specialist SMSF legal advice.

What Happens to Existing SMSF LRBAs?

Importantly, the new rules do not automatically require existing SMSF borrowing arrangements involving non-business real property to be unwound.

Existing LRBAs over non-BRP assets can generally continue under the updated rules.

The legislation also allows existing arrangements to be refinanced, subject to the relevant legislative requirements as well as lender availability and credit approval.

This is particularly important for SMSFs that already hold residential investment property through an LRBA.

Trustees should nevertheless obtain advice before refinancing or materially changing an existing borrowing arrangement, as changes to the structure or terms may have unintended SMSF compliance consequences.

Key Questions for SMSF Trustees

Before using an SMSF to borrow for a property purchase, trustees should consider:

  1. Does the property qualify as business real property?
  2. Is the property used wholly and exclusively for business purposes?
  3. Is there any residential or private use of the property?
  4. Does the proposed borrowing satisfy the LRBA requirements?
  5. Does the property meet the single acquirable asset rules?
  6. Is the purchase permitted under the SMSF’s trust deed and investment strategy?
  7. Are related-party acquisition and leasing rules relevant?
  8. If the arrangement began before 10 August 2026, do the transitional provisions apply?

These issues should ideally be reviewed before the SMSF signs a property contract, as correcting an incorrectly structured SMSF property transaction after signing can be difficult and costly.

Example: Residential Investment Property

An SMSF wants to borrow $600,000 under an LRBA to purchase an apartment that will be rented to an unrelated family as their home.

The apartment is being used for residential purposes rather than wholly and exclusively in a business.

Under the new borrowing restrictions, the property would generally not satisfy the business real property requirement for a new LRBA.

Example: Residential-Style Property Used as a Medical Practice

An SMSF is considering purchasing a terrace house that has been converted into medical consulting rooms.

Although the building was originally designed as residential accommodation, it is now used wholly and exclusively to operate a medical practice.

Subject to the particular circumstances and the other SMSF requirements being satisfied, the property may potentially qualify as business real property.

This illustrates why the new rules should not simply be viewed as a distinction between “residential” and “commercial” property.

What Should SMSF Trustees Do Before Borrowing?

SMSF property transactions involving LRBAs are already highly regulated, and the new borrowing restrictions add another important consideration.

Before entering into a new LRBA, trustees should obtain appropriate SMSF, legal, tax and financial advice to confirm that:

  • the proposed property satisfies the business real property requirements;
  • the LRBA has been correctly structured;
  • the acquisition complies with the SIS Act and related SMSF rules;
  • the fund’s trust deed and investment strategy permit the transaction; and
  • any related-party transactions are appropriately structured.

This review should take place before contracts and borrowing documents are signed.

Frequently Asked Questions

Can an SMSF still borrow money to buy property?

Yes. SMSFs can still borrow in limited circumstances through an LRBA, but the new rules restrict the types of real property that can be acquired using new borrowing arrangements.

Can an SMSF borrow to buy a residential investment property?

Generally, a new LRBA cannot be used to acquire ordinary residential investment property that does not qualify as business real property.

Can an SMSF borrow to buy commercial property?

Potentially, yes. However, simply describing a property as “commercial” does not automatically mean it qualifies. The property needs to satisfy the relevant business real property requirements.

Can an SMSF buy business premises using an LRBA?

Potentially, yes, provided the property qualifies as business real property and all other LRBA, SMSF and superannuation law requirements are satisfied.

Can an SMSF keep residential property already purchased through an LRBA?

The updated rules allow existing LRBAs involving non-BRP assets to continue, subject to the applicable requirements.

Can an existing SMSF residential property loan be refinanced?

Existing arrangements may be refinanced under the updated rules, subject to the legislative requirements, lender availability and credit approval.

Does property zoning determine whether it is business real property?

Not necessarily. The business real property test focuses significantly on the use of the property, rather than simply its zoning, appearance or original design.

Need Advice About an SMSF Property Purchase?

The changes to SMSF borrowing rules make it increasingly important to review a proposed property acquisition before signing a contract or arranging finance.

If you are considering purchasing property through your SMSF, particularly using an LRBA, professional advice can help determine whether the property qualifies under the new rules and whether the proposed structure complies with Australia’s superannuation and tax requirements.

Need Help?

By working with us as your professional tax accountant and mortgage broker, you can be confident that your loans are structured to protect your tax position, maximise deductions, and avoid costly mistakes, giving you greater peace of mind and more control over your financial future.

Pitt Martin Group is a firm of Chartered Accountants, providing services including taxation, accounting, business consulting, self-managed superannuation funds, auditing and mortgage & finance. We spend hundreds of hours each year on training and researching new tax laws to ensure our clients can maximize legitimate tax benefit. Our contact information are phone +61292213345 or email info@pittmartingroup.com.au. Pitt Martin Group is located in the convenient transportation hub of Sydney’s central business district. Our honours include the 2018 CPA NSW President’s Award for Excellence, the 2020 Australian Small Business Champion Award Finalist, the 2021 Australia’s well-known media ‘Accountants Daily’ the Accounting Firm of the Year Award Finalist and the 2022 Start-up Firm of the Year Award Finalist, and the 2023 Hong Kong-Australia Business Association Business Award Finalist.

Pitt Martin Group qualifications include over fifteen years of professional experience in accounting industry, Registered Australia Tax Agents, membership certification of the Chartered Accountants Australia and New Zealand (CA ANZ), certified External Examiner of the Law Societies of New South Wales, Victoria, and Western Australia Law Trust Accounts, membership certification of the Finance Brokers Association of Australia Limited (FBAA), Registered Agents of the Australian Securities and Investments Commission (ASIC), certified Advisor of accounting software such as XERO, QUICKBOOKS, MYOB, etc.

This content is for reference only and does not constitute advice on any individual or group’s specific situation. Any individual or group should take action only after consulting with professionals. Due to the timeliness of tax laws, we have endeavoured to provide timely and accurate information at the time of publication, but cannot guarantee that the content stated will remain applicable in the future. Please indicate the source when forwarding this content.

Read more

High Court Clarifies Trust Distribution Rules

The High Court has recently delivered an important decision for private business groups using discretionary trusts and corporate beneficiaries.

In Commissioner of Taxation v Bendel [2026] HCA 18, decided on 10 June 2026, the High Court rejected the ATO’s longstanding position that an unpaid present entitlement (UPE) owed by a trust to a corporate beneficiary will automatically be treated as a loan for Division 7A purposes.

Division 7A is designed to prevent private companies from providing benefits to shareholders or their associates through payments, loans or debt forgiveness without appropriate tax consequences. Where Division 7A applies, the benefit may be treated as an unfranked dividend.

What does the Bendel decision mean for UPEs?

Discretionary trusts are commonly used in private business and investment structures. A trust may distribute income to a corporate beneficiary so the income is taxed at the applicable company tax rate, while the cash remains in the trust to fund working capital, investments or business growth.

Historically, the ATO considered that where the corporate beneficiary’s entitlement remained unpaid, the UPE could constitute a Division 7A loan. Businesses therefore often needed to enter into complying Division 7A loan arrangements, charge the benchmark interest rate and make minimum yearly repayments to avoid a deemed unfranked dividend.

The High Court has now confirmed that an unpaid trust distribution does not, by itself, constitute a loan merely because the corporate beneficiary has not demanded payment.

This is significant for private groups that have retained trust distributions within the trust rather than transferring the cash to the corporate beneficiary. The decision may reduce the need for some groups to treat UPEs as Division 7A loans, providing greater certainty and potentially reducing administration and compliance costs.

However, the outcome will still depend on the specific facts and arrangements of each trust.

What about existing Division 7A loans?

Following the decision, the ATO released a Decision Impact Statement on 26 June 2026, confirming that it will generally administer the law consistently with the High Court’s decision.

Importantly, businesses should not assume that existing Division 7A loan arrangements can simply be cancelled.

Where a UPE has already been dealt with in a way that created a formal Division 7A loan, the loan remains a loan according to its legal character. Any applicable interest and minimum yearly repayment requirements will generally continue until the loan is repaid or the relevant loan term ends.

Therefore, businesses with existing Division 7A loan agreements should review their arrangements carefully before making any changes.

Does Bendel remove other tax risks?

No. The Bendel decision provides important clarity on UPEs, but it does not remove all Division 7A or tax integrity concerns.

For example, where a trust distributes income to a corporate beneficiary but the trust funds are subsequently used to provide a payment, loan or other benefit to a shareholder of the company or an associate, other Division 7A provisions may still apply.

Section 100A also remains relevant. These rules can potentially apply where income is appointed to one beneficiary but, under a reimbursement agreement, the economic benefit of that income is enjoyed by another party.

The application of these provisions depends heavily on the facts. The Bendel decision should therefore not be treated as a blanket exemption from Division 7A, section 100A or other tax integrity rules.

What should private groups do now?

The Bendel decision provides a good opportunity for private groups to review their trust structures and how UPEs have been managed.

Businesses with corporate beneficiaries should consider whether:

  • trust distribution resolutions have been properly prepared and documented;
  • UPEs have been correctly recorded in the accounting records;
  • any UPEs have subsequently been converted into loans;
  • trust funds have been used for the benefit of shareholders or their associates; and
  • section 100A or other Division 7A provisions may apply.

This review is particularly important for arrangements established under the ATO’s previous approach to UPEs.

Proposed 30% minimum tax on discretionary trusts

The Bendel decision also needs to be considered alongside the Government’s proposed changes to the taxation of discretionary trusts.

The Government has proposed a 30% minimum tax rate on the taxable income of discretionary trusts from 1 July 2028, subject to certain exclusions. Under the proposed framework, tax paid at the trust level would generally not provide a refundable or non-refundable tax credit to corporate beneficiaries in the same way it may for other beneficiaries.

Treasury’s recent consultation on the proposed trust tax reforms has also considered whether Division 7A should apply to unpaid distributions. These proposals are not yet law, but they could significantly change the way private groups approach trust distributions and UPEs in the future.

Looking ahead

The Bendel decision provides welcome clarity under the current Division 7A rules, particularly for private groups using discretionary trusts and corporate beneficiaries.

At the same time, the proposed trust tax reforms mean businesses should not make long-term decisions based on Bendel alone. Reviewing existing trust distributions, UPEs and Division 7A arrangements now can help identify issues and prepare for potential changes before 1 July 2028.

Please let us know if you would like to discuss how the Bendel decision, Division 7A or the proposed 30% minimum tax on discretionary trusts may affect your group.

Pitt Martin Group is a firm of Chartered Accountants, providing services including taxation, accounting, business consulting, self-managed superannuation funds, auditing and mortgage & finance. We spend hundreds of hours each year on training and researching new tax laws to ensure our clients can maximize legitimate tax benefit. Our contact information are phone +61292213345 or email info@pittmartingroup.com.au. Pitt Martin Group is located in the convenient transportation hub of Sydney’s central business district. Our honours include the 2018 CPA NSW President’s Award for Excellence, the 2020 Australian Small Business Champion Award Finalist, the 2021 Australia’s well-known media ‘Accountants Daily’ the Accounting Firm of the Year Award Finalist and the 2022 Start-up Firm of the Year Award Finalist, and the 2023 Hong Kong-Australia Business Association Business Award Finalist.

Pitt Martin Group qualifications include over fifteen years of professional experience in accounting industry, Registered Australia Tax Agents, membership certification of the Chartered Accountants Australia and New Zealand (CA ANZ), certified External Examiner of the Law Societies of New South Wales, Victoria, and Western Australia Law Trust Accounts, membership certification of the Finance Brokers Association of Australia Limited (FBAA), Registered Agents of the Australian Securities and Investments Commission (ASIC), certified Advisor of accounting software such as XERO, QUICKBOOKS, MYOB, etc.

This content is for reference only and does not constitute advice on any individual or group’s specific situation. Any individual or group should take action only after consulting with professionals. Due to the timeliness of tax laws, we have endeavoured to provide timely and accurate information at the time of publication, but cannot guarantee that the content stated will remain applicable in the future. Please indicate the source when forwarding this content.

By Yvonne Shao @ Pitt Martin Tax
Read more
Sharing Economy Tax Tips for Taxpayers in Australia

Sharing Economy Tax Tips for Taxpayers in Australia

More Australians are turning to the sharing economy to boost their income. Whether you’re driving passengers, renting out a spare room, completing freelance jobs, hiring out equipment or earning money from online content, these flexible income streams can provide welcome financial support.

While earning extra income has many benefits, it’s important to understand that it can also create tax obligations. Many people mistakenly assume that income earned through digital platforms is too small or too casual to report. In reality, most sharing economy income is taxable and generally needs to be included in your annual tax return.

Because this income isn’t always automatically pre-filled when you lodge your return, it’s your responsibility to keep accurate records and ensure everything is reported correctly.

The ATO Is Paying Closer Attention to Sharing Economy Activities

The Australian Taxation Office (ATO) has significantly expanded its ability to monitor sharing economy activities. Through sophisticated data-matching programs, information supplied by many online platforms can now be compared with the income taxpayers report each year.

As reporting requirements continue to expand, failing to disclose sharing economy income is becoming much easier for the ATO to identify. Where inconsistencies are found, the ATO may contact taxpayers for clarification and, if necessary, apply amended assessments, interest charges or penalties.

What Is Considered the Sharing Economy?

The sharing economy covers a wide range of activities where individuals earn money using online marketplaces or digital platforms. Common examples include:

  • Driving for ride-share services such as Uber or DiDi
  • Renting out short-term accommodation through Airbnb, Stayz or similar websites
  • Hiring out assets including cars, caravans, trailers, tools, storage space or parking spots
  • Providing freelance or on-demand services such as deliveries, cleaning, gardening, graphic design or handyman work
  • Creating online content, streaming, selling digital products or receiving payments through creator platforms

Even if your activity is only occasional or earns a relatively small amount, the income may still need to be declared. Whether you’re operating as a business, working independently or simply earning some extra cash, tax obligations can still apply.

Why Record-Keeping Matters

One of the easiest ways to avoid problems at tax time is to maintain accurate financial records throughout the year. While many platforms provide payment summaries, relying solely on those reports may not capture everything you need.

Keeping your own records of income and retaining receipts for work-related expenses will make preparing your tax return much simpler. Depending on the nature of your activity, deductible expenses may include platform commissions, fuel, repairs, insurance, cleaning costs, equipment purchases and other expenses directly connected to earning your income.

Good documentation also provides valuable evidence should the ATO ever request further information.

Understand the Deductions You’re Entitled to Claim

Many people miss legitimate tax deductions simply because they don’t realise what they’re eligible to claim. The expenses you can deduct will depend on how you earn your income and whether those costs are directly related to producing that income.

Every situation is different, so obtaining professional tax advice can help ensure you’re claiming appropriate deductions while remaining compliant with Australian tax law.

Don’t Get Caught by an Unexpected Tax Bill

Unlike employees, people earning income through sharing economy platforms often don’t have tax withheld from their payments. As a result, it’s common to receive a larger-than-expected tax bill when lodging a return.

Planning ahead can help reduce financial stress. Some taxpayers choose to transfer a percentage of each payment into a separate savings account, while others make voluntary tax payments during the year or enter the PAYG instalment system where appropriate.

Other Sharing Economy Tax Responsibilities

Income tax isn’t the only consideration for sharing economy participants. Depending on the type and size of your activities, you may also need to register for GST.

If you provide ride-share services, GST registration is generally required regardless of your annual turnover. Other businesses may need to register once they reach the applicable turnover threshold.

You may also wish to consider making additional superannuation contributions. Besides helping build your retirement savings, these contributions may provide tax planning opportunities depending on your individual circumstances.

Taking a Long-Term Approach

Treating your sharing economy activity like a small business can make managing your finances much easier. Keeping organised records, reviewing your profitability regularly and planning for future tax obligations can improve cash flow and support better financial decision-making as your income grows.

Before lodging your tax return, take the time to review your records and confirm you’ve included all income earned through online platforms. Seeking advice from your accountant can help identify available deductions, ensure your reporting is accurate and minimise the risk of unnecessary ATO enquiries.

The sharing economy continues to create flexible earning opportunities for Australians. By understanding your tax obligations, maintaining good records and planning ahead, you can enjoy the benefits of these additional income streams while remaining confident that you’re meeting your tax responsibilities.

For more information about sharing economy income and your tax obligations, visit the ATO’s guidance or speak with us about your individual circumstances.

Need Help?

By working with us as your professional tax accountant and mortgage broker, you can be confident that your loans are structured to protect your tax position, maximise deductions, and avoid costly mistakes, giving you greater peace of mind and more control over your financial future.

Pitt Martin Group is a firm of Chartered Accountants, providing services including taxation, accounting, business consulting, self-managed superannuation funds, auditing and mortgage & finance. We spend hundreds of hours each year on training and researching new tax laws to ensure our clients can maximize legitimate tax benefit. Our contact information are phone +61292213345 or email info@pittmartingroup.com.au. Pitt Martin Group is located in the convenient transportation hub of Sydney’s central business district. Our honours include the 2018 CPA NSW President’s Award for Excellence, the 2020 Australian Small Business Champion Award Finalist, the 2021 Australia’s well-known media ‘Accountants Daily’ the Accounting Firm of the Year Award Finalist and the 2022 Start-up Firm of the Year Award Finalist, and the 2023 Hong Kong-Australia Business Association Business Award Finalist.

Pitt Martin Group qualifications include over fifteen years of professional experience in accounting industry, Registered Australia Tax Agents, membership certification of the Chartered Accountants Australia and New Zealand (CA ANZ), certified External Examiner of the Law Societies of New South Wales, Victoria, and Western Australia Law Trust Accounts, membership certification of the Finance Brokers Association of Australia Limited (FBAA), Registered Agents of the Australian Securities and Investments Commission (ASIC), certified Advisor of accounting software such as XERO, QUICKBOOKS, MYOB, etc.

This content is for reference only and does not constitute advice on any individual or group’s specific situation. Any individual or group should take action only after consulting with professionals. Due to the timeliness of tax laws, we have endeavoured to provide timely and accurate information at the time of publication, but cannot guarantee that the content stated will remain applicable in the future. Please indicate the source when forwarding this content.

By Alex Cramery @ Pitt Martin Tax

Read more
Ending card surcharges: What you need to know before 1 October 2026

Card Surcharges Ending in Australia in 1 October 2026

The Reserve Bank of Australia (RBA) has announced a significant reform that will reshape the way businesses process payments. From 1 October 2026, all surcharges on credit and debit card payments made through eftpos, Visa, and Mastercard will be prohibited across Australia.

For many businesses, card surcharges have become a common way to recover merchant payment costs. However, these new regulations aim to simplify pricing, improve transparency, and reduce payment costs across the economy.

If your business currently applies card surcharges, now is the time to start preparing.

Why Is the RBA Banning Card Surcharges?

According to the RBA, Australian consumers pay approximately $1.6 billion annually in card surcharges. At the same time, businesses incur even greater costs when accepting electronic payments.

The reform package is designed to:

  • Eliminate unexpected checkout fees for consumers
  • Reduce overall payment processing costs for businesses
  • Improve transparency in the payments industry
  • Encourage competition among payment providers
  • Create a simpler and fairer pricing system

The RBA estimates that merchant payment costs could fall by approximately $910 million per year, with small businesses expected to benefit the most.

What Is Changing From 1 October 2026?

The new payment reforms consist of three key changes.

1. Card Surcharges Will Be Banned

From 1 October 2026, businesses will no longer be permitted to charge additional fees for payments made using:

  • eftpos
  • Visa
  • Mastercard
  • Related payment networks

This applies whether customers pay:

  • In-store
  • Online
  • Through mobile wallets
  • Via integrated payment systems

Customers must see a single final price without additional card payment charges being added at checkout.

2. Lower Interchange Fees

Interchange fees are wholesale charges exchanged between financial institutions when card payments are processed.

Under the new reforms:

  • Existing fee caps will be reduced
  • New limits will apply to foreign-issued cards
  • Payment acceptance costs should decrease for merchants

Lower interchange fees are expected to reduce the overall cost of accepting card payments, helping businesses offset the loss of surcharge revenue.

3. Increased Fee Transparency

Banks, payment providers, and card schemes will be required to provide clearer information regarding:

  • Merchant service fees
  • Processing costs
  • Fee structures
  • Provider margins

Payment providers must also demonstrate how wholesale fee reductions are being passed on to businesses.

This increased transparency should make it easier for business owners to compare providers, negotiate better rates, and make informed decisions about their payment systems.

The reforms will be supported by oversight from the Australian Competition and Consumer Commission (ACCC) and guidance from the Australian Small Business and Family Enterprise Ombudsman.

How Businesses Should Prepare for the Card Surcharge Ban

Although the changes do not take effect until October 2026, businesses should begin reviewing their payment arrangements well in advance.

Review Your Merchant Fees

Start by examining your merchant statements and identifying:

  • Current card acceptance costs
  • Monthly processing fees
  • Revenue generated from surcharges
  • The overall impact on business margins

If surcharges currently help offset payment processing costs, you may need to review your pricing strategy to maintain profitability.

Speak With Your Payment Provider

The upcoming reforms create an opportunity to revisit your arrangements with your payment provider. As interchange fees are expected to decrease and fee transparency increases, businesses may be able to negotiate lower merchant service fees, more competitive pricing plans, or upgraded payment technology. Small businesses, which often pay higher effective processing rates, may stand to benefit the most from these discussions.

Update Your Pricing and POS Systems

Before the implementation date, businesses will need to remove:

  • Card surcharge notices
  • Checkout surcharge settings
  • Automatic percentage-based fees
  • Separate payment processing charges

All displayed prices must become fully inclusive.

Review both physical and online sales channels to ensure compliance with the new requirements.

Factor the Changes Into Cash Flow Planning

While lower merchant costs may not be immediate, many businesses are expected to experience savings during the 2026–27 financial year.

Industries that process large volumes of small transactions may see the greatest impact, including:

  • Cafés
  • Restaurants
  • Retail stores
  • Trade businesses
  • Service-based businesses

Now is a good time to update budgets and financial forecasts to account for the expected changes.

Monitor Customer Payment Behaviour

The removal of surcharges may encourage more customers to choose card payments rather than cash. This could improve convenience, speed up transactions, and reduce the need for cash handling. However, businesses should continue monitoring their payment costs as customer behavior changes to ensure any increase in card usage does not offset the savings generated by lower merchant fees.

The Broader Impact on Australian Businesses

Ultimately, this reform creates a more level playing field across the Australian economy. 

For businesses that never charged a surcharge will immediately benefit from lower underlying merchant fees, boosting your profitability. 

For businesses that did charge a surcharge will enjoy far simpler daily operations, less administrative friction, and zero compliance risks. 

Over time, this regulatory shakeup is expected to drive intense competition among payment providers, paving the way for superior financial products and even lower fees across the market. While banks may adjust secondary features like credit card rewards programs to offset their losses, the combined effort of the RBA and ACCC ensures savings are distributed fairly to businesses and consumers alike.

Final Thoughts

The end of card surcharges represents one of the most significant payment reforms in Australia in recent years.

For consumers, it means simpler pricing and fewer surprises at checkout. For businesses, it presents an opportunity to reduce complexity, improve operational efficiency, and potentially lower payment costs.

The key is preparation. Reviewing your payment arrangements now can help ensure a smooth transition before the 1 October 2026 deadline.

If you are unsure how these changes may affect your business, professional advice can help you assess merchant fees, evaluate pricing strategies, and identify opportunities to reduce costs before the new rules take effect.

Need Help?

By working with us as your professional tax accountant and mortgage broker, you can be confident that your loans are structured to protect your tax position, maximise deductions, and avoid costly mistakes, giving you greater peace of mind and more control over your financial future.

Pitt Martin Group is a firm of Chartered Accountants, providing services including taxation, accounting, business consulting, self-managed superannuation funds, auditing and mortgage & finance. We spend hundreds of hours each year on training and researching new tax laws to ensure our clients can maximize legitimate tax benefit. Our contact information are phone +61292213345 or email info@pittmartingroup.com.au. Pitt Martin Group is located in the convenient transportation hub of Sydney’s central business district. Our honours include the 2018 CPA NSW President’s Award for Excellence, the 2020 Australian Small Business Champion Award Finalist, the 2021 Australia’s well-known media ‘Accountants Daily’ the Accounting Firm of the Year Award Finalist and the 2022 Start-up Firm of the Year Award Finalist, and the 2023 Hong Kong-Australia Business Association Business Award Finalist.

Pitt Martin Group qualifications include over fifteen years of professional experience in accounting industry, Registered Australia Tax Agents, membership certification of the Chartered Accountants Australia and New Zealand (CA ANZ), certified External Examiner of the Law Societies of New South Wales, Victoria, and Western Australia Law Trust Accounts, membership certification of the Finance Brokers Association of Australia Limited (FBAA), Registered Agents of the Australian Securities and Investments Commission (ASIC), certified Advisor of accounting software such as XERO, QUICKBOOKS, MYOB, etc.

This content is for reference only and does not constitute advice on any individual or group’s specific situation. Any individual or group should take action only after consulting with professionals. Due to the timeliness of tax laws, we have endeavoured to provide timely and accurate information at the time of publication, but cannot guarantee that the content stated will remain applicable in the future. Please indicate the source when forwarding this content.

By Nora Pham @ Pitt Martin Tax

Read more
federal budget 2026-27

Federal Budget Tax Updates For 2026

The 2026 Federal Budget tax updates have introduced changes to several key tax proposals announced by the Federal Government. The Budget was delivered on 12 May 2026 and included major changes to capital gains tax (CGT), discretionary trusts and self-managed superannuation funds (SMSFs).

Since then, the Government has reviewed feedback from businesses, tax professionals and industry groups. As a result, several key proposals have been amended. These Federal Budget 2026 tax updates provide important information for taxpayers, investors, business owners and trustees planning for future changes.

Federal Budget Tax Updates: Capital Gains

One of the biggest Budget announcements was a change to the current 50% CGT discount. Under the proposal, individuals and trusts would use an indexation system instead. A new 30% minimum tax rate would also apply to capital gains that accrue from 1 July 2027, with limited exceptions.

The Government has now announced a new Innovative Business CGT Concession. The concession aims to encourage more investment in Australian start-ups. Eligible investors, founders and employee share scheme participants could still receive the 50% CGT discount. The Government has released a consultation paper on how the concession will operate.

In addition, small businesses will also benefit from another proposed change. From 1 July 2027, the turnover limit for the 50% active asset reduction will increase. It will rise from $2 million to $10 million.

However, the other three small business CGT concessions will not change. These include the 15-year exemption, retirement exemption and small business rollover. The current $2 million turnover test will still apply. Businesses may still qualify. They need to meet the existing $6 million net asset value test.

Federal Budget Tax Updates: Trusts

The original Budget proposed a 30% minimum tax rate for discretionary trusts from 1 July 2028. Under that proposal, many testamentary trusts would have fallen within the new rules.

The Government has now changed its approach. It plans to exempt all testamentary trusts that exist for genuine testamentary purposes.

The exemption will only apply to income earned from assets that come from the deceased estate. For testamentary discretionary trusts created on or after 1 July 2028, only individuals and income tax-exempt entities can be beneficiaries if the trust is to qualify.

Federal Budget Tax Updates: SMSF’s

The Government has also announced changes for self-managed superannuation funds.

The Government also plans to change SMSF borrowing rules. Under the proposal, SMSFs could no longer use Limited Recourse Borrowing Arrangements (LRBAs) to buy residential property.

Existing borrowing arrangements are expected to remain in place under grandfathering provisions. However, new residential property borrowing through LRBAs would no longer be available once the changes begin.

What Should You Do Next?

These tax proposals could affect investment decisions, business structures, estate planning and superannuation strategies. Although the Government has already revised several measures, more changes may occur before Parliament passes the legislation.

If you own a business, invest through a trust or manage an SMSF, now is a good time to review your position. Understanding the proposed rules now can help you plan ahead.

We will continue to monitor the legislation and provide updates as more information becomes available. If you would like to discuss how these proposed reforms could affect you, please contact our team.

Need Help?

By working with us as your professional tax accountant and mortgage broker, you can be confident that your loans are structured to protect your tax position, maximise deductions, and avoid costly mistakes, giving you greater peace of mind and more control over your financial future.

Pitt Martin Group is a firm of Chartered Accountants, providing services including taxation, accounting, business consulting, self-managed superannuation funds, auditing and mortgage & finance. We spend hundreds of hours each year on training and researching new tax laws to ensure our clients can maximize legitimate tax benefit. Our contact information are phone +61292213345 or email info@pittmartingroup.com.au. Pitt Martin Group is located in the convenient transportation hub of Sydney’s central business district. Our honours include the 2018 CPA NSW President’s Award for Excellence, the 2020 Australian Small Business Champion Award Finalist, the 2021 Australia’s well-known media ‘Accountants Daily’ the Accounting Firm of the Year Award Finalist and the 2022 Start-up Firm of the Year Award Finalist, and the 2023 Hong Kong-Australia Business Association Business Award Finalist.

Pitt Martin Group qualifications include over fifteen years of professional experience in accounting industry, Registered Australia Tax Agents, membership certification of the Chartered Accountants Australia and New Zealand (CA ANZ), certified External Examiner of the Law Societies of New South Wales, Victoria, and Western Australia Law Trust Accounts, membership certification of the Finance Brokers Association of Australia Limited (FBAA), Registered Agents of the Australian Securities and Investments Commission (ASIC), certified Advisor of accounting software such as XERO, QUICKBOOKS, MYOB, etc.

This content is for reference only and does not constitute advice on any individual or group’s specific situation. Any individual or group should take action only after consulting with professionals. Due to the timeliness of tax laws, we have endeavoured to provide timely and accurate information at the time of publication, but cannot guarantee that the content stated will remain applicable in the future. Please indicate the source when forwarding this content.

By Alex Cramery @ Pitt Martin Tax

Read more

PSI: ATO Reviews Profit Distribution Risks

The Australian Taxation Office (ATO) is increasing its focus on how taxpayers who earn income from their personal skills, knowledge and expertise manage and distribute that income for tax purposes.

The ATO has recently released Practical Compliance Guideline PCG 2025/5, which outlines its compliance approach to arrangements involving the “alienation” of Personal Services Income (PSI). These arrangements generally involve income earned through an individual’s personal efforts being received by a company, trust or another entity instead of being directly recognised as the individual’s income.

Operating through a company or trust is common and can provide legitimate commercial advantages, including asset protection, business flexibility and succession planning. However, where income is mainly generated from one individual’s personal services, business owners should carefully consider whether their current arrangements remain appropriate under the ATO’s updated guidance.

Why Is the ATO Focusing on PSI Arrangements?

Many professionals and business owners use companies or trusts for valid commercial reasons. However, the ATO is concerned about arrangements where income generated from an individual’s skills, reputation or labour is redirected to other entities primarily to achieve a more favourable tax outcome.

The PSI rules aim to ensure that income generated mainly from an individual’s personal efforts is appropriately taxed. Although some businesses may qualify as a Personal Services Business (PSB) and fall outside certain PSI attribution rules, this does not mean the arrangement is automatically protected from ATO review.

The ATO has also highlighted that Part IVA general anti-avoidance provisions may apply where arrangements are implemented mainly to obtain a tax benefit. If Part IVA applies, taxpayers may face additional tax liabilities, penalties and interest charges.

What Arrangements Are Considered Lower Risk?

Under PCG 2025/5, the ATO considers whether the individual who performs the work receives an appropriate share of the financial benefits generated from those services.

An arrangement is generally more likely to be considered lower risk where:

  • The individual receives most of the economic benefit through salary, wages, bonuses, director fees or appropriate trust distributions.
  • Profits retained in a company are supported by genuine short-term commercial reasons.
  • Payments made to family members or related parties reflect reasonable amounts for actual services provided.

For example, retaining company profits to fund equipment purchases, business expansion or other short-term commercial needs may be acceptable where there is clear evidence supporting the purpose and the company follows through with those plans.

What May Attract ATO Attention?

The ATO has identified several behaviours that may increase compliance risk, including:

  • Splitting income with family members or related parties who have made little or no contribution to earning that income.
  • Retaining significant company profits without a genuine commercial purpose.
  • Allocating profits from personal services to entities or beneficiaries mainly because they have lower tax rates or available tax losses.

The key consideration is whether the person receiving the benefit has a genuine connection to the income generated.

Where there is a significant mismatch between the individual performing the work and the person ultimately taxed on the profits, the arrangement is more likely to attract ATO scrutiny.

Time to Review Existing Arrangements

The ATO has provided a transition period for taxpayers who genuinely review and adjust their arrangements.

Businesses that take genuine steps to move from higher-risk arrangements to lower-risk arrangements by 30 June 2027 are unlikely to face Part IVA compliance action in relation to those arrangements if reviewed by the ATO.

This transition period is not an automatic exemption or amnesty. Instead, it provides an opportunity for business owners to proactively assess their structures and make changes where necessary.

What Should Business Owners Do?

Business owners who operate through companies or trusts and derive income mainly from their own personal skills or efforts should review their current arrangements.

Consider the following questions:

  • Are retained profits supported by documented short-term commercial reasons?
  • Are payments to family members or related parties commercially reasonable and supported by genuine work performed?
  • Does the current structure appropriately reflect the contribution made by the individual generating the income?
  • Would the arrangement withstand ATO review?

With increased ATO attention on PSI arrangements, reviewing existing structures now can help identify potential issues early and reduce future compliance risks.

Pitt Martin Group is a firm of Chartered Accountants, providing services including taxation, accounting, business consulting, self-managed superannuation funds, auditing and mortgage & finance. We spend hundreds of hours each year on training and researching new tax laws to ensure our clients can maximize legitimate tax benefit. Our contact information are phone +61292213345 or email info@pittmartingroup.com.au. Pitt Martin Group is located in the convenient transportation hub of Sydney’s central business district. Our honours include the 2018 CPA NSW President’s Award for Excellence, the 2020 Australian Small Business Champion Award Finalist, the 2021 Australia’s well-known media ‘Accountants Daily’ the Accounting Firm of the Year Award Finalist and the 2022 Start-up Firm of the Year Award Finalist, and the 2023 Hong Kong-Australia Business Association Business Award Finalist.

Pitt Martin Group qualifications include over fifteen years of professional experience in accounting industry, Registered Australia Tax Agents, membership certification of the Chartered Accountants Australia and New Zealand (CA ANZ), certified External Examiner of the Law Societies of New South Wales, Victoria, and Western Australia Law Trust Accounts, membership certification of the Finance Brokers Association of Australia Limited (FBAA), Registered Agents of the Australian Securities and Investments Commission (ASIC), certified Advisor of accounting software such as XERO, QUICKBOOKS, MYOB, etc.

This content is for reference only and does not constitute advice on any individual or group’s specific situation. Any individual or group should take action only after consulting with professionals. Due to the timeliness of tax laws, we have endeavoured to provide timely and accurate information at the time of publication, but cannot guarantee that the content stated will remain applicable in the future. Please indicate the source when forwarding this content.

By Yvonne Shao @ Pitt Martin Tax

Read more
SMSF 2026–27 Checklist

SMSF 2026–27 Checklist: Key Trustee Actions

With the 2026–27 financial year now underway, this SMSF 2026–27 checklist highlights the key actions trustees should take to keep their funds compliant and well positioned. Completing the items in this SMSF 2026–27 checklist early can help reduce year-end pressure, minimize compliance risks and identify valuable planning opportunities. The checklist below summarizes the major legislative changes, reporting obligations and practical considerations trustees should review during the new financial year.

1. Review Transfer Balance Cap and Pension Planning

General transfer balance cap increases: From 1 July 2026, the general transfer balance cap (TBC) rises from $2.0 million to $2.1 million. Trustees should determine whether members are entitled to additional personal TBC indexation, particularly where retirement pensions commenced before previous indexation dates.

Although the Australian Taxation Office (ATO) calculates each member’s personal transfer balance cap, its assessment depends on transfer balance account (TBA) events that have already been reported. Pension commencements, commutations and other reportable transactions completed before 30 June 2026 should therefore be lodged promptly to ensure any entitlement to indexation is calculated accurately.

Review legacy pensions: The temporary five-year measure allowing certain legacy pensions to be exited remains available between 7 December 2024 and 6 December 2029. Trustees responsible for lifetime, life expectancy or market-linked pensions should first confirm that the trust deed authorises the proposed strategy. Any decision should also consider the potential impact of Division 296 together with the relevant commutation requirements before implementation.

2. Updating Contribution Strategies in the SMSF 2026–27 Checklist

Contribution caps have increased: From the 2026–27 financial year, the concessional contribution cap becomes $32,500 while the standard non-concessional contribution cap increases to $130,000. Eligibility to make non-concessional contributions remains subject to the member’s total superannuation balance (TSB) at 30 June 2026 being below $2.1 million. Trustees should review planned contributions carefully to reduce the likelihood of exceeding applicable caps.

Check bring-forward eligibility: Before applying the bring-forward provisions during 2026–27, trustees should confirm each member’s TSB at 30 June 2026 because both eligibility thresholds and available bring-forward periods have changed.

The increase in the standard non-concessional cap also raises the maximum bring-forward amount from $360,000 to $390,000. However, members who activated the bring-forward provisions during either the 2024–25 or 2025–26 financial years do not automatically gain access to this higher contribution limit.

3. Monitor Pension Requirements and ECPI Risks

Meet annual pension obligations: Trustees should verify that each pension satisfies the minimum annual payment requirements based on the member’s age. Failure to pay the required minimum amount before year-end may affect pension compliance and jeopardise the fund’s entitlement to exempt current pension income.

Members receiving a transition to retirement income stream should also ensure total annual withdrawals remain within both the minimum and 10% maximum payment limits. Where a member turns 65 during 2026–27, the income stream automatically enters retirement phase, potentially affecting their transfer balance cap position. Professional advice before that milestone may help avoid unintended outcomes.

Follow correct pension procedures: Pension commencements and commutations should always be completed using the required administrative processes. Errors may trigger additional transfer balance account events or unexpected tax consequences. Trustees should also ensure all reportable TBA events are lodged with the ATO within the prescribed reporting deadlines.

4. Related-Party Loan Reviews in the SMSF 2026–27 Checklist

Confirm related-party loan compliance: Trustees with related-party borrowing arrangements should review the requirements outlined in ATO Practical Compliance Guideline PCG 2016/5. This guideline sets out the conditions that generally need to be satisfied for a loan to fall within the ATO’s safe harbour provisions, including benchmark interest rates and other commercial terms.

The applicable interest rate should be reviewed each year using the benchmark released during May immediately before the start of the new financial year. For the 2025–26 financial year, the safe harbour rates were 8.95% for property loans and 10.95% for loans relating to listed securities.

Following recent increases in the Reserve Bank of Australia’s cash rate, the benchmark interest rates have increased to 9.35% for property-backed loans and 11.35% for listed securities. Trustees relying on the safe harbour provisions should recalculate minimum repayments to ensure loan arrangements remain compliant throughout the 2026–27 financial year.

5. Review Payroll and Super Contribution Processes

Ensure New Payments Platform readiness: From 1 July 2026, employers and superannuation funds must be capable of receiving contributions through the New Payments Platform (NPP). Trustees should verify that the fund’s nominated bank account supports Osko, PayID and other approved NPP payment methods so employer contributions can be processed without disruption.

Prepare for Member Verification Requests: Employers will begin using Member Verification Requests (MVRs) to confirm whether an SMSF can accept employer contributions before payments are made. Trustees should ensure these requests can be monitored and answered within the required timeframe.

Generally, SuperStream messages are received through the administration platform used by the fund’s accountant or administrator. Members should therefore advise their SMSF adviser whenever an employer intends to submit an MVR so the request can be identified and managed promptly.

Review obligations for closely held employees: Where an SMSF receives employer contributions for related employees, trustees should determine whether any available SuperStream exemptions apply and confirm payroll systems comply with the latest reporting obligations. Late lodgements may result in penalties. Trustees should also remember that overdue SMSF Annual Returns may cause the ATO to remove the fund from the SMSF Lookup register, preventing employers from directing compulsory contributions to the fund until its compliance status is restored.

6. Consider Division 296 Transitional Rules

Assess transitional arrangements carefully: The 2026–27 financial year introduces specific transitional provisions for Division 296, with the relevant total superannuation balance measured at 30 June 2027. Trustees should evaluate whether adopting a Division 296 cost base based on market values at 30 June 2026 would be appropriate for the fund’s circumstances.

This election is not required until the 2027 SMSF Annual Return is lodged. However, because it applies to all eligible fund assets and may influence future capital gains, capital losses and subsequent tax calculations, trustees should fully understand its consequences before proceeding. Professional advice is strongly recommended before making the election.

7. Finish Your SMSF 2026–27 Checklist with Good Housekeeping Practices

Review trustee structure and documentation: Funds operating with individual trustees may wish to consider whether moving to a corporate trustee structure would provide governance or administrative benefits. Any structural changes should be discussed with an adviser and reported to the ATO, ASIC and other relevant authorities within the required timeframes.

Maintain thorough records: Trustees should retain comprehensive documentation supporting trustee decisions, market valuations, contribution timing, elections, employer correspondence and other significant transactions. Well-maintained records assist with the annual audit process and provide valuable evidence if the ATO reviews the fund.

Taking action early can help minimise year-end stress and reduce compliance risks. Please contact us if you would like to discuss any of the matters outlined above or how they may affect your SMSF.

Need Help?

By working with us as your professional tax accountant and mortgage broker, you can be confident that your loans are structured to protect your tax position, maximise deductions, and avoid costly mistakes, giving you greater peace of mind and more control over your financial future.

Pitt Martin Group is a firm of Chartered Accountants, providing services including taxation, accounting, business consulting, self-managed superannuation funds, auditing and mortgage & finance. We spend hundreds of hours each year on training and researching new tax laws to ensure our clients can maximize legitimate tax benefit. Our contact information are phone +61292213345 or email info@pittmartingroup.com.au. Pitt Martin Group is located in the convenient transportation hub of Sydney’s central business district. Our honours include the 2018 CPA NSW President’s Award for Excellence, the 2020 Australian Small Business Champion Award Finalist, the 2021 Australia’s well-known media ‘Accountants Daily’ the Accounting Firm of the Year Award Finalist and the 2022 Start-up Firm of the Year Award Finalist, and the 2023 Hong Kong-Australia Business Association Business Award Finalist.

Pitt Martin Group qualifications include over fifteen years of professional experience in accounting industry, Registered Australia Tax Agents, membership certification of the Chartered Accountants Australia and New Zealand (CA ANZ), certified External Examiner of the Law Societies of New South Wales, Victoria, and Western Australia Law Trust Accounts, membership certification of the Finance Brokers Association of Australia Limited (FBAA), Registered Agents of the Australian Securities and Investments Commission (ASIC), certified Advisor of accounting software such as XERO, QUICKBOOKS, MYOB, etc.

This content is for reference only and does not constitute advice on any individual or group’s specific situation. Any individual or group should take action only after consulting with professionals. Due to the timeliness of tax laws, we have endeavoured to provide timely and accurate information at the time of publication, but cannot guarantee that the content stated will remain applicable in the future. Please indicate the source when forwarding this content.

Read more
Payday Super Has Arrived – What Employers Need to Know

Payday Super Is Here: New rules starting 1 July 2026

From 1 July 2026, one of the biggest reforms to Australia’s superannuation system has officially taken effect. Under the new Payday Super rules, employers must ensure that superannuation contributions are received by employees’ super funds within seven business days of each payday.

This marks a significant shift from the previous quarterly payment system. While the reform aims to improve retirement outcomes for employees by ensuring super is paid sooner, it also introduces new payroll, cash flow and compliance obligations for businesses.

Whether you’re a small business owner or a larger employer, understanding the new requirements is essential to avoid penalties and maintain compliance.

What Is Payday Super?

Under the previous rules, employers generally had until 28 days after the end of each quarter to make super contributions. Under the new Payday Super system, the clock starts on each “Qualifying Earnings” (QE) day – which is essentially your payday for salary, wages, commissions, bonuses, and certain contractor payments.

Key Payday Super Requirements

  • Strict 7-Day Window: Contributions must be received and allocated to the employee’s fund within 7 business days of payday (with very limited exceptions).
  • Per-Payday Calculations: Shortfalls are now calculated per QE day rather than quarterly.
  • Clearing House Updates: The ATO’s Small Business Superannuation Clearing House has officially closed. Businesses previously using this service must now transition to a SuperStream-compliant alternative.

Penalties for Non-Compliance

The Australian Taxation Office (ATO) has introduced stronger enforcement measures under Payday Super.

Employers who fail to meet their obligations may face:

  • Superannuation Guarantee Charge (SGC) liabilities
  • Administrative penalties of up to 60% of the super shortfall
  • Additional interest and compliance costs

However, employers who voluntarily disclose mistakes early and take prompt corrective action may be eligible for reduced penalties.

During the first year of implementation, the ATO’s compliance approach under PCG 2026/1 focuses on businesses that make genuine efforts to comply. Employers who actively address issues are generally considered lower risk, although employee complaints will still be investigated.

The June – July 2026 Transition: A Common Compliance Trap

Many employers may overlook an important transitional issue when moving from the quarterly system to Payday Super.

If your business paid employees during the June 2026 quarter, the Super Guarantee deadline for that quarter remains 28 July 2026. However, any super contributions made after 1 July 2026 will first be allocated to outstanding June quarter obligations before being applied to Payday Super requirements for July payroll.

Without careful planning, businesses could unintentionally create Superannuation Guarantee Charge (SGC) liabilities despite making payments on time.

The appropriate strategy depends on your payroll schedule and the timing of July pay runs, making it worthwhile to review your payment timetable carefully.

Three Practical Steps to Prepare for Payday Super

1. Review Your Payroll Systems

Confirm that your payroll software, clearing house and internal processes are fully compatible with the new Payday Super requirements.

Check that:

  • Qualifying Earnings are correctly identified
  • Super calculations are accurate
  • SuperStream integration is functioning correctly
  • Payment workflows are automated where possible

2. Assess Cash Flow Impacts

Moving from quarterly to more frequent super payments will affect business cash flow.

Consider reviewing:

  • Payroll funding processes
  • Approval workflows
  • Bonus and commission payment procedures
  • Out-of-cycle payroll processes

Planning ahead can help minimise cash flow pressure while ensuring compliance.

3. Strengthen Internal Controls

Payroll and finance teams should clearly understand the new obligations.

Regular reviews of payroll reports, contribution records and payment confirmations can help identify issues early before they become costly compliance problems

Why Businesses Should Act Now

Payday Super isn’t simply a new payment deadline. It changes how payroll, superannuation, and compliance interact.

Even small process gaps between payroll systems, clearing houses and super funds can quickly become compliance issues if left unchecked.

Businesses that proactively review their payroll processes, improve internal controls and monitor compliance regularly will be better positioned to meet their ongoing obligations while reducing administrative risk.

Need Help?

By working with us as your professional tax accountant and mortgage broker, you can be confident that your loans are structured to protect your tax position, maximise deductions, and avoid costly mistakes, giving you greater peace of mind and more control over your financial future.

Pitt Martin Group is a firm of Chartered Accountants, providing services including taxation, accounting, business consulting, self-managed superannuation funds, auditing and mortgage & finance. We spend hundreds of hours each year on training and researching new tax laws to ensure our clients can maximize legitimate tax benefit. Our contact information are phone +61292213345 or email info@pittmartingroup.com.au. Pitt Martin Group is located in the convenient transportation hub of Sydney’s central business district. Our honours include the 2018 CPA NSW President’s Award for Excellence, the 2020 Australian Small Business Champion Award Finalist, the 2021 Australia’s well-known media ‘Accountants Daily’ the Accounting Firm of the Year Award Finalist and the 2022 Start-up Firm of the Year Award Finalist, and the 2023 Hong Kong-Australia Business Association Business Award Finalist.

Pitt Martin Group qualifications include over fifteen years of professional experience in accounting industry, Registered Australia Tax Agents, membership certification of the Chartered Accountants Australia and New Zealand (CA ANZ), certified External Examiner of the Law Societies of New South Wales, Victoria, and Western Australia Law Trust Accounts, membership certification of the Finance Brokers Association of Australia Limited (FBAA), Registered Agents of the Australian Securities and Investments Commission (ASIC), certified Advisor of accounting software such as XERO, QUICKBOOKS, MYOB, etc.

This content is for reference only and does not constitute advice on any individual or group’s specific situation. Any individual or group should take action only after consulting with professionals. Due to the timeliness of tax laws, we have endeavoured to provide timely and accurate information at the time of publication, but cannot guarantee that the content stated will remain applicable in the future. Please indicate the source when forwarding this content.

By Nora Pham @ Pitt Martin Tax

Read more