Skip to main content Skip to search

Archives for English

Payday Super Has Arrived – What Employers Need to Know

Payday Super Is Here: New rules starting 1 July 2026

From 1 July 2026, one of the biggest reforms to Australia’s superannuation system has officially taken effect. Under the new Payday Super rules, employers must ensure that superannuation contributions are received by employees’ super funds within seven business days of each payday.

This marks a significant shift from the previous quarterly payment system. While the reform aims to improve retirement outcomes for employees by ensuring super is paid sooner, it also introduces new payroll, cash flow and compliance obligations for businesses.

Whether you’re a small business owner or a larger employer, understanding the new requirements is essential to avoid penalties and maintain compliance.

What Is Payday Super?

Under the previous rules, employers generally had until 28 days after the end of each quarter to make super contributions. Under the new Payday Super system, the clock starts on each “Qualifying Earnings” (QE) day – which is essentially your payday for salary, wages, commissions, bonuses, and certain contractor payments.

Key Payday Super Requirements

  • Strict 7-Day Window: Contributions must be received and allocated to the employee’s fund within 7 business days of payday (with very limited exceptions).
  • Per-Payday Calculations: Shortfalls are now calculated per QE day rather than quarterly.
  • Clearing House Updates: The ATO’s Small Business Superannuation Clearing House has officially closed. Businesses previously using this service must now transition to a SuperStream-compliant alternative.

Penalties for Non-Compliance

The Australian Taxation Office (ATO) has introduced stronger enforcement measures under Payday Super.

Employers who fail to meet their obligations may face:

  • Superannuation Guarantee Charge (SGC) liabilities
  • Administrative penalties of up to 60% of the super shortfall
  • Additional interest and compliance costs

However, employers who voluntarily disclose mistakes early and take prompt corrective action may be eligible for reduced penalties.

During the first year of implementation, the ATO’s compliance approach under PCG 2026/1 focuses on businesses that make genuine efforts to comply. Employers who actively address issues are generally considered lower risk, although employee complaints will still be investigated.

The June – July 2026 Transition: A Common Compliance Trap

Many employers may overlook an important transitional issue when moving from the quarterly system to Payday Super.

If your business paid employees during the June 2026 quarter, the Super Guarantee deadline for that quarter remains 28 July 2026. However, any super contributions made after 1 July 2026 will first be allocated to outstanding June quarter obligations before being applied to Payday Super requirements for July payroll.

Without careful planning, businesses could unintentionally create Superannuation Guarantee Charge (SGC) liabilities despite making payments on time.

The appropriate strategy depends on your payroll schedule and the timing of July pay runs, making it worthwhile to review your payment timetable carefully.

Three Practical Steps to Prepare for Payday Super

1. Review Your Payroll Systems

Confirm that your payroll software, clearing house and internal processes are fully compatible with the new Payday Super requirements.

Check that:

  • Qualifying Earnings are correctly identified
  • Super calculations are accurate
  • SuperStream integration is functioning correctly
  • Payment workflows are automated where possible

2. Assess Cash Flow Impacts

Moving from quarterly to more frequent super payments will affect business cash flow.

Consider reviewing:

  • Payroll funding processes
  • Approval workflows
  • Bonus and commission payment procedures
  • Out-of-cycle payroll processes

Planning ahead can help minimise cash flow pressure while ensuring compliance.

3. Strengthen Internal Controls

Payroll and finance teams should clearly understand the new obligations.

Regular reviews of payroll reports, contribution records and payment confirmations can help identify issues early before they become costly compliance problems

Why Businesses Should Act Now

Payday Super isn’t simply a new payment deadline. It changes how payroll, superannuation, and compliance interact.

Even small process gaps between payroll systems, clearing houses and super funds can quickly become compliance issues if left unchecked.

Businesses that proactively review their payroll processes, improve internal controls and monitor compliance regularly will be better positioned to meet their ongoing obligations while reducing administrative risk.

Need Help?

By working with us as your professional tax accountant and mortgage broker, you can be confident that your loans are structured to protect your tax position, maximise deductions, and avoid costly mistakes, giving you greater peace of mind and more control over your financial future.

Pitt Martin Group is a firm of Chartered Accountants, providing services including taxation, accounting, business consulting, self-managed superannuation funds, auditing and mortgage & finance. We spend hundreds of hours each year on training and researching new tax laws to ensure our clients can maximize legitimate tax benefit. Our contact information are phone +61292213345 or email info@pittmartingroup.com.au. Pitt Martin Group is located in the convenient transportation hub of Sydney’s central business district. Our honours include the 2018 CPA NSW President’s Award for Excellence, the 2020 Australian Small Business Champion Award Finalist, the 2021 Australia’s well-known media ‘Accountants Daily’ the Accounting Firm of the Year Award Finalist and the 2022 Start-up Firm of the Year Award Finalist, and the 2023 Hong Kong-Australia Business Association Business Award Finalist.

Pitt Martin Group qualifications include over fifteen years of professional experience in accounting industry, Registered Australia Tax Agents, membership certification of the Chartered Accountants Australia and New Zealand (CA ANZ), certified External Examiner of the Law Societies of New South Wales, Victoria, and Western Australia Law Trust Accounts, membership certification of the Finance Brokers Association of Australia Limited (FBAA), Registered Agents of the Australian Securities and Investments Commission (ASIC), certified Advisor of accounting software such as XERO, QUICKBOOKS, MYOB, etc.

This content is for reference only and does not constitute advice on any individual or group’s specific situation. Any individual or group should take action only after consulting with professionals. Due to the timeliness of tax laws, we have endeavoured to provide timely and accurate information at the time of publication, but cannot guarantee that the content stated will remain applicable in the future. Please indicate the source when forwarding this content.

By Nora Pham @ Pitt Martin Tax

Read more

EV FBT Exemption Changes

The Australian Government has announced a staged reduction of the Fringe Benefits Tax (FBT) exemption for electric vehicles (EVs), following the 2026 statutory review of the Electric Car Discount. While EV incentives will continue, the policy is shifting toward a more targeted and fiscally sustainable approach.

Importantly, there are no immediate changes. The current full FBT exemption remains available until 31 March 2027, meaning existing salary packaging and novated lease arrangements continue as normal for now.

Key Overview

The EV FBT exemption has been one of the main drivers behind Australia’s rapid growth in electric vehicle uptake, particularly through novated leasing arrangements that allow employees to access vehicles using pre-tax income.

However, increasing fiscal costs and distributional concerns have led the Government to restructure the concession. The new framework introduces a three-phase transition from a full exemption to a partial discount system, with a stronger focus on lower-cost EVs.

Phase 1: No Change (Now – 31 March 2027)

Current rules remain unchanged.

Eligible EVs below the Luxury Car Tax (LCT) threshold (around $91,000 for fuel-efficient vehicles in 2025–26) continue to receive a full FBT exemption.

For employers and employees, this means:

  • No changes to existing novated lease or salary packaging arrangements
  • Full exemption continues for eligible EVs
  • No immediate compliance impact

This period provides continued certainty for EV planning and acquisitions.

Phase 2: Partial Concessions Introduced (1 April 2027 – 31 March 2029)

From April 2027, the exemption begins to phase down.

  • EVs up to $75,000: continue to receive a full FBT exemption (if eligible)
  • EVs above $75,000 and below the LCT threshold: receive a 25% FBT discount

This shift encourages uptake of more affordable EV models while reducing the overall cost of the incentive.

It also aligns with Australia’s broader emissions strategy, including the New Vehicle Efficiency Standards, which aim to increase supply of lower-emission vehicles in the market.

Phase 3: Long-Term Model (From 1 April 2029)

From 2029 onwards, the system becomes more uniform.

All eligible EVs under the LCT threshold will receive a flat 25% FBT discount, regardless of price.

The import tariff exemption for qualifying EVs will remain in place, ensuring continued structural support for EV adoption even as FBT concessions are reduced.

Existing Leases Will Be Protected

A key feature of the reform is the expected grandfathering of existing arrangements.

Current leases entered into before the transition periods should continue to benefit under the rules in place at the time of signing. While legislation will confirm the final details, businesses can reasonably expect existing novated lease and salary packaging arrangements to remain unaffected.

What This Means for Employers and Employees

The EV FBT exemption has significantly contributed to EV adoption in Australia, especially through salary packaging structures.

According to the statutory review, the policy:

  • Supported around 64,000 additional EV sales
  • Helped reduce transport emissions and fuel costs
  • Increased EV accessibility across different regions

However, it also raised concerns about equity, as higher-income earners were more likely to benefit, while the fiscal cost to Government has continued to rise.

The revised approach aims to maintain EV support while improving long-term sustainability.

Practical Considerations

With the upcoming changes, planning will become increasingly important:

  • Timing matters: entering arrangements before 31 March 2027 may secure full exemption benefits
  • Price sensitivity increases: EVs under $75,000 will remain more tax-effective from 2027
  • Fleet reviews recommended: employers should reassess total cost of ownership, including FBT impacts
  • Used EVs may become more attractive as incentives narrow on new vehicles

Despite policy changes, EV adoption continues to grow strongly, with EV and PHEV sales reaching 22.9% of new vehicles in March 2026, up significantly from 2022 levels.

Final Thoughts

The phased wind-back of the EV FBT exemption reflects a clear policy shift: continued support for electric vehicles, but with tighter targeting and reduced long-term fiscal cost.

For businesses and employees, the focus now moves from “whether to act” to “when and how to structure EV arrangements effectively”.

If you are considering an EV purchase or reviewing salary packaging arrangements, early planning can help ensure optimal tax outcomes under both current and future rules.

Need Help?

By working with us as your professional tax accountant and mortgage broker, you can be confident that your loans are structured to protect your tax position, maximise deductions, and avoid costly mistakes, giving you greater peace of mind and more control over your financial future.

Pitt Martin Group is a firm of Chartered Accountants, providing services including taxation, accounting, business consulting, self-managed superannuation funds, auditing and mortgage & finance. We spend hundreds of hours each year on training and researching new tax laws to ensure our clients can maximize legitimate tax benefit. Our contact information are phone +61292213345 or email info@pittmartingroup.com.au. Pitt Martin Group is located in the convenient transportation hub of Sydney’s central business district. Our honours include the 2018 CPA NSW President’s Award for Excellence, the 2020 Australian Small Business Champion Award Finalist, the 2021 Australia’s well-known media ‘Accountants Daily’ the Accounting Firm of the Year Award Finalist and the 2022 Start-up Firm of the Year Award Finalist, and the 2023 Hong Kong-Australia Business Association Business Award Finalist.

Pitt Martin Group qualifications include over fifteen years of professional experience in accounting industry, Registered Australia Tax Agents, membership certification of the Chartered Accountants Australia and New Zealand (CA ANZ), certified External Examiner of the Law Societies of New South Wales, Victoria, and Western Australia Law Trust Accounts, membership certification of the Finance Brokers Association of Australia Limited (FBAA), Registered Agents of the Australian Securities and Investments Commission (ASIC), certified Advisor of accounting software such as XERO, QUICKBOOKS, MYOB, etc.

This content is for reference only and does not constitute advice on any individual or group’s specific situation. Any individual or group should take action only after consulting with professionals. Due to the timeliness of tax laws, we have endeavoured to provide timely and accurate information at the time of publication, but cannot guarantee that the content stated will remain applicable in the future. Please indicate the source when forwarding this content.

By Yvonne Shao @ Pitt Martin Tax

Read more
SMSF year end review checklist before 30 June

SMSF Year-End Review: Key Matters Before 30 June

As the end of the financial year approaches, SMSF trustees and members should take time to review their affairs before 30 June. Addressing important matters before SMSF year-end review can help minimize compliance risks, maintain access to available tax concessions and ensure planning opportunities are not missed. The checklist below outlines several areas that may deserve attention before the financial year closes.

Contribution Timing in Your SMSF Year-End Review

• Ensure money reaches the fund before SMSF year-end: For contribution limit and deduction purposes, the relevant date is generally when funds are received by the SMSF rather than when a payment instruction is submitted.

Where money is transferred between separate banking institutions, additional time should be allowed for processing and settlement delays.

• Personally deductible contributions: A member who intends to claim a tax deduction for a personal super contribution must provide the required notice to the trustee and receive acknowledgement from the fund within the prescribed timeframe. In most situations, this must occur before the earlier of lodging the member’s income tax return or 30 June of the following financial year.

• Planning to start a pension shortly after year-end? If retirement income payments are expected to commence early in the next financial year, the deduction notice process should generally be completed first. Otherwise, the contribution may no longer qualify for a personal deduction.

Year-End Planning Opportunities for SMSF Members

• Accessing unused concessional limits: Members with a total superannuation balance below $500,000 at the previous 30 June may be eligible to utilise concessional contribution capacity carried forward from earlier years. This can allow larger deductible contributions to be made in the current year.

This strategy may be particularly valuable where an individual expects to realise a significant capital gain during the 2025–26 income year.

• Using the SMSF allocation timing concession: In certain circumstances, a contribution received during June may be held temporarily in an unallocated reserve before being allocated to a member during July. If implemented correctly, the contribution may count towards the following year’s limits rather than the current year’s cap.

Often referred to as a reserving arrangement, this strategy requires appropriate documentation, trustee resolutions and a trust deed that permits its use. When applied correctly, it may provide additional tax planning flexibility.

After-Tax Contributions in an SMSF Year-End Review

• Bring-forward provisions: Eligibility to access the bring-forward rules depends on a member’s total superannuation balance as at the previous SMSF year-end.

For eligible individuals, it may be possible to contribute more than the standard annual after-tax limit by utilising future years’ contribution capacity.

• Contributions for a spouse and government incentives: Contributions made to a spouse’s super account may provide access to a tax offset where eligibility conditions are satisfied. Lower-income earners who make personal after-tax contributions may also qualify for a government co-contribution if the relevant income requirements are met.

Contribution Limit Changes for Your SMSF Review

The following contribution limits currently apply during the 2025–26 financial year:

• Concessional contributions: $30,000.

• Non-concessional contributions: $120,000.

From 1 July 2026, these limits will increase to:

• Concessional contributions: $32,500.

• Non-concessional contributions: $130,000.

Retirement Planning and Transfer Balance Cap Review

• Required minimum pension payments: Where account-based pensions are being paid from the SMSF, trustees should ensure the minimum annual payment has been made to each pension member before SMSF year-end. Failing to satisfy this requirement may create administrative difficulties and affect valuable tax concessions.

• Other retirement income products may also require minimum annual payments. Certain arrangements impose maximum payment limits, and exceeding those limits may produce adverse consequences.

• Retirement transfer threshold planning: The general transfer balance cap will increase from 1 July 2026.

Members considering commencing a retirement pension near the end of the financial year should carefully consider timing. Whether the pension begins before or after 1 July 2026 may affect the amount that can be transferred into the tax-free retirement phase.

• Current general transfer balance cap for 2025–26: $2.0 million. This amount is scheduled to increase to $2.1 million from 1 July 2026.

• Not all members will have access to the full threshold. Depending on previous transfer balance account events, an individual’s personal limit may be lower.

Valuations and Compliance in Your SMSF Year-End Review

• Market value evidence: Trustees should ensure fund assets are supported by evidence demonstrating market value as close as practical to 30 June. Particular attention should be given to property holdings, connected-party assets and investments that are not publicly traded.

• Related-party dealings: Review leasing arrangements, rental agreements and services involving related parties to ensure they remain appropriately documented and reflect commercial terms.

• Pension records and trustee documentation: Pension commencements, commutations and benefit payments should be supported by properly executed documentation together with trustee resolutions and records.

Need Help?

By working with us as your professional tax accountant and mortgage broker, you can be confident that your loans are structured to protect your tax position, maximise deductions, and avoid costly mistakes, giving you greater peace of mind and more control over your financial future.

Pitt Martin Group is a firm of Chartered Accountants, providing services including taxation, accounting, business consulting, self-managed superannuation funds, auditing and mortgage & finance. We spend hundreds of hours each year on training and researching new tax laws to ensure our clients can maximize legitimate tax benefit. Our contact information are phone +61292213345 or email info@pittmartingroup.com.au. Pitt Martin Group is located in the convenient transportation hub of Sydney’s central business district. Our honours include the 2018 CPA NSW President’s Award for Excellence, the 2020 Australian Small Business Champion Award Finalist, the 2021 Australia’s well-known media ‘Accountants Daily’ the Accounting Firm of the Year Award Finalist and the 2022 Start-up Firm of the Year Award Finalist, and the 2023 Hong Kong-Australia Business Association Business Award Finalist.

Pitt Martin Group qualifications include over fifteen years of professional experience in accounting industry, Registered Australia Tax Agents, membership certification of the Chartered Accountants Australia and New Zealand (CA ANZ), certified External Examiner of the Law Societies of New South Wales, Victoria, and Western Australia Law Trust Accounts, membership certification of the Finance Brokers Association of Australia Limited (FBAA), Registered Agents of the Australian Securities and Investments Commission (ASIC), certified Advisor of accounting software such as XERO, QUICKBOOKS, MYOB, etc.

This content is for reference only and does not constitute advice on any individual or group’s specific situation. Any individual or group should take action only after consulting with professionals. Due to the timeliness of tax laws, we have endeavoured to provide timely and accurate information at the time of publication, but cannot guarantee that the content stated will remain applicable in the future. Please indicate the source when forwarding this content.

Read more
federal budget 2026-27

2026 Federal Budget Tax Changes: What You Should Consider Now

The proposed tax changes announced in the 2026 Federal Budget have created plenty of discussion.

Property investors are reviewing their portfolios. Business owners are reassessing their structures. Families using discretionary trusts are asking what happens next.

The proposed reforms focus on three key areas:

  • Negative gearing
  • Capital gains tax (CGT)
  • Discretionary trusts

Importantly, these measures are not law yet. Parliament still needs to consider and pass the legislation.

However, that does not mean you should ignore the proposals. Instead, now is a good time to understand the possible impact and plan ahead.

Why Planning Early Makes Sense

Many people are waiting for certainty before taking action.

However, smart planning does not require certainty.

The proposed negative gearing and CGT changes are due to start from 1 July 2027. Meanwhile, the trust reforms are not expected to begin until 1 July 2028.

As a result, investors and business owners have time to review their position and explore different options.

You do not need to make major changes today. However, understanding your risks and opportunities now can help you make better decisions later.

1. Review Your Existing Property Portfolio

One of the biggest Budget announcements relates to negative gearing.

The Government plans to limit negative gearing for established residential properties purchased after 12 May 2026.

Existing Investors May Have an Advantage

Current property owners could benefit from grandfathering rules.

Under the proposal, investors who owned residential property before Budget night can continue using the existing negative gearing rules.

As a result, eligible rental losses could still offset salary, business income and other taxable income.

For many investors, this may become a valuable long-term benefit.

Why This Matters

Not all investment properties may receive the same tax treatment in the future.

Because of this, now is a good time to review your portfolio.

First, identify which assets may qualify for grandfathering. Next, consider how those assets fit within your long-term investment goals.

A simple review today could uncover opportunities you may have overlooked.

2. Think Carefully About Future Property Purchases

The proposed reforms could change how investors approach new property purchases.

In the past, many investors used negative gearing when buying established residential properties.

However, future buyers may need to focus more on investment fundamentals.

Focus on Quality Investments

Tax benefits are important. However, they should never be the main reason for buying an investment property.

Instead, focus on:

  • Strong locations
  • Rental demand
  • Cash flow potential
  • Long-term growth

These factors often have a greater impact on returns than tax deductions alone.

New Builds Could Attract More Interest

In addition, the Government has indicated that newly built residential properties may continue to receive favourable tax treatment.

Some housing developments and build-to-rent projects may also qualify for concessions.

As a result, investors may begin comparing new builds more closely with established properties.

3. Identify Assets That May Need Valuations

The proposed CGT changes could create new planning opportunities.

They could also create additional record-keeping requirements.

Why Valuations Matter

Under the proposal, gains that build up before 1 July 2027 will receive different tax treatment from gains that arise after that date.

Because of this, many investors may need accurate market values as at 1 July 2027.

This could apply to:

  • Investment properties
  • Commercial real estate
  • Share portfolios
  • Business assets

Start Early

Valuations often take time.

Therefore, it makes sense to start planning well before any deadline arrives.

Good records today can save time, money and stress later.

4. Review Your Capital Gains Tax Strategy

The Government also plans to change the current CGT discount rules.

This is one of the biggest Budget announcements.

For many years, investors have relied on the 50% CGT discount when selling assets.

However, the proposed rules may change the way some investors think about future sales.

Look at Future Exit Plans

Now is a good time to review your long-term plans.

For example:

  • Which assets might you sell in the next five years?
  • How would the current rules affect the outcome?
  • How could the proposed rules change that result?

These questions can help you identify potential risks early.

Keep the Bigger Picture in Mind

Tax matters. However, it should not drive every decision.

Likewise, your investment goals, retirement plans and cash flow needs should remain key considerations.

5. Review Your Trust Structure

The proposed trust changes have attracted significant attention.

If introduced, discretionary trusts would face a minimum tax rate of 30%.

Understand the Potential Impact

Many families use discretionary trusts to distribute income among beneficiaries.

The Government wants to reduce some of the tax benefits associated with these arrangements.

As a result, some families could pay more tax under the proposed system.

Remember the Non-Tax Benefits

Importantly, trusts offer more than tax advantages.

They can also assist with:

  • Asset protection
  • Estate planning
  • Succession planning
  • Family wealth management

Therefore, trusts may still play an important role even if tax outcomes change.

6. Consider Alternative Structures

Some taxpayers may decide to review their current structures.

However, restructuring is not always the right move.

Explore Different Options

Depending on your situation, you may wish to compare:

  • Private companies
  • Fixed trusts
  • Corporate beneficiaries
  • Other business structures

Each option has strengths and weaknesses.

Avoid Rushed Decisions

Finally, avoid making major changes based on proposed legislation alone.

Instead, compare tax outcomes alongside asset protection, business goals and succession planning needs.

7. Stay Informed

The final action may be the most important.

At this stage, the proposals are not law.

Focus on Preparation, Not Panic

Many details could change before the legislation passes Parliament.

Therefore, preparation is more valuable than speculation.

Review your position. Model different scenarios. Understand your options.

Then, when more details become available, you can act with confidence.

Frequently Asked Questions

Will negative gearing be abolished?

No. The proposal restricts how some losses can be used. It does not abolish negative gearing.

Will existing properties be protected?

Under the current proposal, many existing property owners will receive grandfathering protection.

Should I restructure my trust now?

Not necessarily. First, wait for more certainty around the final legislation.

Will trusts still be useful?

Yes. In many cases, trusts will continue to provide asset protection and estate planning benefits.

Seek Advice Before Making Major Decisions

Every taxpayer’s situation is different.

For example, one investor may benefit from grandfathering rules. Another may need to review future purchase plans.

Likewise, some business owners may benefit from a restructure, while others may not.

Professional advice can help you understand the options available and avoid costly mistakes.

What Should You Do Next?

The proposed 2026 Federal Budget tax changes could affect investors, business owners and families for years to come.

However, there is still time to prepare.

Now is the ideal time to review your position, understand the possible impact and plan ahead.

By taking action early, you can make informed decisions and respond with confidence as the legislation develops.

Need Help?

By working with us as your professional tax accountant and mortgage broker, you can be confident that your loans are structured to protect your tax position, maximise deductions, and avoid costly mistakes, giving you greater peace of mind and more control over your financial future.

Pitt Martin Group is a firm of Chartered Accountants, providing services including taxation, accounting, business consulting, self-managed superannuation funds, auditing and mortgage & finance. We spend hundreds of hours each year on training and researching new tax laws to ensure our clients can maximize legitimate tax benefit. Our contact information are phone +61292213345 or email info@pittmartingroup.com.au. Pitt Martin Group is located in the convenient transportation hub of Sydney’s central business district. Our honours include the 2018 CPA NSW President’s Award for Excellence, the 2020 Australian Small Business Champion Award Finalist, the 2021 Australia’s well-known media ‘Accountants Daily’ the Accounting Firm of the Year Award Finalist and the 2022 Start-up Firm of the Year Award Finalist, and the 2023 Hong Kong-Australia Business Association Business Award Finalist.

Pitt Martin Group qualifications include over fifteen years of professional experience in accounting industry, Registered Australia Tax Agents, membership certification of the Chartered Accountants Australia and New Zealand (CA ANZ), certified External Examiner of the Law Societies of New South Wales, Victoria, and Western Australia Law Trust Accounts, membership certification of the Finance Brokers Association of Australia Limited (FBAA), Registered Agents of the Australian Securities and Investments Commission (ASIC), certified Advisor of accounting software such as XERO, QUICKBOOKS, MYOB, etc.

This content is for reference only and does not constitute advice on any individual or group’s specific situation. Any individual or group should take action only after consulting with professionals. Due to the timeliness of tax laws, we have endeavoured to provide timely and accurate information at the time of publication, but cannot guarantee that the content stated will remain applicable in the future. Please indicate the source when forwarding this content.

By Alex Cramery @ Pitt Martin Tax

Read more
EV Home Charging Rate

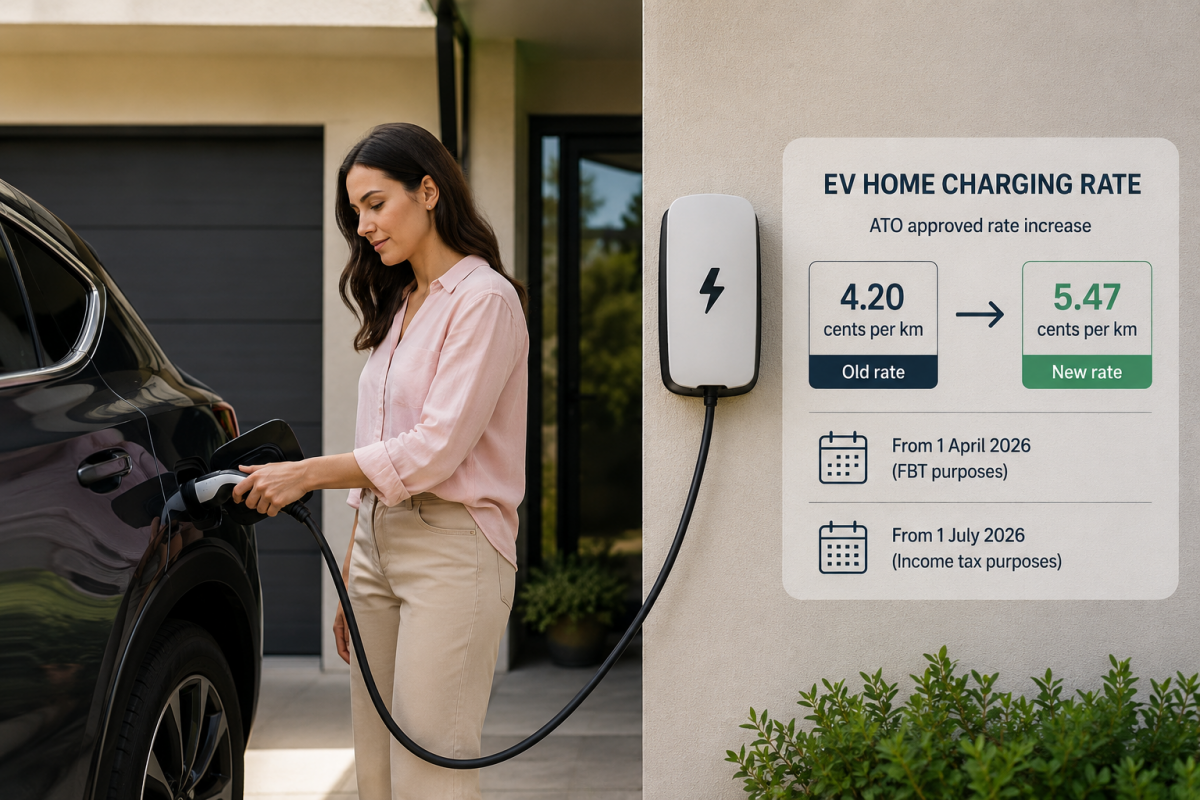
ATO Increases EV Home Charging Rate to 5.47 Cents per Kilometre from 2026

Key Takeaways

  • The ATO’s standard EV home charging rate will increase from 4.20 cents to 5.47 cents per kilometre.
  • The new rate applies from 1 April 2026 for Fringe Benefits Tax (FBT) purposes.
  • The new rate applies from 1 July 2026 for income tax deductions.
  • Employers providing EVs through novated leases, salary packaging arrangements or company vehicles may see changes to their FBT calculations.
  • Individuals claiming work-related electric vehicle expenses using the logbook method may be entitled to larger deductions.
  • Minimal record-keeping is required to use the ATO’s simplified method.

The Australian Taxation Office (ATO) has announced changes to the approved EV home charging rate, which may affect taxpayers and employers using electric vehicles (EVs) or plug-in hybrid electric vehicles (PHEVs) for work-related purposes where charging occurs at home.

For fringe benefits tax (FBT) purposes, the revised rate will apply from 1 April 2026, while income tax claims will adopt the change from 1 July 2026. Under the update, the approved home-charging electricity rate will increase from 4.20 cents per kilometre to 5.47 cents per kilometre.

Where household electricity bills do not separately identify EV charging usage, the ATO allows taxpayers to rely on this simplified cents-per-kilometre calculation method. This removes the need to track electricity consumption in kilowatt hours or install specialized charging measurement equipment. Instead, taxpayers can estimate charging costs by multiplying the approved rate by the distance travelled by the vehicle.

The revised amount reflects higher electricity prices and is intended to provide businesses and individuals with a more commercially realistic charging allowance.

Home Charging Electricity Rate Impact on Employers

Employers supplying EVs or PHEVs through salary packaging arrangements, novated leasing structures, or company-owned vehicles may see changes to their FBT calculations as a result of the increased EV home charging rate. In practice, the update may:

• Increase the taxable value of the benefit when the operating cost method is adopted.

• Result in larger employee recipient contributions, potentially reducing the employer’s FBT liability.

• Affect the calculation of reportable fringe benefits amounts.

Claiming Deductions for Electric Vehicle Charging Costs

Taxpayers using the logbook method to claim work-related vehicle expenses may apply the new rate to the business-use portion of kilometres travelled from the commencement of the 2026–27 income year. Earlier periods, including years dating back to 2022, must continue using the previous 4.20-cent rate.

Records Required for EV Charging Expense Claims

Only limited records are required to support these claims. Taxpayers should retain:

• Odometer readings taken at the beginning and end of the relevant income or FBT year where possible.

• A compliant logbook identifying business and private travel if using the operating cost or logbook method.

• At least one electricity bill demonstrating that home electricity expenses are incurred.

• For PHEVs, petrol receipts should also be retained. Fuel expenses must be calculated separately using the manufacturer’s hybrid fuel consumption figures, while the ATO home-charging rate applies solely to electric kilometres travelled.

Tip: Many newer EV models now report the proportion of charging completed at home compared with public charging stations. Using this information may improve calculation accuracy and potentially increase deductions.

Example of the Revised Home Charging Rate

If an employee owns an EV and travels 25,000 kilometres for employment purposes during the 2026–27 income year, the home-charging expense calculation would be:

Home-charging cost = 25,000 × 5.47c = $1,367.50 (previously $1,050).

Compared with the earlier rate, the additional $317.50 may assist in lowering the employee’s taxable income for the relevant year.

Preparing for the New Electric Vehicle Charging Rules

• The existing lower rate should continue to be used for the FBT year ending 31 March 2026 and for income tax deductions relating to the year ending 30 June 2026.

• The revised rate should only be applied for the current FBT year and for income years commencing from 1 July 2026.

The adoption of electric vehicles continues to grow, and the updated ATO rate is expected to deliver improved tax outcomes for many taxpayers while maintaining a straightforward compliance process. Whether you operate a vehicle fleet, offer salary packaging arrangements, or claim motor vehicle expenses personally, now is an ideal time to assess the potential benefits. Our team can help you evaluate the impact and ensure you maximise all available tax concessions and deductions.

Need Help?

By working with us as your professional tax accountant and mortgage broker, you can be confident that your loans are structured to protect your tax position, maximise deductions, and avoid costly mistakes, giving you greater peace of mind and more control over your financial future.

Pitt Martin Group is a firm of Chartered Accountants, providing services including taxation, accounting, business consulting, self-managed superannuation funds, auditing and mortgage & finance. We spend hundreds of hours each year on training and researching new tax laws to ensure our clients can maximize legitimate tax benefit. Our contact information are phone +61292213345 or email info@pittmartingroup.com.au. Pitt Martin Group is located in the convenient transportation hub of Sydney’s central business district. Our honours include the 2018 CPA NSW President’s Award for Excellence, the 2020 Australian Small Business Champion Award Finalist, the 2021 Australia’s well-known media ‘Accountants Daily’ the Accounting Firm of the Year Award Finalist and the 2022 Start-up Firm of the Year Award Finalist, and the 2023 Hong Kong-Australia Business Association Business Award Finalist.

Pitt Martin Group qualifications include over fifteen years of professional experience in accounting industry, membership certification of the Chartered Accountants Australia and New Zealand (CA ANZ), membership certification of the Australian Society of Certified Practising Accountants (CPA), Registered Australia Tax Agents, certified External Examiner of the Law Societies of New South Wales, Victoria, and Western Australia Law Trust Accounts, membership certification of the Finance Brokers Association of Australia Limited (FBAA), Registered Agents of the Australian Securities and Investments Commission (ASIC), certified Advisor of accounting software such as XERO, QUICKBOOKS, MYOB, etc.

This content is for reference only and does not constitute advice on any individual or group’s specific situation. Any individual or group should take action only after consulting with professionals. Due to the timeliness of tax laws, we have endeavoured to provide timely and accurate information at the time of publication, but cannot guarantee that the content stated will remain applicable in the future. Please indicate the source when forwarding this content.

Read more
Superannuation contribution caps to increase from 1 July 2026

Superannuation contribution caps are set to rise effective from 1 July 2026

Australia’s superannuation contribution caps will increase from 1 July 2026 following the release of the December 2025 quarter Average Weekly Ordinary Time Earnings (AWOTE). The annual concessional contribution (CC) cap will rise from $30,000 to $32,500, while the non-concessional contribution (NCC) cap will increase from $120,000 to $130,000. These changes may provide additional opportunities to increase retirement savings and improve tax efficiency.

Concessional Contributions

Concessional contributions are pre-tax contributions and may include Superannuation Guarantee (SG) payments, salary sacrifice arrangements, and personal deductible contributions. For individuals whose SG contributions remain below the annual cap, additional concessional contributions may help reduce taxable income and lower overall tax liabilities.

Some taxpayers may also qualify to use unused concessional contribution caps from the previous five financial years under the carry-forward contribution rules, provided their total superannuation balance (TSB) was below $500,000 at the previous 30 June.

Non-Concessional Contributions

Non-concessional contributions are made using after-tax income. Although they generally do not provide an immediate tax deduction, they can still offer long-term tax advantages because superannuation earnings are typically taxed at only 15% during the accumulation phase. In retirement, earnings and pension withdrawals may become tax-free, subject to the transfer balance cap, which will increase to $2,100,000 from 1 July 2026.

Eligible individuals may also access the bring-forward rule, allowing up to three years of NCC caps to be contributed at once. From 1 July 2026, this could allow contributions of up to $390,000 in a single financial year. However, eligibility depends on factors such as total superannuation balance and prior NCC contributions.

There may also be contribution opportunities available in the current financial year for individuals whose TSB was below $2,000,000 on 30 June 2025.

Recommended Action

With superannuation rules becoming increasingly complex, individuals and business owners should regularly review their contribution strategies, contribution caps, and total superannuation balances to avoid excess contribution penalties and maximise available tax benefits.

Need Help?

By working with us as your professional tax accountant and mortgage broker, you can be confident that your loans are structured to protect your tax position, maximise deductions, and avoid costly mistakes, giving you greater peace of mind and more control over your financial future.

Pitt Martin Group is a firm of Chartered Accountants, providing services including taxation, accounting, business consulting, self-managed superannuation funds, auditing and mortgage & finance. We spend hundreds of hours each year on training and researching new tax laws to ensure our clients can maximize legitimate tax benefit. Our contact information are phone +61292213345 or email info@pittmartingroup.com.au. Pitt Martin Group is located in the convenient transportation hub of Sydney’s central business district. Our honours include the 2018 CPA NSW President’s Award for Excellence, the 2020 Australian Small Business Champion Award Finalist, the 2021 Australia’s well-known media ‘Accountants Daily’ the Accounting Firm of the Year Award Finalist and the 2022 Start-up Firm of the Year Award Finalist, and the 2023 Hong Kong-Australia Business Association Business Award Finalist.

Pitt Martin Group qualifications include over fifteen years of professional experience in accounting industry, membership certification of the Chartered Accountants Australia and New Zealand (CA ANZ), membership certification of the Australian Society of Certified Practising Accountants (CPA), Registered Australia Tax Agents, certified External Examiner of the Law Societies of New South Wales, Victoria, and Western Australia Law Trust Accounts, membership certification of the Finance Brokers Association of Australia Limited (FBAA), Registered Agents of the Australian Securities and Investments Commission (ASIC), certified Advisor of accounting software such as XERO, QUICKBOOKS, MYOB, etc.

This content is for reference only and does not constitute advice on any individual or group’s specific situation. Any individual or group should take action only after consulting with professionals. Due to the timeliness of tax laws, we have endeavoured to provide timely and accurate information at the time of publication, but cannot guarantee that the content stated will remain applicable in the future. Please indicate the source when forwarding this content.

Read more

Fuel Disruptions: ATO Support for Affected Businesses

Global fuel supply pressures, driven by ongoing geopolitical tensions in the Middle East, are continuing to affect many Australian businesses. Rising fuel costs, delivery delays, and tighter margins are creating cash flow challenges across a range of industries, particularly those reliant on transport and logistics.

In response, Treasurer Jim Chalmers and the Australian Taxation Office (ATO) have introduced a set of temporary, practical measures designed to ease pressure on impacted businesses. Rather than a broad stimulus package, the support is targeted and administered directly by the ATO on a case-by-case basis.

If your business has been affected by fuel disruptions—whether through higher operating costs, reduced revenue, or supply chain delays—there may now be more flexibility available to help you manage your tax obligations.

What support is available?

1. Flexible payment arrangements

Businesses experiencing cash flow pressure can request payment plans with the ATO to spread existing tax debts over time. This helps preserve working capital for essential expenses such as wages, inventory, and operational costs.

2. Interest and penalty relief

Where tax payment delays are linked to fuel-related disruptions, the ATO may consider remitting general interest charges (GIC) and late payment penalties. This can significantly reduce the overall burden of temporary financial stress.

3. PAYG instalment adjustments

If your revenue has been impacted by increased fuel costs or slower trading conditions, you may be able to reduce your PAYG instalments. This ensures your tax obligations better reflect your current business performance, improving short-term cash flow.

4. Reduced compliance activity

In certain affected sectors, the ATO may temporarily scale back audit and review activity. This allows businesses to focus on operations, staffing, and customer commitments rather than administrative demands.

5. Temporary pause on debt recovery

In appropriate cases, the ATO may pause debt recovery action while a business works through short-term financial pressure. This provides additional breathing room for businesses facing external cost shocks.

How to access support

Businesses do not need to navigate this process alone. In many cases, a brief explanation of how fuel disruptions have impacted operations—supported by basic financial information—is enough to begin a discussion with the ATO.

Professional assistance can also help ensure the right type of relief is requested and properly documented. Applications for the ATO fuel disruption response and related payment arrangements are currently available until 30 June 2026.

Why this matters

Fuel volatility continues to affect key sectors such as transport, logistics, agriculture, manufacturing, and retail. These pressures can quickly flow through to reduced margins and tighter cash flow.

The intention of this support package is to give businesses short-term breathing space, allowing them to maintain staffing levels, manage supplier payments, adjust pricing where necessary, and continue operating without additional tax-related pressure.

While temporary, these measures can play an important role in stabilising cash flow during uncertain periods.

Take action early

If your business is experiencing pressure from rising fuel costs or supply chain disruption, it is worth reviewing your position early. Identifying available support options sooner rather than later can help avoid unnecessary penalties and improve financial flexibility.

Pitt Martin Group qualifications include over fifteen years of professional experience in accounting industry, membership certification of the Chartered Accountants Australia and New Zealand (CA ANZ), membership certification of the Australian Society of Certified Practising Accountants (CPA), Registered Australia Tax Agents, certified External Examiner of the Law Societies of New South Wales, Victoria, and Western Australia Law Trust Accounts, membership certification of the Finance Brokers Association of Australia Limited (FBAA), Registered Agents of the Australian Securities and Investments Commission (ASIC), certified Advisor of accounting software such as XERO, QUICKBOOKS, MYOB, etc.

This content is for reference only and does not constitute advice on any individual or group’s specific situation. Any individual or group should take action only after consulting with professionals. Due to the timeliness of tax laws, we have endeavoured to provide timely and accurate information at the time of publication, but cannot guarantee that the content stated will remain applicable in the future. Please indicate the source when forwarding this content.

By Yvonne Shao @ Pitt Martin Tax

Read more
The ATO’s Increased Focus on Work Vehicle FBT: Avoid Costly Missteps

The ATO’s Increased Focus on Work Vehicle FBT: Avoid Costly Missteps

The ATO is closely checking employers who allow personal use of work vehicles. Their advanced data systems can quickly detect mistakes, which may result in audits, penalties, added interest, and reputational risk. For more details, refer to the latest ATO FBT audit warning: Misreporting FBT on personal use of work vehicles | Australian Taxation Office

If your business provides vehicles to employees—whether for operational needs or as an added benefit—it is important to review your Fringe Benefits Tax (FBT) obligations carefully. Proper reporting and record-keeping can help you avoid unnecessary risks and costs.

Misconceptions Around Dual-Cab Utes

One common mistake involves dual-cab utes. Many employers believe these vehicles are automatically exempt from FBT, but this is not always correct. The tax treatment depends on both the design of the vehicle and how it is actually used during the FBT year. For example, even if a vehicle can carry more than one tonne or is not mainly designed for passengers, FBT may still apply if there is private use.

The ATO has already identified many cases where businesses incorrectly claimed full exemptions for such vehicles. As a result, those employers had to pay additional tax along with interest. To avoid this situation, it is essential to have proper evidence supporting any exemption claimed. Although formal logbooks may not always be required, having records similar to a logbook can make it much easier to justify your position during an ATO review or audit.

Proper Allocation of Private and Business Use

If a full FBT exemption does not apply, tax is usually based on the private use of the vehicle. You need to work out how much of the costs—such as fuel, repairs, and depreciation—relate to personal trips. Ignoring this can cause issues during an audit. Keeping clear records and correctly splitting costs may reduce FBT. Any FBT payable is the employer’s responsibility.

Obligation to Lodge FBT Returns

Another area often overlooked is the requirement to lodge FBT returns. Even if you believe the amount involved is small or insignificant, you may still be required to submit a return. The ATO uses data analytics to identify businesses that fail to lodge, and penalties for non-compliance can be severe—up to 200% of the tax payable, plus interest charges.

To stay compliant, businesses should take note of key deadlines. FBT returns are generally due on 21 May each year. Filing on time helps avoid penalties and allows for better cash flow planning.

Importance of Maintaining Accurate Records

Maintaining proper records, including logbooks, is one of the most effective ways to manage FBT obligations. A valid logbook should record odometer readings, trip details, and the purpose of each journey over a continuous 12-week period. This record can usually be used for up to five years, provided usage patterns do not significantly change. Even in situations where a logbook is not strictly required, keeping detailed records can prevent higher tax liabilities.

Using digital tools can also improve efficiency. Many logbook apps are available to simplify tracking, reduce errors, and save time. In addition to supporting FBT calculations, good records may also help support other tax deductions.

Commercial Implications of Non-Compliance

FBT compliance is not only about meeting legal requirements. It also has practical business implications. An ATO audit can consume time and resources, distracting you from your core operations. It may also affect how your business is viewed by clients, lenders, and partners.

On the other hand, proper FBT management ensures that you only pay the correct amount of tax. It helps protect your cash flow and may even identify opportunities to improve tax efficiency.

Recommended Actions

To reduce risk, businesses should regularly review their vehicle policies, update records, and ensure that all reporting is accurate. Taking a proactive approach can make compliance easier and prevent costly mistakes.

Pitt Martin Group is a CPA accounting firm, providing services including taxation, accounting, business consulting, self-managed superannuation funds, auditing and mortgage & finance. We spend hundreds of hours each year on training and researching new tax laws to ensure our clients can maximize legitimate tax benefit. Our contact information are phone +61292213345 or email info@pittmartingroup.com.au. Pitt Martin Group is located in the convenient transportation hub of Sydney’s central business district. Our honours include the 2018 CPA NSW President’s Award for Excellence, the 2020 Australian Small Business Champion Award Finalist, the 2021 Australia’s well-known media ‘Accountants Daily’ the Accounting Firm of the Year Award Finalist and the 2022 Start-up Firm of the Year Award Finalist, and the 2023 Hong Kong-Australia Business Association Business Award Finalist.

Pitt Martin Group qualifications include over fifteen years of professional experience in accounting industry, membership certification of the Australian Society of Certified Practising Accountants (CPA), Australian Taxation Registered Agents, certified External Examiner of the Law Societies of New South Wales, Victoria, and Western Australia Law Trust Accounts, membership certification of the Finance Brokers Association of Australia Limited (FBAA), Registered Agents of the Australian Securities and Investments Commission (ASIC), certified Advisor of accounting software such as XERO, QUICKBOOKS, MYOB, etc.

This content is for reference only and does not constitute advice on any individual or group’s specific situation. Any individual or group should take action only after consulting with professionals. Due to the timeliness of tax laws, we have endeavoured to provide timely and accurate information at the time of publication, but cannot guarantee that the content stated will remain applicable in the future. Please indicate the source when forwarding this content.

By Angela Abejo @ Pitt Martin Tax

Read more
Understanding the New Division 296 Tax on High Superannuation Balances

Understanding the New Division 296 Tax on High Superannuation Balances

The Australian Government’s “Better Targeted Superannuation Concessions” reform, commonly referred to as Division 296, has now been enacted and will commence from 1 July 2026. This measure introduces additional tax considerations for individuals with substantial superannuation balances. For affected taxpayers, it is essential to understand how the rules operate, the policy rationale behind them, and the planning implications moving forward.

Policy Intent Behind Division 296

The primary objective of Division 296 is to improve the equity and long-term sustainability of superannuation tax concessions. Rather than applying broad changes across the entire system, the legislation specifically targets individuals with significant super balances. In doing so, it seeks to ensure that higher-balance members pay an increased level of tax on earnings attributable to those balances.

Applicability: Thresholds and Tax Outcomes

From the 2026–27 income year onward, Division 296 applies where an individual’s total superannuation balance exceeds prescribed thresholds:

  • $3 million (large balance threshold)
  • $10 million (very large balance threshold)

These thresholds will be indexed over time. The effect of the new regime is an increase in the effective tax rate applied to earnings associated with balances above these limits:

  • Balances up to $3 million remain subject to the standard 15% tax rate within the fund
  • Earnings linked to balances between $3 million and $10 million will attract an additional 15% tax, bringing the effective rate to 30%
  • For balances exceeding $10 million, a further 25% tax applies, resulting in a combined effective rate of 40%

Certain individuals are excluded from the operation of Division 296 despite exceeding the thresholds. These include minors receiving death benefit pensions and individuals who have contributed structured settlement amounts arising from personal injury compensation.

In the event of death, an individual’s total superannuation balance ceases to exist. However, Division 296 may still apply for the income year in which death occurs (other than in the first year of implementation), provided the individual’s balance exceeded $3 million at the beginning of that year. As superannuation does not generally form part of the estate, this outcome highlights the importance of incorporating these rules into estate planning considerations.

Calculation and Assessment Mechanism

For self-managed superannuation funds (SMSFs), Division 296 earnings are determined based on taxable income, subject to a number of adjustments. These adjustments account for items such as concessional contributions included in assessable income, exempt pension income, non-arm’s length income (already taxed at the highest marginal rate), and income derived through pooled superannuation trusts.

Additional modifications may apply in relation to capital gains where the fund has elected to apply specific small-fund CGT provisions.

Once the adjusted earnings figure is established, it is allocated to individual members using an actuarially determined proportion. The Australian Taxation Office (ATO) then uses this information to calculate and issue the individual’s Division 296 tax liability.

Although the liability is imposed on the individual rather than the superannuation fund, payment flexibility is provided. Taxpayers may either settle the liability personally or elect to have the amount withdrawn from their nominated superannuation interest.

Practical Considerations and Planning Opportunities

Individuals approaching or exceeding the relevant thresholds should seek professional advice to assess the financial impact of Division 296. This may involve tailored projections, consideration of available elections (including capital gains tax options), and planning for cash flow and compliance requirements.

The introduction of this measure also presents an opportunity to reassess whether maintaining excess wealth within the superannuation environment remains optimal. Alternative investment structures may, in some cases, provide greater flexibility or tax efficiency for amounts above the applicable thresholds.

Early and proactive planning will be critical to managing the implications of Division 296 effectively.

Need Help?

By working with us as your professional tax accountant and mortgage broker, you can be confident that your loans are structured to protect your tax position, maximise deductions, and avoid costly mistakes, giving you greater peace of mind and more control over your financial future.

Pitt Martin Group is a firm of Chartered Accountants, providing services including taxation, accounting, business consulting, self-managed superannuation funds, auditing and mortgage & finance. We spend hundreds of hours each year on training and researching new tax laws to ensure our clients can maximize legitimate tax benefit. Our contact information are phone +61292213345 or email info@pittmartingroup.com.au. Pitt Martin Group is located in the convenient transportation hub of Sydney’s central business district. Our honours include the 2018 CPA NSW President’s Award for Excellence, the 2020 Australian Small Business Champion Award Finalist, the 2021 Australia’s well-known media ‘Accountants Daily’ the Accounting Firm of the Year Award Finalist and the 2022 Start-up Firm of the Year Award Finalist, and the 2023 Hong Kong-Australia Business Association Business Award Finalist.

Pitt Martin Group qualifications include over fifteen years of professional experience in accounting industry, membership certification of the Chartered Accountants Australia and New Zealand (CA ANZ), membership certification of the Australian Society of Certified Practising Accountants (CPA), Registered Australia Tax Agents, certified External Examiner of the Law Societies of New South Wales, Victoria, and Western Australia Law Trust Accounts, membership certification of the Finance Brokers Association of Australia Limited (FBAA), Registered Agents of the Australian Securities and Investments Commission (ASIC), certified Advisor of accounting software such as XERO, QUICKBOOKS, MYOB, etc.

This content is for reference only and does not constitute advice on any individual or group’s specific situation. Any individual or group should take action only after consulting with professionals. Due to the timeliness of tax laws, we have endeavoured to provide timely and accurate information at the time of publication, but cannot guarantee that the content stated will remain applicable in the future. Please indicate the source when forwarding this content.

By Zoe Ma @ Pitt Martin Tax

Read more

FBT Lessons from a Landmark Case

As Fringe Benefits Tax (FBT) season approaches, family businesses should take a closer look at how they provide benefits to working directors and family members. A recent court case has drawn significant attention in this area—not only because of its facts, but also because of its journey through three levels of review and what it ultimately means for closely held structures.

For many family-run businesses, the line between “ownership benefits” and “employment benefits” is often blurred. This case serves as a timely reminder that how benefits are characterised—and documented—can make all the difference.

A business built on overlapping roles

The case involved three brothers who operated a large business empire through a discretionary trust. The group’s activities spanned petrol stations, convenience stores, fast food outlets, and more. The brothers were deeply involved in the business, acting as directors, decision-makers, and controllers of the trust.

However, unlike traditional executives, they did not receive formal salaries or wages. Instead, profits and economic benefits flowed through the family trust, of which they were beneficiaries.

Among the benefits provided was access to a fleet of over 40 luxury and high-performance vehicles, used for both business and personal purposes. Importantly, the private use component was not treated as salary. Instead, related costs were allocated to a beneficiary account and later offset through trust distributions.

From a commercial perspective, this type of arrangement is not unusual in family groups. But from a tax perspective, it raised a critical question: were these benefits provided as part of employment, or as part of ownership?

The ATO’s position

The Australian Taxation Office (ATO) took the view that the private use of the vehicles gave rise to FBT liabilities. Their argument was straightforward: the brothers were effectively employees, and the benefits were provided in respect of their work.

If accepted, this would significantly broaden the application of FBT in family business contexts—especially where individuals perform active roles without formal remuneration.

Three decisions, three different outcomes

What makes this case particularly noteworthy is its progression through three levels of decision-making, each reaching a different conclusion.

1. Administrative Appeals Tribunal (AAT)
The AAT initially ruled in favour of the taxpayer. It found that the brothers were not “employees” for FBT purposes. Even if they were treated as employees on a hypothetical basis, the Tribunal concluded that the vehicle benefits were not provided “in respect of” employment. Instead, they arose from the brothers’ roles as beneficiaries and controllers of the trust.

2. Federal Court (single judge)
The Commissioner appealed, and the Federal Court overturned the AAT’s decision. The judge took a broader view of the FBT rules, finding that the brothers could be treated as employees under the legislation. On that basis, the vehicle benefits were considered to be connected to their employment, and therefore subject to FBT.

This decision caused concern among advisors and business owners, as it suggested a potentially wider reach of FBT into family business arrangements.

3. Full Federal Court (final decision)
The matter was then appealed again—this time to the Full Federal Court. In March 2026, the Full Court unanimously allowed the taxpayer’s appeal and effectively restored the AAT’s original decision.

The Full Court confirmed two key points:

  • It was open to conclude that the brothers were not employees in the traditional legal sense, despite their active involvement in the business.
  • Even if they were employees, there was not a sufficient connection between the benefits and any employment relationship.

This final decision provides an important degree of reassurance for family businesses.

Key takeaways: it’s about substance, not labels

One of the strongest messages from the case is that substance matters more than labels.

The courts looked beyond titles such as “director” and focused on the actual nature of the relationship. Factors such as the absence of employment contracts, lack of wages and leave entitlements, and the existence of separate operational managers all supported the conclusion that the brothers were not employees in the ordinary sense.

Equally important was the purpose of the benefits. The vehicles were not provided as a substitute for salary, but rather as part of the broader economic entitlements flowing from the trust structure.

For family businesses, this reinforces the idea that simply holding multiple roles does not automatically trigger FBT. The key is identifying which role is dominant in a given context.

Why documentation is critical

While the outcome was favourable to the taxpayer, it should not be seen as a green light for informal arrangements.

A major factor in the case was how the benefits were treated and recorded. The use of beneficiary accounts and trust distributions helped support the argument that the benefits were linked to ownership, not employment.

Without this level of documentation, the outcome could have been very different.

In practice, this means:

  • Clearly recording trust distributions through trustee resolutions
  • Ensuring accounting treatment aligns with the intended character of the benefit
  • Avoiding inconsistent or mixed treatment across different records

Practical implications for family businesses

The case highlights several practical points that business owners should consider as part of their FBT review:

1. Not all benefits are subject to FBT
Benefits provided to family members in discretionary trusts are not automatically caught. The connection to employment must be clearly established.

2. Review dual-capacity individuals
Where individuals act as both beneficiaries and active workers, their arrangements deserve closer scrutiny. These are the situations most likely to attract ATO attention.

3. Consider how benefits are structured
If a benefit is effectively a substitute for salary, FBT risk increases. If it is genuinely linked to ownership or trust entitlements, the position may be stronger.

4. Don’t ignore other tax risks
Arrangements involving private companies and trusts may also raise issues under other provisions, such as Division 7A.

5. Be prepared for scrutiny
The ATO continues to focus on closely held groups, particularly where there is a mismatch between economic benefits and reported income.

A timely reminder before FBT season

As FBT lodgement deadlines approach, this case is a useful reminder that the rules are not always straightforward—but they are also not as broad as sometimes feared.

The final outcome confirms that FBT does not automatically apply to every benefit provided within a family business structure. However, it also reinforces that each arrangement will be judged on its specific facts, supported by evidence and documentation.

For businesses providing vehicles, expense payments, or other perks to family members—especially in the absence of formal salaries—now is the time to review those arrangements carefully.

Getting it right upfront is far easier than defending it later.

Pitt Martin Group is a firm of Chartered Accountants, providing services including taxation, accounting, business consulting, self-managed superannuation funds, auditing and mortgage & finance. We spend hundreds of hours each year on training and researching new tax laws to ensure our clients can maximize legitimate tax benefit. Our contact information are phone +61292213345 or email info@pittmartingroup.com.au. Pitt Martin Group is located in the convenient transportation hub of Sydney’s central business district. Our honours include the 2018 CPA NSW President’s Award for Excellence, the 2020 Australian Small Business Champion Award Finalist, the 2021 Australia’s well-known media ‘Accountants Daily’ the Accounting Firm of the Year Award Finalist and the 2022 Start-up Firm of the Year Award Finalist, and the 2023 Hong Kong-Australia Business Association Business Award Finalist.

Pitt Martin Group qualifications include over fifteen years of professional experience in accounting industry, membership certification of the Chartered Accountants Australia and New Zealand (CA ANZ), membership certification of the Australian Society of Certified Practising Accountants (CPA), Registered Australia Tax Agents, certified External Examiner of the Law Societies of New South Wales, Victoria, and Western Australia Law Trust Accounts, membership certification of the Finance Brokers Association of Australia Limited (FBAA), Registered Agents of the Australian Securities and Investments Commission (ASIC), certified Advisor of accounting software such as XERO, QUICKBOOKS, MYOB, etc.

This content is for reference only and does not constitute advice on any individual or group’s specific situation. Any individual or group should take action only after consulting with professionals. Due to the timeliness of tax laws, we have endeavoured to provide timely and accurate information at the time of publication, but cannot guarantee that the content stated will remain applicable in the future. Please indicate the source when forwarding this content.

By Yvonne Shao @ Pitt Martin Tax

Read more