Skip to main content Skip to search

Posts by Alex Cramery

Australian Tax Residency

Australian Tax Residency: ATO Travel Rules

If you travel overseas regularly for work, family or personal reasons, your Australian tax residency status and international travel records could become increasingly important when managing your tax affairs.

On 24 August 2026, the Australian Taxation Office (ATO) gazetted its latest passenger movements data-matching program. Under the program, the Department of Home Affairs is expected to provide the ATO with international travel information relating to approximately 115,000 individuals each year, covering the 2026–27 to 2028–29 income years.

The ATO can use this information to compare travel movements against existing tax records and identify potential discrepancies involving tax residency, income reporting, tax return lodgements and other tax obligations.

For Australians working overseas, people who have moved abroad and taxpayers who spend extended periods outside Australia, understanding the relevant tax residency rules and maintaining accurate travel records can help reduce uncertainty and support a consistent tax position.

What Is the ATO’s Passenger Movements Data-Matching Program?

The ATO’s passenger movements data-matching program allows it to obtain international travel information from the Department of Home Affairs and compare that information with its own records.

The information may include:

  • An individual’s name and date of birth
  • International arrival and departure dates
  • Passport details
  • Citizenship and visa status

The program is intended to help the ATO identify potential inconsistencies in tax registration, lodgement, income reporting, payment obligations and tax residency.

For example, if a taxpayer reports that they moved overseas on a particular date but passenger movement records indicate a different departure date, the ATO may seek further information to understand the discrepancy.

A difference in travel dates does not automatically mean that a taxpayer has made an error. However, accurate records can help explain the circumstances and support the position adopted in a tax return.

Why Is Australian Tax Residency Important?

Your Australian tax residency status can significantly affect how your income and other tax obligations are treated.

Australian tax residents are generally taxed on their worldwide income, while foreign residents are generally taxed on their Australian-sourced income, subject to applicable Australian tax law and any relevant double tax agreements.

Your residency status may also affect:

  • Income tax: Whether foreign employment income, overseas investments and other foreign income must be reported in Australia.
  • Tax-free threshold: Whether you qualify for the Australian tax-free threshold and how it applies to your circumstances.
  • Medicare levy: Whether you have Medicare levy obligations or qualify for an exemption.
  • Capital gains tax (CGT): How gains from Australian property and other assets are treated, including eligibility for certain exemptions.
  • Part-year residency: How your tax obligations are calculated if you become or cease to be an Australian tax resident during an income year.

If you have moved overseas, returned to Australia after an extended absence or maintained connections with Australia while living abroad, reviewing your residency position can be an important part of preparing your tax return.

For further information, refer to the Australian Taxation Office’s guidance on Australian residency for tax purposes.

Does Spending Time Overseas Automatically Make You a Foreign Tax Resident?

No. Spending time overseas does not automatically make you a foreign resident for Australian tax purposes.

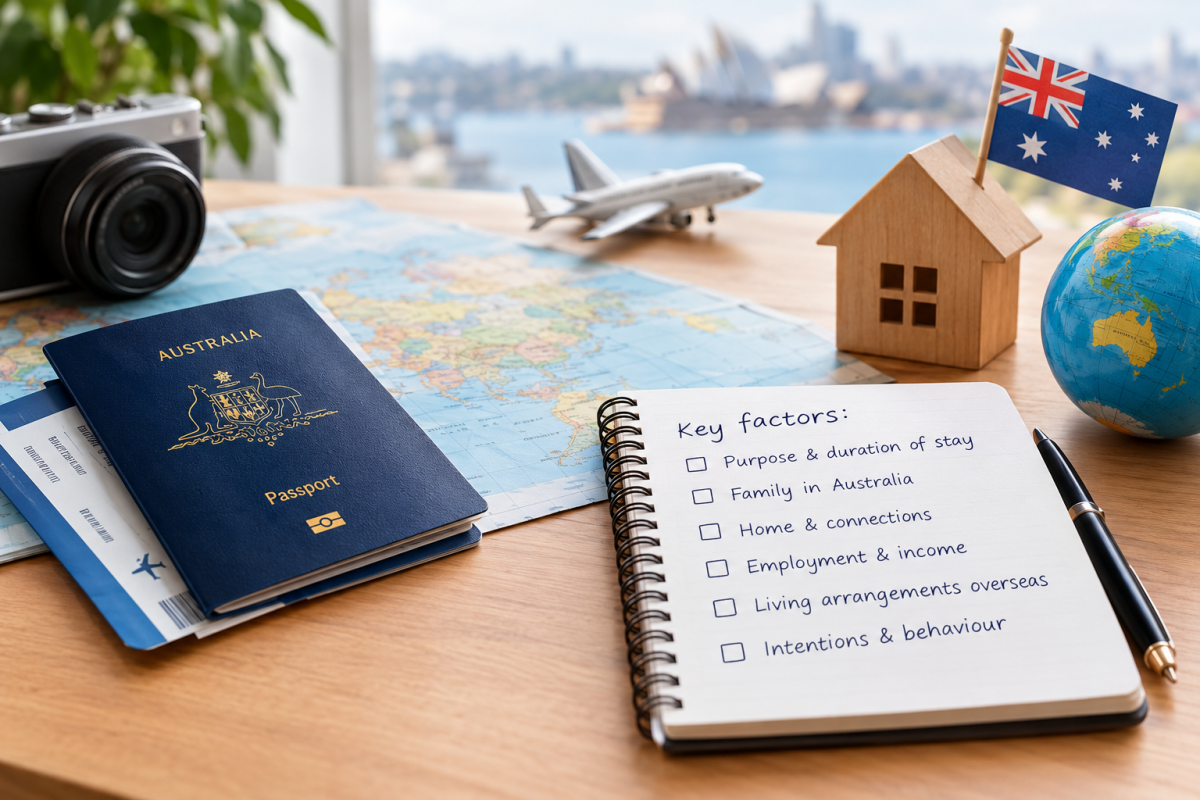
The ATO considers the relevant residency tests and the overall circumstances of each individual. Depending on the circumstances, relevant factors may include:

  • The purpose and intended duration of your overseas stay
  • Whether your spouse, children or other immediate family remain in Australia
  • Whether you maintain a home or other significant connections in Australia
  • Your employment arrangements and economic ties
  • Your living arrangements and connections in another country
  • Your intentions and behaviour before, during and after the move

The number of days you spend outside Australia may be relevant, but it does not determine your residency status in every case.

For example, someone working overseas temporarily may retain Australian tax residency, while another individual who establishes a life in another country may have different residency outcomes depending on their circumstances.

The key point is that Australian tax residency is determined by the applicable legal tests and your overall circumstances, not simply by the number of days you spend overseas.

Keeping a clear record of your travel dates, living arrangements and significant changes in circumstances can help support an assessment of your residency position.

When Can Your Overseas Travel History Affect Your Tax Return?

Your international travel history may be particularly relevant in several common situations.

1. Becoming or Ceasing to Be an Australian Tax Resident

If you become or cease to be an Australian tax resident during an income year, your arrival and departure dates may help establish the timeline of your move.

These dates can form part of the evidence supporting your residency position and may be relevant when determining how income is treated during different periods of the year.

They may also affect the calculation of your part-year tax-free threshold, where applicable.

However, departure from Australia does not, by itself, establish that you have ceased to be an Australian tax resident. Your living arrangements, intentions, family connections and other relevant circumstances must also be considered.

2. Working Overseas or Earning Foreign Income

If you regularly travel overseas for work, your travel records may help establish when you were in Australia and when you were working or staying overseas.

This can be relevant if you:

  • Work for an overseas employer
  • Undertake international assignments
  • Earn foreign employment income
  • Operate a business across multiple countries
  • Receive overseas investment income while maintaining Australian connections

Your Australian tax obligations will depend on factors such as your residency status, the nature and source of your income, and any applicable double tax agreement.

Maintaining accurate travel records alongside employment contracts, payslips and other supporting documents can help substantiate the tax treatment adopted in your return.

3. Selling an Australian Property After Moving Overseas

If you move overseas and later sell an Australian property, your tax residency history may affect the capital gains tax treatment of the sale.

Australian real estate can remain subject to Australian CGT even when the owner is a foreign resident. Foreign residency can also restrict access to certain concessions, including the main residence exemption, subject to applicable exceptions and transitional rules.

The dates you lived in your property, moved overseas, changed tax residency status and eventually sold the property may be relevant when assessing your CGT position.

If you are considering selling an Australian property while living overseas, obtaining tax advice before the sale can help you understand the potential tax consequences and any applicable restrictions.

For more information, see the ATO’s guidance on Capital Gains Tax.

How to Keep Accurate Overseas Travel Records

Maintaining accurate records is a practical way to support your Australian tax residency position and respond to questions if the ATO requests further information.

Consider the following steps.

Keep a Detailed Travel History

Record the departure and arrival dates for each international trip, including the relevant income year. Where necessary, distinguish between your physical travel dates and the dates you established or ceased a particular living arrangement.

Retain Supporting Documents

Keep relevant documents where available, including:

  • Flight itineraries and boarding passes
  • Passport records and travel confirmations
  • Employment contracts and overseas assignment details
  • Overseas accommodation or residential records
  • Documents relating to a move to or from Australia

These records may help explain your movements and provide context for your residency position.

Document Significant Changes in Your Circumstances

If you move overseas, relocate your family, change employers or establish a home in another country, retain records of those changes.

Travel dates alone may not establish your tax residency status, so documenting the wider circumstances can be valuable.

Review Your Tax Residency Before Lodging Your Return

Before lodging your Australian tax return, check that your travel dates and other relevant information are accurate and consistent with your supporting documents.

If you have spent substantial time overseas or your circumstances have changed during the year, consider reviewing your residency position before finalising your return.

Seek Professional Advice When Your Position Is Unclear

Australian tax residency can be complex, particularly when you maintain homes, family connections, employment or financial interests in more than one country.

An experienced tax adviser can help you assess the relevant residency tests, understand potential tax obligations and identify the records needed to support your position.

What Happens If Your Travel Records Do Not Match ATO Information?

If the dates reported to the ATO differ from passenger movement information, the discrepancy could prompt the ATO to request clarification or supporting evidence.

A discrepancy does not automatically mean you have breached your tax obligations. Differences may arise for legitimate reasons, and international travel dates are only one part of assessing tax residency.

However, having reliable records can make it easier to explain the difference and demonstrate how you arrived at your tax position.

This is particularly important if you have moved between countries, worked overseas for extended periods or have a residency position that depends on several factors.

Rather than waiting for a query, reviewing your records before lodging your tax return can help identify potential inconsistencies early.

Frequently Asked Questions About Australian Tax Residency and Overseas Travel

Does the ATO track overseas travel?

Under its passenger movements data-matching program, the ATO is expected to receive travel information from the Department of Home Affairs for approximately 115,000 individuals each year from 2026–27 to 2028–29. The information may be compared with tax records to identify potential discrepancies and compliance issues.

How long can I stay overseas without losing Australian tax residency?

There is no single period of overseas absence that automatically determines whether you remain an Australian tax resident. The applicable residency tests and your overall circumstances must be considered, including your intentions, family connections, living arrangements and ties to Australia.

Do Australian tax residents need to declare overseas income?

Australian tax residents are generally required to declare their worldwide income, including relevant foreign income, subject to applicable tax rules and any available relief. The treatment of specific income depends on your circumstances and any relevant double tax agreement.

Can I be an Australian tax resident while living overseas?

Yes. Living or working overseas does not automatically mean you cease to be an Australian tax resident. Your status depends on the relevant residency tests and the facts of your situation.

Why should I keep records of my arrival and departure dates?

Accurate travel records can help establish the timeline of your movements, support your residency assessment and explain differences between the information reported in your tax return and the information available to the ATO.

Can my tax residency affect the sale of my Australian home?

Yes. Your residency status can affect the availability of certain capital gains tax concessions, including the main residence exemption. The outcome depends on the applicable rules, the property and your individual circumstances. Seek advice before selling if you live overseas or expect to change residency status.

Need Help?

Pitt Martin Group’s Sydney tax accountants can assist with Australian tax residency assessments, international tax compliance, foreign income reporting, capital gains tax implications and tax return preparation. Whether you are relocating overseas, returning to Australia or concerned about discrepancies between your travel history and tax records, contact our experienced tax advisers for professional guidance tailored to your circumstances.

Pitt Martin Group is a firm of Chartered Accountants, providing services including taxation, accounting, business consulting, self-managed superannuation funds, auditing and mortgage & finance. We spend hundreds of hours each year on training and researching new tax laws to ensure our clients can maximize legitimate tax benefit. Our contact information are phone +61292213345 or email info@pittmartingroup.com.au. Pitt Martin Group, Sydney tax accountants, is located in the convenient transportation hub of Sydney’s central business district. Our honours include the 2018 CPA NSW President’s Award for Excellence, the 2020 Australian Small Business Champion Award Finalist, the 2021 Australia’s well-known media ‘Accountants Daily’ the Accounting Firm of the Year Award Finalist and the 2022 Start-up Firm of the Year Award Finalist, and the 2023 Hong Kong-Australia Business Association Business Award Finalist.

Pitt Martin Group qualifications include over fifteen years of professional experience in accounting industry, Registered Australia Tax Agents, membership certification of the Chartered Accountants Australia and New Zealand (CA ANZ), certified External Examiner of the Law Societies of New South Wales, Victoria, and Western Australia Law Trust Accounts, membership certification of the Finance Brokers Association of Australia Limited (FBAA), Registered Agents of the Australian Securities and Investments Commission (ASIC), certified Advisor of accounting software such as XERO, QUICKBOOKS, MYOB, etc.

This content is for reference only and does not constitute advice on any individual or group’s specific situation. Any individual or group should take action only after consulting with professionals. Due to the timeliness of tax laws, we have endeavoured to provide timely and accurate information at the time of publication, but cannot guarantee that the content stated will remain applicable in the future. Please indicate the source when forwarding this content.

By Alex Cramery @ Pitt Martin Tax

Read more
ATO Travel Allowance Rates 2026–27

ATO Travel Allowance Rates 2026–27

The Australian Taxation Office (ATO) has released its reasonable travel and overtime meal allowance rates for the 2026–27 income year in Taxation Determination TD 2026/4.

The updated rates include a $40.00 reasonable amount for overtime meal expenses, together with updated reasonable amounts for domestic and overseas work-related travel based on salary levels and travel destinations.

However, there is an important distinction employees and employers need to understand:

The ATO’s reasonable travel allowance rates are not automatic tax deductions.

Receiving a travel or overtime meal allowance does not automatically entitle an employee to claim the ATO’s published amount as a tax deduction. The employee must satisfy specific requirements, and incorrectly claiming an amount can result in a deduction being denied, as well as potential interest and penalties.

ATO Travel Allowance Rates

The ATO publishes reasonable amounts each income year for certain work-related travel and overtime meal expenses.

For the 2026–27 income year, the updated amounts are contained in TD 2026/4 and cover certain:

  • Domestic travel expenses;
  • Overseas travel expenses;
  • Meal and incidental expenses while travelling for work; and
  • Overtime meal expenses.

These amounts can be useful because, where the relevant conditions are satisfied, an employee may be able to claim certain deductible expenses without keeping receipts for every individual expense.

However, the ATO’s reasonable amounts should be regarded as a substantiation concession or benchmark, not as an automatic deduction available to every employee.

ATO Overtime Meal Allowance Rates

The ATO’s reasonable amount for an overtime meal expense for the 2026–27 income year is $40.00.

This does not mean every employee who works overtime can automatically claim $40 as a tax deduction.

The employee must generally receive a genuine overtime meal allowance from their employer and satisfy the applicable requirements. The meal expense must also have actually been incurred and be deductible under the tax rules.

In simple terms:

The $40.00 reasonable amount is not a standard $40 tax deduction for everyone who works overtime.

ATO Travel Allowance Rates Tax Deduction Rules

An employee cannot simply receive a travel allowance and automatically claim the corresponding ATO reasonable amount as a tax deduction.

The underlying expense must still be genuinely incurred and satisfy the requirements for a work-related tax deduction.

The ATO’s reasonable amount may allow an employee to rely on simplified substantiation rules in certain circumstances. It does not create a deduction where there is no deductible expense.

For more information, employees should also review your firm’s guide to work-related tax deductions.

When Does the ATO Travel Allowance Rates Apply?

The ATO’s reasonable amounts generally become relevant where an employee receives a genuine travel or overtime meal allowance from their employer.

As a practical matter, the allowance should generally:

  • Be paid specifically to cover work-related travel or overtime meal expenses;
  • Relate to particular work travel or overtime rather than being a general payment;
  • Be separately identified from normal salary or wages; and
  • Be intended to cover expenses the employee is expected to incur.

The exact tax treatment will depend on the employee’s circumstances and the applicable ATO requirements.

If Your ATO Travel Allowance Rates are Included in Salary?

If an amount has simply been incorporated into an employee’s normal salary package, or is not separately identified as a travel or overtime meal allowance, the ATO’s reasonable amount provisions may not apply.

Instead, the employee may need to rely on the normal substantiation and record-keeping rules when determining whether an expense can be claimed.

This is an important issue for employers when establishing payroll arrangements.

Employers should make sure allowances are properly structured, separately identified and supported by appropriate documentation.

What ATO Travel Allowance Rates Can an Employee Claim?

The ATO’s reasonable amount is not a guaranteed deduction.

Generally, an employee can only claim an expense where it:

  1. Was actually incurred;
  2. Was incurred in earning assessable income;
  3. Is not private or domestic;
  4. Has not been reimbursed by the employer; and
  5. Meets the applicable substantiation and record-keeping requirements.

For example, if an employee receives a travel allowance and spends less than the applicable ATO reasonable amount, they should not assume they can automatically claim the full published rate.

Similarly, an employee should not claim an expense that was never actually incurred.

The reasonable amount is primarily relevant to substantiation, rather than creating an entitlement to a particular deduction.

Do You Need Receipts If You Receive an ATO Travel Allowance Rate?

Not necessarily.

Where the relevant conditions are satisfied, an employee may be able to rely on the ATO’s reasonable amount provisions without keeping receipts for every individual meal or incidental expense.

However, this does not mean that employees should keep no records.

Employees should maintain sufficient information to demonstrate:

  • They travelled for work;
  • The relevant travel occurred;
  • They received a travel allowance;
  • They incurred deductible expenses; and
  • Their claim satisfies the relevant requirements.

Keeping supporting records can be particularly important if the ATO reviews the employee’s tax return

What Records Should Employees Keep?

Even where individual receipts are not required under the applicable reasonable amount provisions, good record keeping remains important.

Useful records can include:

  • A diary of work-related trips and overnight travel;
  • Dates and locations of business travel;
  • Details of meals and incidental expenses;
  • Bank or credit card records showing expenses personally paid;
  • A representative selection of receipts; and
  • Documentation from the employer confirming the allowance and travel arrangements.

Employees should not rely solely on the ATO’s published rates without maintaining supporting evidence of their travel and expenses.

Do You Need a Travel Diary for Six or More Nights?

Additional travel diary requirements can apply where an employee travels for work for six or more consecutive nights.

In these circumstances, employees will generally need to maintain a travel diary recording relevant information such as:

  • The dates of travel;
  • Locations visited;
  • The activities undertaken; and
  • The purpose of the travel.

Employees undertaking extended work travel should therefore pay particular attention to their record-keeping obligations.

ATO Travel Allowance Rates Tax Deduction Mistakes

Understanding the common mistakes can help employees avoid incorrect claims.

1. Treating the ATO rate as an automatic deduction

The published rate is not an automatic deduction. The employee must satisfy the relevant requirements.

2. Claiming expenses that were never incurred

The reasonable amount does not allow an employee to claim an expense they did not actually pay.

3. Treating ordinary salary as a travel allowance

An amount incorporated into ordinary salary or wages does not necessarily qualify as a separate travel allowance.

4. Claiming reimbursed expenses

Employees generally cannot claim a tax deduction for an expense that has already been reimbursed by their employer.

5. Keeping no supporting records

Even where individual receipts may not be required, employees should maintain sufficient evidence to support their claim.

6. Forgetting travel diary requirements

Extended work travel can trigger additional travel diary obligations. Employees should check these requirements before undertaking longer trips.

Practical Tips for Employees

If you receive a travel or overtime meal allowance during the 2026–27 income year, consider the following:

  • Check your payslip: Make sure the allowance is separately identified from ordinary salary or wages.
  • Understand what the allowance covers: Confirm whether it relates to travel, meals, incidentals or overtime meals.
  • Keep records throughout the year: A simple travel diary can be much easier than reconstructing travel months later.
  • Retain supporting documents: Keep bank statements, credit card records and relevant receipts where available.
  • Only claim genuine expenses: Do not treat the ATO reasonable amount as an automatic deduction.
  • Take extra care on extended trips: Check the travel diary requirements when you are away for six or more consecutive nights.
  • Review your tax return carefully: Make sure any deduction is supported by the actual circumstances.

Practical Tips for Employers

Employers should also review their employee travel and overtime meal allowance arrangements for 2026–27.

Consider whether:

  • Allowances are separately identified in payroll records;
  • Employees understand what each allowance is intended to cover;
  • Allowances are supported by appropriate policies and documentation;
  • Employees know what records they should retain;
  • Payroll and tax reporting processes correctly identify allowances; and
  • The business’s allowance arrangements remain appropriate for the current income year.

Clear documentation can help reduce confusion for both employers and employees.

ATO Travel Allowance Rates 2026–27: Key Takeaway

The ATO reasonable travel allowance rates for 2026–27, set out in TD 2026/4, provide useful benchmarks for employees and employers.

The $40.00 overtime meal allowance rate, together with the updated domestic and overseas travel amounts, should not be interpreted as an automatic tax deduction.

The key distinction is:

An ATO reasonable amount may allow certain substantiation requirements to be relaxed, but it does not create an entitlement to claim an expense that was not actually incurred.

Employees should ensure they have received a genuine allowance, incurred genuine deductible expenses and maintained appropriate records.

Employers should ensure their allowance arrangements are properly structured, documented and communicated to employees.

Reviewing these arrangements early in the 2026–27 income year can help reduce the risk of incorrect deductions, ATO scrutiny, interest and penalties.

If you or your employees receive travel allowances or overtime meal allowances, now is a good time to review your arrangements. We can help you assess whether your allowances meet the relevant ATO requirements, understand the reasonable amounts and establish appropriate record-keeping processes.

ATO Travel Allowance Rates 2026–27: FAQs

What is the ATO overtime meal allowance for 2026–27?

The ATO’s reasonable amount for overtime meal expenses for the 2026–27 income year is $40.00. This is not automatically a $40 tax deduction. The relevant conditions must be satisfied before the reasonable amount provisions can be relied upon.

Can I automatically claim the ATO travel allowance rate?

No. The ATO’s reasonable travel amounts are not automatic tax deductions. Generally, the employee must have actually incurred deductible work-related expenses and satisfy the applicable requirements.

Do I need receipts if I receive a travel allowance?

Not necessarily. Where the relevant conditions are satisfied, an employee may not need receipts for every individual expense. However, appropriate supporting records should still be maintained.

What is TD 2026/4?

TD 2026/4 is the ATO Taxation Determination that sets out the reasonable amounts for certain domestic and overseas travel expenses and overtime meal expenses for the 2026–27 income year.

Do I need a travel diary for work travel?

Additional travel diary requirements can apply when an employee is travelling for work for six or more consecutive nights. Employees undertaking extended work travel should check the applicable requirements and maintain the necessary records.

Are ATO reasonable travel amounts the same as tax deductions?

No. The reasonable amounts are primarily relevant to substantiation requirements. They do not mean an employee is automatically entitled to claim the published amount as a tax deduction.

Need Help?

By working with us as your professional tax accountant and mortgage broker, you can be confident that your loans are structured to protect your tax position, maximise deductions, and avoid costly mistakes, giving you greater peace of mind and more control over your financial future.

Pitt Martin Group is a firm of Chartered Accountants, providing services including taxation, accounting, business consulting, self-managed superannuation funds, auditing and mortgage & finance. We spend hundreds of hours each year on training and researching new tax laws to ensure our clients can maximize legitimate tax benefit. Our contact information are phone +61292213345 or email info@pittmartingroup.com.au. Pitt Martin Group is located in the convenient transportation hub of Sydney’s central business district. Our honours include the 2018 CPA NSW President’s Award for Excellence, the 2020 Australian Small Business Champion Award Finalist, the 2021 Australia’s well-known media ‘Accountants Daily’ the Accounting Firm of the Year Award Finalist and the 2022 Start-up Firm of the Year Award Finalist, and the 2023 Hong Kong-Australia Business Association Business Award Finalist.

Pitt Martin Group qualifications include over fifteen years of professional experience in accounting industry, Registered Australia Tax Agents, membership certification of the Chartered Accountants Australia and New Zealand (CA ANZ), certified External Examiner of the Law Societies of New South Wales, Victoria, and Western Australia Law Trust Accounts, membership certification of the Finance Brokers Association of Australia Limited (FBAA), Registered Agents of the Australian Securities and Investments Commission (ASIC), certified Advisor of accounting software such as XERO, QUICKBOOKS, MYOB, etc.

This content is for reference only and does not constitute advice on any individual or group’s specific situation. Any individual or group should take action only after consulting with professionals. Due to the timeliness of tax laws, we have endeavoured to provide timely and accurate information at the time of publication, but cannot guarantee that the content stated will remain applicable in the future. Please indicate the source when forwarding this content.

By Alex Cramery @ Pitt Martin Tax
Read more
Sharing Economy Tax Tips for Taxpayers in Australia

Sharing Economy Tax Tips for Taxpayers in Australia

More Australians are turning to the sharing economy to boost their income. Whether you’re driving passengers, renting out a spare room, completing freelance jobs, hiring out equipment or earning money from online content, these flexible income streams can provide welcome financial support.

While earning extra income has many benefits, it’s important to understand that it can also create tax obligations. Many people mistakenly assume that income earned through digital platforms is too small or too casual to report. In reality, most sharing economy income is taxable and generally needs to be included in your annual tax return.

Because this income isn’t always automatically pre-filled when you lodge your return, it’s your responsibility to keep accurate records and ensure everything is reported correctly.

The ATO Is Paying Closer Attention to Sharing Economy Activities

The Australian Taxation Office (ATO) has significantly expanded its ability to monitor sharing economy activities. Through sophisticated data-matching programs, information supplied by many online platforms can now be compared with the income taxpayers report each year.

As reporting requirements continue to expand, failing to disclose sharing economy income is becoming much easier for the ATO to identify. Where inconsistencies are found, the ATO may contact taxpayers for clarification and, if necessary, apply amended assessments, interest charges or penalties.

What Is Considered the Sharing Economy?

The sharing economy covers a wide range of activities where individuals earn money using online marketplaces or digital platforms. Common examples include:

  • Driving for ride-share services such as Uber or DiDi
  • Renting out short-term accommodation through Airbnb, Stayz or similar websites
  • Hiring out assets including cars, caravans, trailers, tools, storage space or parking spots
  • Providing freelance or on-demand services such as deliveries, cleaning, gardening, graphic design or handyman work
  • Creating online content, streaming, selling digital products or receiving payments through creator platforms

Even if your activity is only occasional or earns a relatively small amount, the income may still need to be declared. Whether you’re operating as a business, working independently or simply earning some extra cash, tax obligations can still apply.

Why Record-Keeping Matters

One of the easiest ways to avoid problems at tax time is to maintain accurate financial records throughout the year. While many platforms provide payment summaries, relying solely on those reports may not capture everything you need.

Keeping your own records of income and retaining receipts for work-related expenses will make preparing your tax return much simpler. Depending on the nature of your activity, deductible expenses may include platform commissions, fuel, repairs, insurance, cleaning costs, equipment purchases and other expenses directly connected to earning your income.

Good documentation also provides valuable evidence should the ATO ever request further information.

Understand the Deductions You’re Entitled to Claim

Many people miss legitimate tax deductions simply because they don’t realise what they’re eligible to claim. The expenses you can deduct will depend on how you earn your income and whether those costs are directly related to producing that income.

Every situation is different, so obtaining professional tax advice can help ensure you’re claiming appropriate deductions while remaining compliant with Australian tax law.

Don’t Get Caught by an Unexpected Tax Bill

Unlike employees, people earning income through sharing economy platforms often don’t have tax withheld from their payments. As a result, it’s common to receive a larger-than-expected tax bill when lodging a return.

Planning ahead can help reduce financial stress. Some taxpayers choose to transfer a percentage of each payment into a separate savings account, while others make voluntary tax payments during the year or enter the PAYG instalment system where appropriate.

Other Sharing Economy Tax Responsibilities

Income tax isn’t the only consideration for sharing economy participants. Depending on the type and size of your activities, you may also need to register for GST.

If you provide ride-share services, GST registration is generally required regardless of your annual turnover. Other businesses may need to register once they reach the applicable turnover threshold.

You may also wish to consider making additional superannuation contributions. Besides helping build your retirement savings, these contributions may provide tax planning opportunities depending on your individual circumstances.

Taking a Long-Term Approach

Treating your sharing economy activity like a small business can make managing your finances much easier. Keeping organised records, reviewing your profitability regularly and planning for future tax obligations can improve cash flow and support better financial decision-making as your income grows.

Before lodging your tax return, take the time to review your records and confirm you’ve included all income earned through online platforms. Seeking advice from your accountant can help identify available deductions, ensure your reporting is accurate and minimise the risk of unnecessary ATO enquiries.

The sharing economy continues to create flexible earning opportunities for Australians. By understanding your tax obligations, maintaining good records and planning ahead, you can enjoy the benefits of these additional income streams while remaining confident that you’re meeting your tax responsibilities.

For more information about sharing economy income and your tax obligations, visit the ATO’s guidance or speak with us about your individual circumstances.

Need Help?

By working with us as your professional tax accountant and mortgage broker, you can be confident that your loans are structured to protect your tax position, maximise deductions, and avoid costly mistakes, giving you greater peace of mind and more control over your financial future.

Pitt Martin Group is a firm of Chartered Accountants, providing services including taxation, accounting, business consulting, self-managed superannuation funds, auditing and mortgage & finance. We spend hundreds of hours each year on training and researching new tax laws to ensure our clients can maximize legitimate tax benefit. Our contact information are phone +61292213345 or email info@pittmartingroup.com.au. Pitt Martin Group is located in the convenient transportation hub of Sydney’s central business district. Our honours include the 2018 CPA NSW President’s Award for Excellence, the 2020 Australian Small Business Champion Award Finalist, the 2021 Australia’s well-known media ‘Accountants Daily’ the Accounting Firm of the Year Award Finalist and the 2022 Start-up Firm of the Year Award Finalist, and the 2023 Hong Kong-Australia Business Association Business Award Finalist.

Pitt Martin Group qualifications include over fifteen years of professional experience in accounting industry, Registered Australia Tax Agents, membership certification of the Chartered Accountants Australia and New Zealand (CA ANZ), certified External Examiner of the Law Societies of New South Wales, Victoria, and Western Australia Law Trust Accounts, membership certification of the Finance Brokers Association of Australia Limited (FBAA), Registered Agents of the Australian Securities and Investments Commission (ASIC), certified Advisor of accounting software such as XERO, QUICKBOOKS, MYOB, etc.

This content is for reference only and does not constitute advice on any individual or group’s specific situation. Any individual or group should take action only after consulting with professionals. Due to the timeliness of tax laws, we have endeavoured to provide timely and accurate information at the time of publication, but cannot guarantee that the content stated will remain applicable in the future. Please indicate the source when forwarding this content.

By Alex Cramery @ Pitt Martin Tax
Read more
federal budget 2026-27

Federal Budget Tax Updates For 2026

The 2026 Federal Budget tax updates have introduced changes to several key tax proposals announced by the Federal Government. The Budget was delivered on 12 May 2026 and included major changes to capital gains tax (CGT), discretionary trusts and self-managed superannuation funds (SMSFs).

Since then, the Government has reviewed feedback from businesses, tax professionals and industry groups. As a result, several key proposals have been amended. These Federal Budget 2026 tax updates provide important information for taxpayers, investors, business owners and trustees planning for future changes.

Federal Budget Tax Updates: Capital Gains

One of the biggest Budget announcements was a change to the current 50% CGT discount. Under the proposal, individuals and trusts would use an indexation system instead. A new 30% minimum tax rate would also apply to capital gains that accrue from 1 July 2027, with limited exceptions.

The Government has now announced a new Innovative Business CGT Concession. The concession aims to encourage more investment in Australian start-ups. Eligible investors, founders and employee share scheme participants could still receive the 50% CGT discount. The Government has released a consultation paper on how the concession will operate.

In addition, small businesses will also benefit from another proposed change. From 1 July 2027, the turnover limit for the 50% active asset reduction will increase. It will rise from $2 million to $10 million.

However, the other three small business CGT concessions will not change. These include the 15-year exemption, retirement exemption and small business rollover. The current $2 million turnover test will still apply. Businesses may still qualify. They need to meet the existing $6 million net asset value test.

Federal Budget Tax Updates: Trusts

The original Budget proposed a 30% minimum tax rate for discretionary trusts from 1 July 2028. Under that proposal, many testamentary trusts would have fallen within the new rules.

The Government has now changed its approach. It plans to exempt all testamentary trusts that exist for genuine testamentary purposes.

The exemption will only apply to income earned from assets that come from the deceased estate. For testamentary discretionary trusts created on or after 1 July 2028, only individuals and income tax-exempt entities can be beneficiaries if the trust is to qualify.

Federal Budget Tax Updates: SMSF’s

The Government has also announced changes for self-managed superannuation funds.

The Government also plans to change SMSF borrowing rules. Under the proposal, SMSFs could no longer use Limited Recourse Borrowing Arrangements (LRBAs) to buy residential property.

Existing borrowing arrangements are expected to remain in place under grandfathering provisions. However, new residential property borrowing through LRBAs would no longer be available once the changes begin.

What Should You Do Next?

These tax proposals could affect investment decisions, business structures, estate planning and superannuation strategies. Although the Government has already revised several measures, more changes may occur before Parliament passes the legislation.

If you own a business, invest through a trust or manage an SMSF, now is a good time to review your position. Understanding the proposed rules now can help you plan ahead.

We will continue to monitor the legislation and provide updates as more information becomes available. If you would like to discuss how these proposed reforms could affect you, please contact our team.

Need Help?

By working with us as your professional tax accountant and mortgage broker, you can be confident that your loans are structured to protect your tax position, maximise deductions, and avoid costly mistakes, giving you greater peace of mind and more control over your financial future.

Pitt Martin Group is a firm of Chartered Accountants, providing services including taxation, accounting, business consulting, self-managed superannuation funds, auditing and mortgage & finance. We spend hundreds of hours each year on training and researching new tax laws to ensure our clients can maximize legitimate tax benefit. Our contact information are phone +61292213345 or email info@pittmartingroup.com.au. Pitt Martin Group is located in the convenient transportation hub of Sydney’s central business district. Our honours include the 2018 CPA NSW President’s Award for Excellence, the 2020 Australian Small Business Champion Award Finalist, the 2021 Australia’s well-known media ‘Accountants Daily’ the Accounting Firm of the Year Award Finalist and the 2022 Start-up Firm of the Year Award Finalist, and the 2023 Hong Kong-Australia Business Association Business Award Finalist.

Pitt Martin Group qualifications include over fifteen years of professional experience in accounting industry, Registered Australia Tax Agents, membership certification of the Chartered Accountants Australia and New Zealand (CA ANZ), certified External Examiner of the Law Societies of New South Wales, Victoria, and Western Australia Law Trust Accounts, membership certification of the Finance Brokers Association of Australia Limited (FBAA), Registered Agents of the Australian Securities and Investments Commission (ASIC), certified Advisor of accounting software such as XERO, QUICKBOOKS, MYOB, etc.

This content is for reference only and does not constitute advice on any individual or group’s specific situation. Any individual or group should take action only after consulting with professionals. Due to the timeliness of tax laws, we have endeavoured to provide timely and accurate information at the time of publication, but cannot guarantee that the content stated will remain applicable in the future. Please indicate the source when forwarding this content.

By Alex Cramery @ Pitt Martin Tax
Read more
federal budget 2026-27

2026 Federal Budget Tax Changes: What You Should Consider Now

The proposed tax changes announced in the 2026 Federal Budget have created plenty of discussion.

Property investors are reviewing their portfolios. Business owners are reassessing their structures. Families using discretionary trusts are asking what happens next.

The proposed reforms focus on three key areas:

  • Negative gearing
  • Capital gains tax (CGT)
  • Discretionary trusts

Importantly, these measures are not law yet. Parliament still needs to consider and pass the legislation.

However, that does not mean you should ignore the proposals. Instead, now is a good time to understand the possible impact and plan ahead.

Why Planning Early Makes Sense

Many people are waiting for certainty before taking action.

However, smart planning does not require certainty.

The proposed negative gearing and CGT changes are due to start from 1 July 2027. Meanwhile, the trust reforms are not expected to begin until 1 July 2028.

As a result, investors and business owners have time to review their position and explore different options.

You do not need to make major changes today. However, understanding your risks and opportunities now can help you make better decisions later.

1. Review Your Existing Property Portfolio

One of the biggest Budget announcements relates to negative gearing.

The Government plans to limit negative gearing for established residential properties purchased after 12 May 2026.

Existing Investors May Have an Advantage

Current property owners could benefit from grandfathering rules.

Under the proposal, investors who owned residential property before Budget night can continue using the existing negative gearing rules.

As a result, eligible rental losses could still offset salary, business income and other taxable income.

For many investors, this may become a valuable long-term benefit.

Why This Matters

Not all investment properties may receive the same tax treatment in the future.

Because of this, now is a good time to review your portfolio.

First, identify which assets may qualify for grandfathering. Next, consider how those assets fit within your long-term investment goals.

A simple review today could uncover opportunities you may have overlooked.

2. Think Carefully About Future Property Purchases

The proposed reforms could change how investors approach new property purchases.

In the past, many investors used negative gearing when buying established residential properties.

However, future buyers may need to focus more on investment fundamentals.

Focus on Quality Investments

Tax benefits are important. However, they should never be the main reason for buying an investment property.

Instead, focus on:

  • Strong locations
  • Rental demand
  • Cash flow potential
  • Long-term growth

These factors often have a greater impact on returns than tax deductions alone.

New Builds Could Attract More Interest

In addition, the Government has indicated that newly built residential properties may continue to receive favourable tax treatment.

Some housing developments and build-to-rent projects may also qualify for concessions.

As a result, investors may begin comparing new builds more closely with established properties.

3. Identify Assets That May Need Valuations

The proposed CGT changes could create new planning opportunities.

They could also create additional record-keeping requirements.

Why Valuations Matter

Under the proposal, gains that build up before 1 July 2027 will receive different tax treatment from gains that arise after that date.

Because of this, many investors may need accurate market values as at 1 July 2027.

This could apply to:

  • Investment properties
  • Commercial real estate
  • Share portfolios
  • Business assets

Start Early

Valuations often take time.

Therefore, it makes sense to start planning well before any deadline arrives.

Good records today can save time, money and stress later.

4. Review Your Capital Gains Tax Strategy

The Government also plans to change the current CGT discount rules.

This is one of the biggest Budget announcements.

For many years, investors have relied on the 50% CGT discount when selling assets.

However, the proposed rules may change the way some investors think about future sales.

Look at Future Exit Plans

Now is a good time to review your long-term plans.

For example:

  • Which assets might you sell in the next five years?
  • How would the current rules affect the outcome?
  • How could the proposed rules change that result?

These questions can help you identify potential risks early.

Keep the Bigger Picture in Mind

Tax matters. However, it should not drive every decision.

Likewise, your investment goals, retirement plans and cash flow needs should remain key considerations.

5. Review Your Trust Structure

The proposed trust changes have attracted significant attention.

If introduced, discretionary trusts would face a minimum tax rate of 30%.

Understand the Potential Impact

Many families use discretionary trusts to distribute income among beneficiaries.

The Government wants to reduce some of the tax benefits associated with these arrangements.

As a result, some families could pay more tax under the proposed system.

Remember the Non-Tax Benefits

Importantly, trusts offer more than tax advantages.

They can also assist with:

  • Asset protection
  • Estate planning
  • Succession planning
  • Family wealth management

Therefore, trusts may still play an important role even if tax outcomes change.

6. Consider Alternative Structures

Some taxpayers may decide to review their current structures.

However, restructuring is not always the right move.

Explore Different Options

Depending on your situation, you may wish to compare:

  • Private companies
  • Fixed trusts
  • Corporate beneficiaries
  • Other business structures

Each option has strengths and weaknesses.

Avoid Rushed Decisions

Finally, avoid making major changes based on proposed legislation alone.

Instead, compare tax outcomes alongside asset protection, business goals and succession planning needs.

7. Stay Informed

The final action may be the most important.

At this stage, the proposals are not law.

Focus on Preparation, Not Panic

Many details could change before the legislation passes Parliament.

Therefore, preparation is more valuable than speculation.

Review your position. Model different scenarios. Understand your options.

Then, when more details become available, you can act with confidence.

Frequently Asked Questions

Will negative gearing be abolished?

No. The proposal restricts how some losses can be used. It does not abolish negative gearing.

Will existing properties be protected?

Under the current proposal, many existing property owners will receive grandfathering protection.

Should I restructure my trust now?

Not necessarily. First, wait for more certainty around the final legislation.

Will trusts still be useful?

Yes. In many cases, trusts will continue to provide asset protection and estate planning benefits.

Seek Advice Before Making Major Decisions

Every taxpayer’s situation is different.

For example, one investor may benefit from grandfathering rules. Another may need to review future purchase plans.

Likewise, some business owners may benefit from a restructure, while others may not.

Professional advice can help you understand the options available and avoid costly mistakes.

What Should You Do Next?

The proposed 2026 Federal Budget tax changes could affect investors, business owners and families for years to come.

However, there is still time to prepare.

Now is the ideal time to review your position, understand the possible impact and plan ahead.

By taking action early, you can make informed decisions and respond with confidence as the legislation develops.

Need Help?

By working with us as your professional tax accountant and mortgage broker, you can be confident that your loans are structured to protect your tax position, maximise deductions, and avoid costly mistakes, giving you greater peace of mind and more control over your financial future.

Pitt Martin Group is a firm of Chartered Accountants, providing services including taxation, accounting, business consulting, self-managed superannuation funds, auditing and mortgage & finance. We spend hundreds of hours each year on training and researching new tax laws to ensure our clients can maximize legitimate tax benefit. Our contact information are phone +61292213345 or email info@pittmartingroup.com.au. Pitt Martin Group is located in the convenient transportation hub of Sydney’s central business district. Our honours include the 2018 CPA NSW President’s Award for Excellence, the 2020 Australian Small Business Champion Award Finalist, the 2021 Australia’s well-known media ‘Accountants Daily’ the Accounting Firm of the Year Award Finalist and the 2022 Start-up Firm of the Year Award Finalist, and the 2023 Hong Kong-Australia Business Association Business Award Finalist.

Pitt Martin Group qualifications include over fifteen years of professional experience in accounting industry, Registered Australia Tax Agents, membership certification of the Chartered Accountants Australia and New Zealand (CA ANZ), certified External Examiner of the Law Societies of New South Wales, Victoria, and Western Australia Law Trust Accounts, membership certification of the Finance Brokers Association of Australia Limited (FBAA), Registered Agents of the Australian Securities and Investments Commission (ASIC), certified Advisor of accounting software such as XERO, QUICKBOOKS, MYOB, etc.

This content is for reference only and does not constitute advice on any individual or group’s specific situation. Any individual or group should take action only after consulting with professionals. Due to the timeliness of tax laws, we have endeavoured to provide timely and accurate information at the time of publication, but cannot guarantee that the content stated will remain applicable in the future. Please indicate the source when forwarding this content.

By Alex Cramery @ Pitt Martin Tax
Read more
Understanding the New Division 296 Tax on High Superannuation Balances

澳洲新规:养老金超过300万将面临额外税负

澳大利亚政府推出的“更精准的养老金税收优惠政策”(即 Division 296)现已正式立法,并将于2026年7月1日起生效。该措施主要针对拥有较高养老金余额的个人,引入额外的税务影响。对于相关纳税人而言,理解该政策的运作机制、立法背景以及未来的规划重点尤为重要。

政策目的

Division 296 的核心目标在于提升养老金税收优惠的公平性与长期可持续性。与全面调整整个养老金税制不同,该政策专门针对高余额人群,通过对其相关投资收益征收更高税率,使整体税收分配更加合理。

适用范围:门槛与税率影响

自2026–27财年起,当个人的养老金总余额超过以下门槛时,将适用 Division 296:

  • 300万澳元(高余额门槛)
  • 1000万澳元(超高余额门槛)

上述门槛未来将进行指数化调整。根据新规,超过相应区间的收益将适用更高的综合税率:

  • 不超过300万澳元的部分,继续适用养老金基金内15%的标准税率
  • 300万至1000万澳元区间对应的收益,将额外征收15%税,使综合税率达到30%
  • 超过1000万澳元部分的收益,将额外征收25%税,使综合税率达到40%

需要注意的是,尽管部分个人养老金余额超过上述门槛,但仍可能被排除在 Division 296 适用范围之外。例如,领取死亡抚恤养老金的未成年人,以及因人身伤害赔偿而进行结构性缴款的个人。

在个人去世时,其养老金总余额将不再存在。但除实施首年(2026–27财年)外,如该个人在该财年初的余额超过300万澳元,仍可能就该年度被征收 Division 296 税。由于养老金通常不属于遗产范围,这一规定在遗产规划中应予以重点考虑。

税额计算与征收机制

对于自管养老金基金(SMSF)而言,Division 296 收益的计算以基金的应税收入为基础,并进行一系列调整。这些调整包括:计入应税收入的缴款、与养老金阶段相关的免税收入、非公平交易收入(已按最高边际税率征税)以及通过合并养老金信托取得的收入等。

如基金已作出相关小型基金资本利得税选择,还需对部分资本利得进行相应调整。

在确定调整后的收益后,该收益将根据精算师计算的比例分配至各成员。随后,由澳大利亚税务局(ATO)依据这些数据对个人进行 Division 296 税额评估。

该税项由个人承担,而非由养老金基金直接缴纳。但纳税人可选择自行支付,或申请从其指定的养老金账户中扣除相应金额。

实务建议与规划重点

对于养老金余额接近或已超过相关门槛的个人,建议尽早咨询专业顾问,以评估 Division 296 带来的具体影响。这通常包括进行定制化测算、评估可适用的税务选择(如资本利得税相关选择),以及提前规划现金流与合规要求。

此外,该政策也为高净值人士提供了重新审视资产配置结构的契机,特别是对于超过门槛部分的资金,是否继续留在养老金体系内,或转向其他投资结构,需综合考虑税务效率与灵活性。

及早进行规划,将有助于更有效地应对 Division 296 带来的各项影响。

需要协助?

与我们这样的专业税务会计师和贷款经纪人合作,您可以放心,我们的团队可以提供针对性建议,确保贷款结构既能保护您的税务最大化扣除,同时避免错误的风险,从而让您更加安心,并更好地规划财务。

皮特马丁会计师事务所 Pitt Martin Group 是一家提供税务,会计,生意咨询,自管养老金,审计及贷款等综合性服务的经澳洲特许会计师协会认证的注册会计师事务所。我们每年会花上几百个小时去研究新的税法,以保证我们的客户可以最大化合理避税。我们的中文联系方式是 Robert Liu +61292213345 或邮件 info@pittmartingroup.com.au。皮特马丁会计师事务所Pitt Martin Group坐落在交通便利的悉尼市市中心,是一家拥有可以说中文合伙人的会计师事务所。我们的荣誉包括2018年CPA新州首席优秀奖, 2020年澳大利亚小生意年度冠军入围奖, 2021年澳洲知名媒体《每日会计师》年度最佳会计师事务所冠军入围奖,2022年最佳会计师事务所新人入围奖和2023香港澳大利亚商业协会最佳积极生意入围奖。

皮特马丁会计师事务所 Pitt Martin Group资质包括超过十五年的从业经验,澳大利亚与新西兰特许会计师协会(CAANZ)会员,澳大利亚注册会计师协会(CPA)执业认证会员,澳大利亚税务注册代理,新州、维州和西澳律师协会信托账户 (Trust Account) 认证审计师,澳大利亚金融贷款经纪人协会(FBAA)执业认证会员,澳大利亚证券及投资委员会注册代理,XERO, QUICKBOOKS, MYOB等会计软件授权单位及认证顾问。

本文内容仅供参考,不构成对任何个人或团体的具体情况而形成建议。任何个人或团体应该在征求专业人士的意见后方可采取行动。由于税法的时效性,我们在发布时已致力于提供及时、准确的信息,但不能保证所称述的内容在今后任然可以适用。转发该文内容请注明出处。

By Zoe Ma @ Pitt Martin Tax

Read more
Understanding the New Division 296 Tax on High Superannuation Balances

Understanding the New Division 296 Tax on High Superannuation Balances

The Australian Government’s “Better Targeted Superannuation Concessions” reform, commonly referred to as Division 296, has now been enacted and will commence from 1 July 2026. This measure introduces additional tax considerations for individuals with substantial superannuation balances. For affected taxpayers, it is essential to understand how the rules operate, the policy rationale behind them, and the planning implications moving forward.

Policy Intent Behind Division 296

The primary objective of Division 296 is to improve the equity and long-term sustainability of superannuation tax concessions. Rather than applying broad changes across the entire system, the legislation specifically targets individuals with significant super balances. In doing so, it seeks to ensure that higher-balance members pay an increased level of tax on earnings attributable to those balances.

Applicability: Thresholds and Tax Outcomes

From the 2026–27 income year onward, Division 296 applies where an individual’s total superannuation balance exceeds prescribed thresholds:

  • $3 million (large balance threshold)
  • $10 million (very large balance threshold)

These thresholds will be indexed over time. The effect of the new regime is an increase in the effective tax rate applied to earnings associated with balances above these limits:

  • Balances up to $3 million remain subject to the standard 15% tax rate within the fund
  • Earnings linked to balances between $3 million and $10 million will attract an additional 15% tax, bringing the effective rate to 30%
  • For balances exceeding $10 million, a further 25% tax applies, resulting in a combined effective rate of 40%

Certain individuals are excluded from the operation of Division 296 despite exceeding the thresholds. These include minors receiving death benefit pensions and individuals who have contributed structured settlement amounts arising from personal injury compensation.

In the event of death, an individual’s total superannuation balance ceases to exist. However, Division 296 may still apply for the income year in which death occurs (other than in the first year of implementation), provided the individual’s balance exceeded $3 million at the beginning of that year. As superannuation does not generally form part of the estate, this outcome highlights the importance of incorporating these rules into estate planning considerations.

Calculation and Assessment Mechanism

For self-managed superannuation funds (SMSFs), Division 296 earnings are determined based on taxable income, subject to a number of adjustments. These adjustments account for items such as concessional contributions included in assessable income, exempt pension income, non-arm’s length income (already taxed at the highest marginal rate), and income derived through pooled superannuation trusts.

Additional modifications may apply in relation to capital gains where the fund has elected to apply specific small-fund CGT provisions.

Once the adjusted earnings figure is established, it is allocated to individual members using an actuarially determined proportion. The Australian Taxation Office (ATO) then uses this information to calculate and issue the individual’s Division 296 tax liability.

Although the liability is imposed on the individual rather than the superannuation fund, payment flexibility is provided. Taxpayers may either settle the liability personally or elect to have the amount withdrawn from their nominated superannuation interest.

Practical Considerations and Planning Opportunities

Individuals approaching or exceeding the relevant thresholds should seek professional advice to assess the financial impact of Division 296. This may involve tailored projections, consideration of available elections (including capital gains tax options), and planning for cash flow and compliance requirements.

The introduction of this measure also presents an opportunity to reassess whether maintaining excess wealth within the superannuation environment remains optimal. Alternative investment structures may, in some cases, provide greater flexibility or tax efficiency for amounts above the applicable thresholds.

Early and proactive planning will be critical to managing the implications of Division 296 effectively.

Need Help?

By working with us as your professional tax accountant and mortgage broker, you can be confident that your loans are structured to protect your tax position, maximise deductions, and avoid costly mistakes, giving you greater peace of mind and more control over your financial future.

Pitt Martin Group is a firm of Chartered Accountants, providing services including taxation, accounting, business consulting, self-managed superannuation funds, auditing and mortgage & finance. We spend hundreds of hours each year on training and researching new tax laws to ensure our clients can maximize legitimate tax benefit. Our contact information are phone +61292213345 or email info@pittmartingroup.com.au. Pitt Martin Group is located in the convenient transportation hub of Sydney’s central business district. Our honours include the 2018 CPA NSW President’s Award for Excellence, the 2020 Australian Small Business Champion Award Finalist, the 2021 Australia’s well-known media ‘Accountants Daily’ the Accounting Firm of the Year Award Finalist and the 2022 Start-up Firm of the Year Award Finalist, and the 2023 Hong Kong-Australia Business Association Business Award Finalist.

Pitt Martin Group qualifications include over fifteen years of professional experience in accounting industry, membership certification of the Chartered Accountants Australia and New Zealand (CA ANZ), membership certification of the Australian Society of Certified Practising Accountants (CPA), Registered Australia Tax Agents, certified External Examiner of the Law Societies of New South Wales, Victoria, and Western Australia Law Trust Accounts, membership certification of the Finance Brokers Association of Australia Limited (FBAA), Registered Agents of the Australian Securities and Investments Commission (ASIC), certified Advisor of accounting software such as XERO, QUICKBOOKS, MYOB, etc.

This content is for reference only and does not constitute advice on any individual or group’s specific situation. Any individual or group should take action only after consulting with professionals. Due to the timeliness of tax laws, we have endeavoured to provide timely and accurate information at the time of publication, but cannot guarantee that the content stated will remain applicable in the future. Please indicate the source when forwarding this content.

By Zoe Ma @ Pitt Martin Tax

Read more
Understanding Capital Gains Tax on Your Home: Latest ATO Guidance for Home-Based Businesses

在家做生意,卖房要交多少税?ATO最新指引告诉你

越来越多的人选择在家开展业务,不管是自由职业、个体经营,还是小型生意,这种方式确实灵活又方便。但很多人忽略了一点,一旦涉及卖房,你的税务情况可能就没那么简单了。

澳大利亚税务局(ATO)近期对“居家经营”与“小企业资本利得税(CGT)优惠”的关系作出了更明确的说明,也澄清了一个长期以来容易被误解的问题。

更多详情请看:居家经营业务和CGT的影响|澳大利亚税务局

关键问题:活跃资产测试

一般来说,出售自住房可以享受CGT全额豁免,但如果房屋的一部分用于经营业务,这项豁免可能会受到影响。当无法享受全额豁免时,很多人会考虑其他优惠,例如持有超过12个月的50% CGT折扣,或者小企业CGT优惠政策。其中,小企业CGT优惠在符合条件的情况下,甚至可以大幅降低或免除CGT。

不过,这类优惠并不是自动适用的,其中最关键的条件之一是“活跃资产测试”。简单来说,你需要证明这套房产在持有期间内,有至少7.5年用于经营业务,或者至少一半的持有时间用于经营。

更重要的是,ATO是按整套房产来判断,而不是只看用于做生意的那一部分。也就是说,这个测试只有“通过”或“未通过”,不存在部分满足的情况。即使你在家中设有办公室、工作室,或者申报了居家办公相关费用,也不代表该房产就一定属于“活跃资产”。如果业务使用只是附带性质,占比较小,通常无法适用小企业CGT优惠。

判例说明:Rus v FCT

相关判例也支持这一观点。在Rus v FCT(2018)一案中,纳税人拥有一块约16公顷的土地,但只有不到10%的面积用于经营,包括家庭办公室和存放工具的仓库,且主要业务实际上是在外部进行。最终,税务局和法庭均认定该房产整体未能通过活跃资产测试,因为业务使用部分占比过低,且并未构成该资产的主要用途。这个案例也反映出ATO的一贯立场,即房产需要从整体角度评估,局部或附带的商业用途通常不足以改变结论。

实际案例说明

在实际操作中,不同情况的结果差异也很明显。通过以下两个常见情形,可以更直观地理解ATO的判断方式。

轻度居家经营:Donald在家中用一间空房经营美发业务,占房屋面积约7%,每周接待客户约8小时。在这种情况下,他可以申报部分居家经营相关费用,同时仍可享受约93%的自住房资本利得税免税。但由于业务使用比例较低,这种情况通常无法适用小企业CGT优惠,不过仍可以使用50%的CGT折扣。

较高比例商业用途:Janet和Frank拥有一栋两层房产,一楼约50%的面积用于经营外卖店,二楼作为自住房使用。该业务已经持续经营多年,并且配有员工。在这种情况下,该房产更有可能被认定为活跃资产,因此对于未被自住房免税覆盖的资本利得部分,有机会适用小企业CGT优惠。

需要注意的关键点

对于纳税人来说,有几个关键点需要特别注意。首先,部分自住房免税并不意味着可以自动适用小企业CGT优惠,单纯的居家办公或申报费用通常是不够的。其次,在决定在家中开展业务前,应提前考虑对税务的整体影响,包括费用扣除方式、CGT计算以及未来是否符合优惠条件。此外,建议保留完整的记录,例如房屋使用比例、业务时间以及相关费用凭证,这些资料在未来出售房产或接受税务审查时都非常重要。最后,如果有出售房产的计划,应尽早咨询专业会计师,以便全面评估潜在的CGT影响并合理规划。

总结

总体来看,ATO的最新指引传递了一个明确的信息,大多数在家开展小规模业务的业主,在出售自住房时并不能自动享受小企业CGT优惠。是否符合条件,取决于业务使用的比例、持续时间以及具体经营情况。因此,提前做好规划尤为重要。表面上看似增加的业务收入,未来可能会因为较高的资本利得税而被抵消。合理理解相关规则,有助于做出更明智的决策,也能让每一分收益更好地服务于未来的投资或长期财务目标。

需要协助?

与我们这样的专业税务会计师和贷款经纪人合作,您可以放心,我们的团队可以提供针对性建议,确保贷款结构既能保护您的税务最大化扣除,同时避免错误的风险,从而让您更加安心,并更好地规划财务。

皮特马丁会计师事务所 Pitt Martin Group 是一家提供税务,会计,生意咨询,自管养老金,审计及贷款等综合性服务的经澳洲特许会计师协会认证的注册会计师事务所。我们每年会花上几百个小时去研究新的税法,以保证我们的客户可以最大化合理避税。我们的中文联系方式是 Robert Liu +61292213345 或邮件 info@pittmartingroup.com.au。皮特马丁会计师事务所Pitt Martin Group坐落在交通便利的悉尼市市中心,是一家拥有可以说中文合伙人的会计师事务所。我们的荣誉包括2018年CPA新州首席优秀奖, 2020年澳大利亚小生意年度冠军入围奖, 2021年澳洲知名媒体《每日会计师》年度最佳会计师事务所冠军入围奖,2022年最佳会计师事务所新人入围奖和2023香港澳大利亚商业协会最佳积极生意入围奖。

皮特马丁会计师事务所 Pitt Martin Group资质包括超过十五年的从业经验,澳大利亚与新西兰特许会计师协会(CAANZ)会员,澳大利亚注册会计师协会(CPA)执业认证会员,澳大利亚税务注册代理,新州、维州和西澳律师协会信托账户 (Trust Account) 认证审计师,澳大利亚金融贷款经纪人协会(FBAA)执业认证会员,澳大利亚证券及投资委员会注册代理,XERO, QUICKBOOKS, MYOB等会计软件授权单位及认证顾问。

本文内容仅供参考,不构成对任何个人或团体的具体情况而形成建议。任何个人或团体应该在征求专业人士的意见后方可采取行动。由于税法的时效性,我们在发布时已致力于提供及时、准确的信息,但不能保证所称述的内容在今后任然可以适用。转发该文内容请注明出处。

By Zoe Ma @ Pitt Martin Tax

Read more
Understanding Capital Gains Tax on Your Home: Latest ATO Guidance for Home-Based Businesses

Understanding Capital Gains Tax on Your Home: Latest ATO Guidance for Home-Based Businesses

Operating a business from your home—whether as a freelancer, sole trader, or small business owner—offers undeniable convenience. Yet, when it comes to selling your property and minimising tax, the Australian Taxation Office (ATO) has recently clarified some important rules that may affect your plans.

The ATO has outlined its position on how home-based businesses interact with the small business capital gains tax (CGT) concessions. This guidance highlights an area that has long caused confusion among taxpayers.

More details are available here: Home-based business and CGT implications | Australian Taxation Office

The Core Concern: The Active Asset Test

Typically, the sale of your main residence qualifies for a full CGT exemption. However, if you use any portion of your home for business purposes, this could limit the exemption available.

Where the main residence rules do not provide a full exemption, other CGT concessions may apply. These include the CGT discount for assets held more than 12 months and the small business CGT concessions. The latter can potentially reduce—or even eliminate—the capital gain from selling your property, provided certain requirements are met.

One crucial condition is the active asset test. Broadly speaking, to meet this test, the property must have been actively employed in a business for at least 7.5 years of ownership, or for at least half of the ownership period.

The ATO is clear: the test applies to the entire property, not just the section used for business. An asset either satisfies the active asset test or it doesn’t; partial compliance isn’t recognised. Simply maintaining a home office, workshop, or claiming home occupancy deductions does not automatically qualify your home as an active asset. Where business activities are minor or incidental, the small business CGT concessions usually won’t apply.

Case Law: Rus v FCT

The principle that the whole property must qualify as an active asset, and that incidental business use is insufficient, is supported by the Administrative Appeals Tribunal (AAT) case Rus v FCT [2018] AATA 1854. In this instance, a taxpayer attempted to apply the small business CGT concessions on a largely vacant 16-hectare rural property. Less than 10% of the land was used for business—a home office, a shed for storing tools and vehicles, and supplies for a plastering and construction business. The remainder of the land remained vacant or residential.

The AAT upheld the ATO’s decision that the property did not meet the active asset test. The tribunal found that the business activities were not sufficiently integral to the overall property. Minor or incidental use does not render the entire property an active asset, particularly when the main business operations occur off-site. This case underscores the ATO’s strict approach: the property is assessed as a whole. Limited home-based business use is rarely enough to qualify for the small business CGT concessions.

Practical Scenarios

Minor home-based business: Donald operates a hairdressing salon in a spare room, occupying just 7% of her home and seeing clients eight hours per week. She claims occupancy deductions and receives a 93% main residence exemption. Despite this, her limited business use disqualifies her from the small business CGT concessions. The 50% CGT discount may still apply.

Substantial business use: Janet and Frank own a two-storey property where the ground floor runs a takeaway store (50% of total floor space) while the upper floor is their private residence. With decades of continuous business and employees, the property qualifies as an active asset. This opens potential access to small business CGT concessions for the portion of the capital gain not covered by the main residence exemption.

Key Takeaways

  • A partial main residence exemption does not automatically grant access to small business CGT concessions. Home office deductions or minor business use are not sufficient.
  • Consider your home-use plans carefully. Starting a home-based business can affect deductions, CGT calculations, and eligibility for concessions.
  • Maintain detailed records. Floor plans, hours of business use, and supporting documentation for deductions can strengthen your position for future planning or audits.
  • Consult your accountant. Professional advice is critical if selling your home is on the horizon, to assess CGT exposure and identify any concessions that may apply.

Conclusion

The ATO’s guidance makes it clear that many home-based business owners will not automatically qualify for small business CGT concessions when selling their home. Eligibility depends entirely on the specific facts and extent of business use.

Being proactive is essential. Understanding how your property is treated for CGT purposes allows you to make smarter decisions. For example, small business profits generated from your home could be significantly reduced if a higher CGT liability arises upon sale. Every dollar matters, whether it contributes to your next venture or your retirement savings.

Need Help?

By working with us as your professional tax accountant and mortgage broker, you can be confident that your loans are structured to protect your tax position, maximise deductions, and avoid costly mistakes, giving you greater peace of mind and more control over your financial future.

Pitt Martin Group is a firm of Chartered Accountants, providing services including taxation, accounting, business consulting, self-managed superannuation funds, auditing and mortgage & finance. We spend hundreds of hours each year on training and researching new tax laws to ensure our clients can maximize legitimate tax benefit. Our contact information are phone +61292213345 or email info@pittmartingroup.com.au. Pitt Martin Group is located in the convenient transportation hub of Sydney’s central business district. Our honours include the 2018 CPA NSW President’s Award for Excellence, the 2020 Australian Small Business Champion Award Finalist, the 2021 Australia’s well-known media ‘Accountants Daily’ the Accounting Firm of the Year Award Finalist and the 2022 Start-up Firm of the Year Award Finalist, and the 2023 Hong Kong-Australia Business Association Business Award Finalist.

Pitt Martin Group qualifications include over fifteen years of professional experience in accounting industry, membership certification of the Chartered Accountants Australia and New Zealand (CA ANZ), membership certification of the Australian Society of Certified Practising Accountants (CPA), Registered Australia Tax Agents, certified External Examiner of the Law Societies of New South Wales, Victoria, and Western Australia Law Trust Accounts, membership certification of the Finance Brokers Association of Australia Limited (FBAA), Registered Agents of the Australian Securities and Investments Commission (ASIC), certified Advisor of accounting software such as XERO, QUICKBOOKS, MYOB, etc.

This content is for reference only and does not constitute advice on any individual or group’s specific situation. Any individual or group should take action only after consulting with professionals. Due to the timeliness of tax laws, we have endeavoured to provide timely and accurate information at the time of publication, but cannot guarantee that the content stated will remain applicable in the future. Please indicate the source when forwarding this content.

By Zoe Ma @ Pitt Martin Tax

Read more
Holiday Homes and the ATO’s Sharpened Focus: What Property Owners Need to Know

ATO严查度假屋税务申报:业主需高度关注

对于许多澳大利亚家庭而言,海边小屋或滑雪公寓通常兼具两种用途。一方面,它是家人度假休闲的私人空间;另一方面,在自用以外的时间,会通过 Airbnb 或 Stayz 等平台对外出租,以补贴持有成本。

过去,不少业主普遍认为,只要对私人使用与出租用途进行合理分摊,大部分与出租物业相关的常规税务扣除都可以申报。然而,这种做法正面临改变。澳洲税务局(ATO)近期发布了多份税务裁定及合规指引文件,包括 TR 2025/D1、PCG 2025/D6 及 PCG 2025/D7,明确释放出将加强对“自用与出租混合型物业”合规监管的信号。

尽管上述文件仍处于草案阶段,但其监管方向已十分清晰,反映了未来 ATO 在审查度假房产扣除申报时的思路。

核心问题:投资性资产还是自用的生活型资产?

新指引的核心在于区分两类物业,一类是真正以商业化方式运营,目的是最大化租金回报的投资性资产;另一类则主要用于业主个人生活享受,出租仅属辅助或偶发行为。

ATO 再次强调,无论收入来源是短期住宿、零散预订,还是非正式安排,只要取得租金收入,都必须如实申报。

更值得关注的是费用扣除问题。如果某房产被认定为“度假自用房”,而非真正的收入性投资资产,ATO 可能会拒绝其大部分持有成本的税务抵扣,包括贷款利息、市政费和水费、土地税、保险费、维修与保养费用。

即便该物业在一年中的部分时间按市场价出租,上述费用仍有可能被否决。在这种情况下,业主可能仅能扣除与实际出租直接相关的费用,例如清洁费或广告费。

在判断物业是否具备商业运营性质时,ATO 会重点关注以下因素:

 • 是否在旺季期间保留给业主自用
 • 是否存在不连续或有限度的广告推广
 • 租金定价是否明显高于同类市场水平
 • 是否多年持续产生税务亏损

如果上述情况存在,ATO 可能认为出租只是附带性质,而非持有房产的主要目的。

费用分摊:必须“公平合理”

即便物业符合收入性资产的条件,只要存在私人使用与出租并存的情况,相关费用仍需进行合理分摊。

PCG 2025/D6 明确指出,分摊方式必须符合“公平合理”的原则。常见方法包括:

 • 按时间分摊,例如根据实际出租天数或真实可供出租天数计算
 • 按面积分摊,例如仅出租部分房间的情况下按面积比例计算

完善的记录至关重要。ATO 目前已可获取各大预订平台的数据,并能够核对广告刊登情况、可出租日历及申报收入。如未妥善保存证据,或采用过于激进的分摊方式,被审计的风险将显著上升。

潜在税务影响

其潜在的税务影响不容忽视。例如,一套度假公寓在淡季出租可获得每年 30,000 澳元租金收入,但在学校假期等旺季期间完全自用。按照新监管思路,ATO 可能认定该物业本质上属于私人度假用途,从而大幅限制贷款利息及其他持有成本的扣除金额。这可能导致应税收入增加数万澳元,从而使应缴税款大幅上升。

此外,产权结构也需谨慎安排。通常情况下,租金收入与可扣除费用须按照法律产权比例分配,而非依据谁使用得更多。若以低于市场价格出租给亲属,抵扣额度还可能会进一步受限。

新规实施前的建议措施

上述草案拟自 2026 年 7 月 1 日起适用。对于 2025 年 11 月 12 日之前已存在的安排,可能提供过渡性宽免。但建议业主不要等到正式生效才采取行动。

目前可考虑:

 第一,检视房产是否真正以最大化租金收益为目标进行商业化运营,包括旺季期间是否对外开放出租。
 第二,确保租金定价符合当地市场水平。
 第三,保留完整记录,包括预订日历、广告截图、客户咨询记录,以及清晰区分自用与出租天数的使用记录。
 第四,评估当前产权结构及运营模式是否具备商业合理性。如需调整,应同时考虑资本利得税、印花税及相关法律费用的影响。
 第五,如希望申请过渡性宽免安排,必须保留充分的书面证据。

总结

ATO 并未全面取消度假房产的税务抵扣,而是更加明确地区分真正的投资型物业与自用的生活型房产。

只要结构安排合理、运营方式具备商业实质,并且记录完整充分,许多业主仍然可以合法申报与收入相关的合理扣除,从而优化现金流。

如果您持有度假房产,现在正是进行税务审视与规划的良机。及早评估与调整,有助于避免未来出现不必要的税务风险与补税压力。

如需我们协助评估您目前的安排并制定应对策略,欢迎随时与我们联系。

需要协助?

与我们这样的专业税务会计师和贷款经纪人合作,您可以放心,我们的团队可以提供针对性建议,确保贷款结构既能保护您的税务最大化扣除,同时避免错误的风险,从而让您更加安心,并更好地规划财务。

皮特马丁会计师事务所 Pitt Martin Group 是一家提供税务,会计,生意咨询,自管养老金,审计及贷款等综合性服务的经澳洲特许会计师协会认证的注册会计师事务所。我们每年会花上几百个小时去研究新的税法,以保证我们的客户可以最大化合理避税。我们的中文联系方式是 Robert Liu +61292213345 或邮件 info@pittmartingroup.com.au。皮特马丁会计师事务所Pitt Martin Group坐落在交通便利的悉尼市市中心,是一家拥有可以说中文合伙人的会计师事务所。我们的荣誉包括2018年CPA新州首席优秀奖, 2020年澳大利亚小生意年度冠军入围奖, 2021年澳洲知名媒体《每日会计师》年度最佳会计师事务所冠军入围奖,2022年最佳会计师事务所新人入围奖和2023香港澳大利亚商业协会最佳积极生意入围奖。

皮特马丁会计师事务所 Pitt Martin Group资质包括超过十五年的从业经验,澳大利亚与新西兰特许会计师协会(CAANZ)会员,澳大利亚注册会计师协会(CPA)执业认证会员,澳大利亚税务注册代理,新州、维州和西澳律师协会信托账户 (Trust Account) 认证审计师,澳大利亚金融贷款经纪人协会(FBAA)执业认证会员,澳大利亚证券及投资委员会注册代理,XERO, QUICKBOOKS, MYOB等会计软件授权单位及认证顾问。

本文内容仅供参考,不构成对任何个人或团体的具体情况而形成建议。任何个人或团体应该在征求专业人士的意见后方可采取行动。由于税法的时效性,我们在发布时已致力于提供及时、准确的信息,但不能保证所称述的内容在今后任然可以适用。转发该文内容请注明出处。

By Zoe Ma @ Pitt Martin Tax

Read more