Skip to main content Skip to search

Posts by Nora Pham

Monthly PAYG instalments and business cash flow planning

Monthly PAYG Instalments: What Changes?

From 1 July 2027, more businesses and individuals paying PAYG instalments are expected to have the option of reporting and paying monthly instead of quarterly. The Australian Taxation Office (ATO) may also gain the power to require certain taxpayers to make monthly payments if they have a history of failing to meet their tax obligations.

Announced in the 2026-27 Federal Budget, these proposed changes are currently subject to draft legislation and are not yet law. However, they could affect how businesses manage their cash flow and tax obligations, making it worthwhile to understand the potential impact ahead of time.

What Are the Proposed Changes?

PAYG instalments are regular payments towards your expected annual income tax liability. They allow businesses and individuals to spread their tax payments throughout the year rather than facing a larger tax bill when their annual tax return is assessed.

Currently, most taxpayers in the PAYG instalment system pay quarterly, while certain larger taxpayers are already required to pay monthly.

Under the proposed changes, the following arrangements are expected to apply from 1 July 2027:

  • Monthly payments as an option: Most taxpayers already paying PAYG instalments could choose to report and pay monthly instead of quarterly.
  • Mandatory monthly payments for certain taxpayers: The ATO could require taxpayers with a demonstrated history of failing to meet their tax obligations to move to monthly payments.
  • Instalments that better reflect business performance: The changes form part of broader reforms designed to make tax instalments more responsive to current business performance, including through accounting software.

Monthly instalments would generally be due by the 21st of the following month, subject to the final rules.

For more information, visit the ATO’s guidance on dynamic PAYG instalments.

How Could Monthly Payments Affect Cash Flow?

For many businesses, the main consideration will be whether paying monthly makes cash-flow management easier or creates additional financial pressure.

Potential benefits

Smaller, more frequent payments may be easier to budget for than larger quarterly amounts. This could be particularly beneficial for businesses with steady monthly income, regular bookkeeping and established monthly reporting processes.

Paying monthly may also help businesses monitor their tax position more closely throughout the year. If instalments better reflect current earnings, there may be less risk of paying too much or too little during the year.

However, the actual benefits will depend on how the final rules operate and each taxpayer’s circumstances.

Potential drawbacks

On the other hand, monthly payments mean money leaves the business more frequently. This could reduce financial flexibility for businesses experiencing seasonal income, irregular customer payments or tight working capital.

More frequent reporting may also create additional administrative work, although accounting software could help automate parts of the process.

For businesses that rely on retaining cash between payment dates, quarterly payments may remain the more suitable option.

Ultimately, the right approach will depend on your income patterns, available cash reserves and existing accounting processes.

Who Could Be Required to Pay Monthly PAYG Instalments?

Businesses and individuals with a history of late lodgements, overdue tax debts or repeated failures to meet their tax obligations should pay particular attention to these proposed changes.

If the legislation becomes law, the ATO could require affected taxpayers to move to monthly PAYG instalments. This may create additional cash-flow pressure, particularly for businesses that are already experiencing financial difficulties.

However, these changes are not only relevant to taxpayers with compliance issues.

Taxpayers with a good compliance record may also consider voluntarily moving to monthly payments if doing so would make budgeting and tax management easier. Others may find that retaining their existing quarterly arrangements is more appropriate.

What should you do now to prepare for monthly PAYG instalments?

Although the proposed legislation has not been finalised, businesses can take several practical steps to prepare for the potential changes.

  1. Review your cash flow: Consider whether monthly payments would fit your income and expense patterns better than quarterly payments.
  2. Check your accounting processes: Assess whether your bookkeeping, reporting and banking arrangements can accommodate more frequent payments.
  3. Review your current PAYG instalments: Compare your existing instalments with your expected annual income tax liability. If you notice any significant differences, consider discussing them with your accountant.
  4. Address outstanding tax obligations: If you have overdue tax debts or a history of missed lodgement deadlines, seek professional advice early to manage your obligations and reduce the risk of further difficulties.

Monthly payments would change the timing of your tax payments, not your underlying tax liability. Planning ahead can help you avoid unexpected cash-flow pressure and choose an approach that suits your business.

We will provide further updates as the rules are finalised. In the meantime, contact us if you would like to review your current PAYG instalments or assess how monthly payments could affect your cash flow.

Frequently Asked Questions

Are monthly PAYG instalments law yet?

No. The changes were announced in the 2026–27 Federal Budget and are currently the subject of draft legislation. The proposed start date is 1 July 2027.

Will monthly PAYG instalments be compulsory?

Not for most taxpayers. Most taxpayers already paying PAYG instalments could choose to pay monthly. However, the ATO could require taxpayers with a demonstrated history of failing to meet their tax obligations to pay monthly.

When would monthly instalments be due?

Monthly instalments would generally be due by the 21st of the following month, subject to the final rules.

Will paying monthly change how much tax I pay?

No. Monthly payments would change the timing of your tax payments, not your underlying tax liability.

Need help?

If you are unsure whether monthly PAYG instalments would be suitable for your business, Pitt Martin Group can help you review your current tax instalments, assess the potential impact on your cash flow, and understand how the proposed changes may affect your tax obligations. We can also help you consider the most appropriate payment arrangement based on your business circumstances.

Pitt Martin Group is a firm of Chartered Accountants, providing services including taxation, accounting, business consulting, self-managed superannuation funds, auditing and mortgage & finance. We spend hundreds of hours each year on training and researching new tax laws to ensure our clients can maximize legitimate tax benefit. Our contact information are phone +61292213345 or email info@pittmartingroup.com.au. Pitt Martin Group, Sydney tax accountants, is located in the convenient transportation hub of Sydney’s central business district. Our honours include the 2018 CPA NSW President’s Award for Excellence, the 2020 Australian Small Business Champion Award Finalist, the 2021 Australia’s well-known media ‘Accountants Daily’ the Accounting Firm of the Year Award Finalist and the 2022 Start-up Firm of the Year Award Finalist, and the 2023 Hong Kong-Australia Business Association Business Award Finalist.

Pitt Martin Group qualifications include over fifteen years of professional experience in accounting industry, Registered Australia Tax Agents, membership certification of the Chartered Accountants Australia and New Zealand (CA ANZ), certified External Examiner of the Law Societies of New South Wales, Victoria, and Western Australia Law Trust Accounts, membership certification of the Finance Brokers Association of Australia Limited (FBAA), Registered Agents of the Australian Securities and Investments Commission (ASIC), certified Advisor of accounting software such as XERO, QUICKBOOKS, MYOB, etc.

This content is for reference only and does not constitute advice on any individual or group’s specific situation. Any individual or group should take action only after consulting with professionals. Due to the timeliness of tax laws, we have endeavoured to provide timely and accurate information at the time of publication, but cannot guarantee that the content stated will remain applicable in the future. Please indicate the source when forwarding this content.

By Nora Pham @ Pitt Martin Tax

Read more
Lost Super: $21 Billion Waiting

Lost Super: $21 Billion Unclaimed

More than $21 billion in lost super and unclaimed superannuation is currently waiting across Australia, according to the ATO figures cited in the original article. The average lost account holds around $41,000, and the ATO reunited more than $1.1 billion with members last year.

That money could be contributing to your retirement savings instead of sitting in a forgotten account. Checking for lost super is free, usually takes only a few minutes, and tax time can be a useful opportunity to review where your super is held.

How does lost super happen?

Lost super generally occurs when a super account becomes inactive and the fund can no longer contact the member. This can happen for several common reasons, including:

  • Changing jobs and leaving an old super account behind
  • Moving house without updating your address with the fund
  • Changing your phone number or contact details
  • Changing your name and not notifying the fund

When a fund cannot contact you, the account may eventually be classified as lost. In some cases, the balance is transferred to the ATO, which holds the money until it can be reunited with its rightful owner.

The important point is that lost super does not simply disappear. It may still be waiting for you to claim it.

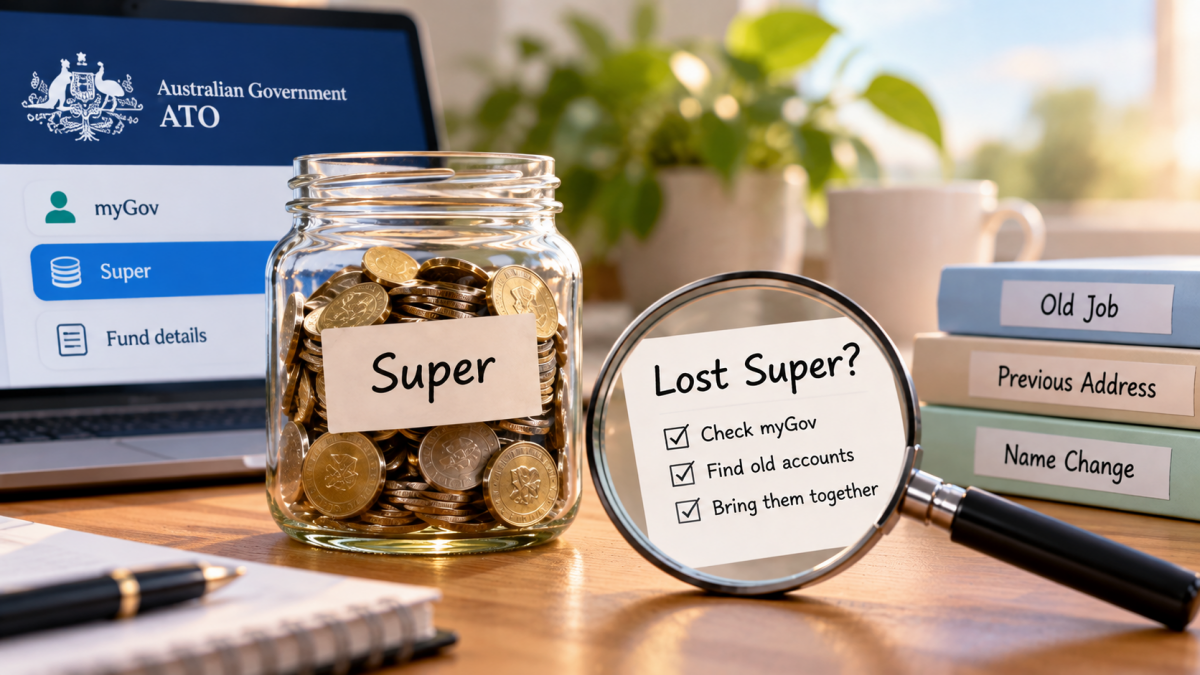
How to find lost super through myGov

Finding lost super is straightforward and free. One of the quickest ways is through ATO online services linked to myGov.

  1. Log in to myGov and open the ATO service.
  2. Select Super, then Fund details.
  3. Review your active super accounts and any lost or ATO-held super linked to your tax file number.

You may also be able to search through the ATO app, use the automated lost super search service on 13 28 65, or complete a paper form.

Old accounts can easily be forgotten, particularly after changing jobs several times. Even a small balance from an early job may have grown over time.

Why it matters near retirement

Finding lost super can be valuable at any age, but it may be especially important if you are approaching retirement.

An additional $20,000, $40,000 or more could make a noticeable difference to the amount available in your retirement nest egg. Smaller balances may also continue to grow once they are brought together in an active account that earns investment returns and receives future contributions.

Consolidating super may also make your retirement savings easier to monitor and can help reduce unnecessary duplicated fees.

Check your insurance before consolidating

Before rolling several super accounts into one fund, check whether any of your existing accounts include insurance cover.

Super accounts can include death, total and permanent disability, or income protection insurance. In some circumstances, that cover may end when the account balance is rolled into another fund.

Losing insurance without realising it could leave an unexpected gap in your protection. Before consolidating, check with your super fund or adviser so you understand what cover may stop, continue or change.

Why checking your super is worthwhile

Money held in a lost or low-balance account may be earning less than it could or attracting unnecessary fees. Bringing your super together can make it easier to track your overall position, reduce duplicated costs and review your investment options.

The ATO reunification figures show that meaningful amounts are regularly returned to members who search for lost super.

With more than $21 billion waiting to be claimed, checking whether you have lost or ATO-held super could be well worth a few minutes.

You can start a free search through the ATO’s lost superannuation service:

https://www.ato.gov.au/forms-and-instructions/superannuation-searching-for-lost-superannuation

Need professional tax assistance?

If you are unsure whether you have lost or ATO-held super, or whether consolidating multiple super accounts is right for you, Pitt Martin Group can help you review your super position, understand the potential impact on fees and insurance cover, and consider the next steps based on your circumstances.

Pitt Martin Group is a firm of Chartered Accountants, providing services including taxation, accounting, business consulting, self-managed superannuation funds, auditing and mortgage & finance. We spend hundreds of hours each year on training and researching new tax laws to ensure our clients can maximize legitimate tax benefit. Our contact information are phone +61292213345 or email info@pittmartingroup.com.au. Pitt Martin Group, Sydney tax accountants, is located in the convenient transportation hub of Sydney’s central business district. Our honours include the 2018 CPA NSW President’s Award for Excellence, the 2020 Australian Small Business Champion Award Finalist, the 2021 Australia’s well-known media ‘Accountants Daily’ the Accounting Firm of the Year Award Finalist and the 2022 Start-up Firm of the Year Award Finalist, and the 2023 Hong Kong-Australia Business Association Business Award Finalist.

Pitt Martin Group qualifications include over fifteen years of professional experience in accounting industry, Registered Australia Tax Agents, membership certification of the Chartered Accountants Australia and New Zealand (CA ANZ), certified External Examiner of the Law Societies of New South Wales, Victoria, and Western Australia Law Trust Accounts, membership certification of the Finance Brokers Association of Australia Limited (FBAA), Registered Agents of the Australian Securities and Investments Commission (ASIC), certified Advisor of accounting software such as XERO, QUICKBOOKS, MYOB, etc.

This content is for reference only and does not constitute advice on any individual or group’s specific situation. Any individual or group should take action only after consulting with professionals. Due to the timeliness of tax laws, we have endeavoured to provide timely and accurate information at the time of publication, but cannot guarantee that the content stated will remain applicable in the future. Please indicate the source when forwarding this content.

By Nora Pham @ Pitt Martin Tax
Read more
Work-Related Computer Deductions: What the Hartley Case Means for Taxpayers

Work-Related Computer Deductions: What the Hartley Case Means for Taxpayers

A recent Tribunal decision highlights an important point for taxpayers claiming work-related computer deductions: using computer equipment for activities that benefit your employer does not automatically mean the related expenses are tax deductible.

Work-Related Computer Deductions: What Happened?

A recent Tribunal decision highlights an important issue for employees claiming work-related computer deductions: computer equipment and technology expenses are not automatically deductible simply because the activities benefit an employer.

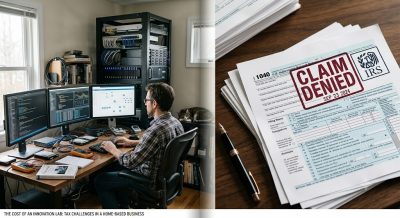
In Hartley and Commissioner of Taxation [2026] ARTA 1590, the Tribunal considered whether a senior IT sales employee could claim substantial deductions for a home computer “lab”. Although the employee demonstrated that several projects undertaken at home were encouraged by and benefited his employer, the Tribunal ultimately denied the deductions in full.

The decision is a useful reminder that the connection between an expense and an employee’s actual income-earning duties is critical when determining whether a work-related deduction is available.

What Were the Work-Related Computer Deductions?

Mr Hartley was employed by Ericsson Australia as a Domain Sales Manager. He argued that his employment involved responsibilities beyond traditional sales activities. According to his evidence, his role also involved innovation, identifying new product opportunities and providing thought leadership within the industry.

During the 2022 income year, Mr Hartley claimed a substantial amount of work-related and capital allowance deductions associated with his home computer “lab”.

The total amount ultimately disputed before the Tribunal was $31,870. Most of the claim related to technology and computing expenses, including:

  • Digital storage devices
  • Computers
  • Computer monitors
  • Computer software
  • Subscriptions to various computing services

The ATO denied the claims during its audit of Mr Hartley’s tax affairs. The taxpayer subsequently objected to the decision, but the deductions remained denied. The matter was then considered by the Tribunal.

The size and nature of the claim made the case particularly relevant for taxpayers who incur significant technology costs in connection with their employment.

The computer activities benefited the employer

Mr Hartley provided evidence of several projects undertaken using his home computer lab. These included:

  • A network virtualisation project that was later developed and marketed by Ericsson;
  • Cloud infrastructure work undertaken through an industry collaboration involving Ericsson; and
  • Work on video interface technology that was featured in an Ericsson press release and later deployed in the business.

The Tribunal accepted that Mr Hartley had specialised expertise and that his senior role involved contributing to the development of marketable technologies.

However, this was not enough to establish that the expenses were deductible.

Why were the work-related computer deductions denied?

Despite that, the Tribunal denied the deductions in full. The reasoning turned on whose purpose the expenditure served:

  1. The activities weren’t required by the role. Ericsson neither mandated the work nor permitted Mr. Hartley to use company equipment to perform it.
  2. The taxpayer stood to keep the benefit. Evidence suggested the work was done at home partly so Mr. Hartley could retain ownership of any development if he left Ericsson.
  3. General professional interest isn’t enough. The Tribunal found the activities were closer to maintaining general professional standing and personal interest in IT than to discharging his actual employment duties.

Citing the High Court’s decision in Federal Commissioner of Taxation v Hatchett [1971] HCA 47, the Tribunal confirmed that employer encouragement of an activity without more does not convert it into a deductible work expense.

What Does the Hartley Case Mean for Work-Related Computer Deductions?

The ATO has repeatedly flagged work-related deductions as a compliance priority, and large or unusual claims attract particular scrutiny. Hartley is a useful reminder of where the line sits:

For businesses and taxpayers, it is not enough to demonstrate that:

  • the equipment is used at home;
  • the employer is aware of or encourages the activity;
  • the employer benefits from the work; or
  • the taxpayer uses the equipment to develop professional skills or maintain industry knowledge.

The nature of the taxpayer’s actual employment duties and the purpose for which the expenditure was incurred remain important considerations.

This is particularly relevant where an employee is claiming significant amounts for computers, monitors, storage equipment, software or online computing services.

Key takeaway for taxpayers

Before claiming a work-related computer deduction, taxpayers should consider whether the expense genuinely relates to their current income-producing duties rather than broader professional interests or personal projects.

The Hartley decision demonstrates that even substantial work that ultimately benefits an employer may not qualify for a deduction if it falls outside the employee’s actual employment responsibilities.

For significant claims, businesses and employees should retain appropriate records and carefully consider the connection between the expense, the employment duties and the income being earned.

Frequently Asked Questions

What was the outcome of Hartley and Commissioner of Taxation [2026] ARTA 1590?

The Administrative Review Tribunal upheld the ATO’s decision to deny Mr Hartley’s $31,870 claim for home computer “lab” expenses, finding the costs were not sufficiently connected to his actual employment duties.

Does employer encouragement make a work-related expense deductible?

No. The Tribunal confirmed that an employer encouraging or benefiting from an activity is not, on its own, enough to support a deduction. The expense must relate to the performance of the employee’s specific duties.

What case law did the Tribunal rely on?

The Tribunal cited Federal Commissioner of Taxation v Hatchett [1971] HCA 47, a longstanding authority on the limits of deductibility for self-education and work-related expenditure.

What should you take from this decision?

Before claiming large work-related deductions, test whether the expense was actually required to perform the client’s job not merely useful, encouraged, or professionally beneficial. Also consider who ultimately retains the benefit of any work product created.

Is the computer use directly connected to your employment duties?

A general professional interest may not be enough.

Need Help?

If you are unsure whether your computer, technology or other work-related expenses are deductible, Pitt Martin Group can help you assess the connection between the expense and your income-earning activities, determine any required apportionment, and understand the record-keeping requirements.

As Sydney tax accountants, we assist individuals and businesses with work-related deductions, tax compliance and practical tax advice.

Pitt Martin Group is a firm of Chartered Accountants, providing services including taxation, accounting, business consulting, self-managed superannuation funds, auditing and mortgage & finance. We spend hundreds of hours each year on training and researching new tax laws to ensure our clients can maximize legitimate tax benefit. Our contact information are phone +61292213345 or email info@pittmartingroup.com.au. Pitt Martin Group, Sydney tax accountants, is located in the convenient transportation hub of Sydney’s central business district. Our honours include the 2018 CPA NSW President’s Award for Excellence, the 2020 Australian Small Business Champion Award Finalist, the 2021 Australia’s well-known media ‘Accountants Daily’ the Accounting Firm of the Year Award Finalist and the 2022 Start-up Firm of the Year Award Finalist, and the 2023 Hong Kong-Australia Business Association Business Award Finalist.

Pitt Martin Group qualifications include over fifteen years of professional experience in accounting industry, Registered Australia Tax Agents, membership certification of the Chartered Accountants Australia and New Zealand (CA ANZ), certified External Examiner of the Law Societies of New South Wales, Victoria, and Western Australia Law Trust Accounts, membership certification of the Finance Brokers Association of Australia Limited (FBAA), Registered Agents of the Australian Securities and Investments Commission (ASIC), certified Advisor of accounting software such as XERO, QUICKBOOKS, MYOB, etc.

This content is for reference only and does not constitute advice on any individual or group’s specific situation. Any individual or group should take action only after consulting with professionals. Due to the timeliness of tax laws, we have endeavoured to provide timely and accurate information at the time of publication, but cannot guarantee that the content stated will remain applicable in the future. Please indicate the source when forwarding this content.

By Nora Pham @ Pitt Martin Tax
Read more
Navigating the 2026–27 Car Thresholds

Navigating the 2026 – 2027 Car Thresholds: What Every Australian Business Needs to Know

If your business is planning to buy or lease a vehicle in the new financial year, the updated 2026–27 car thresholds from the Australian Taxation Office (ATO) are worth a look before you sign anything. They shape three things that matter to your bottom line: depreciation, GST recovery, and whether Luxury Car Tax (LCT) applies.

For vehicles first used or leased from 1 July 2026, the car limit, GST credit cap, and LCT thresholds have all increased with indexation. Understanding how they interact can help you time a purchase and avoid surprises at tax time.

The Car Limit: The Depreciation Cap

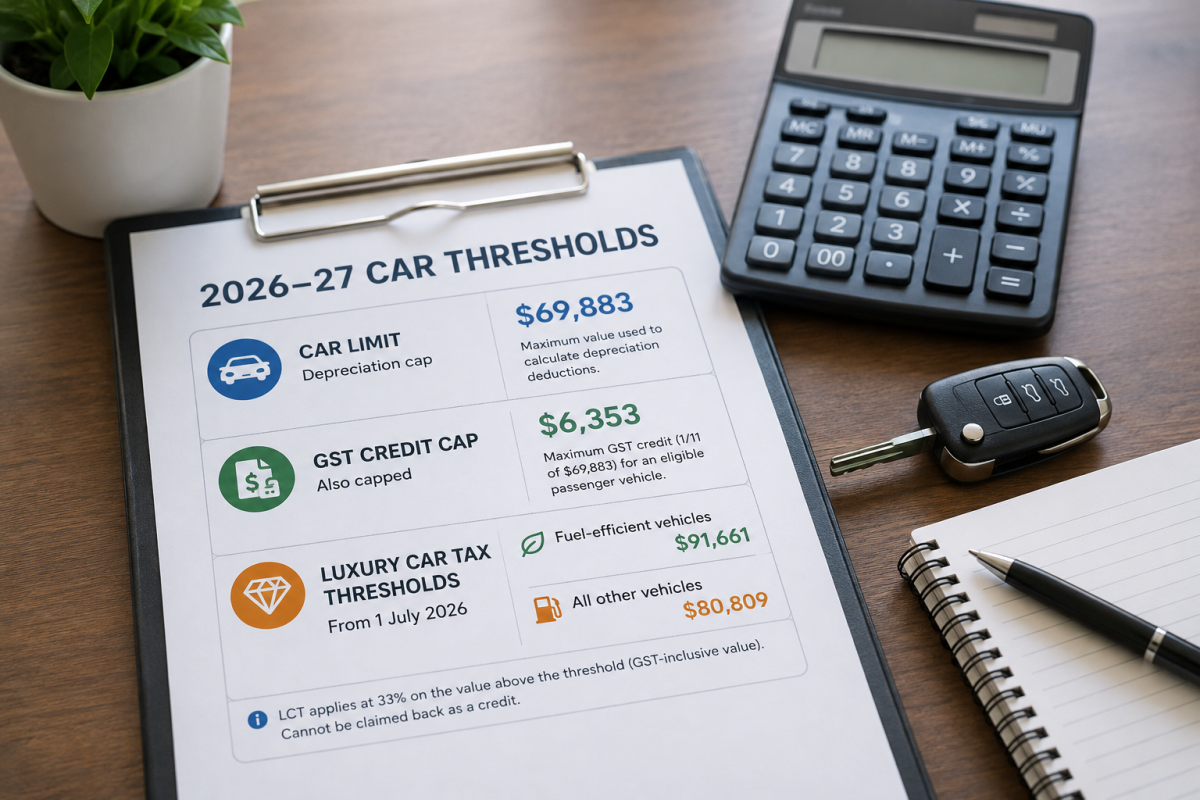
For 2026–27, the ATO car limit is $69,883, the maximum value used to calculate depreciation deductions for a passenger vehicle, regardless of actual purchase price. Buy above this and the excess generally cannot be depreciated. There may be good commercial reasons to buy something pricier, but beyond the car limit, extra spend typically produces no additional tax benefit.

A few points worth noting:

  • Mixed use: If a vehicle is used for both business and private purposes, you can only claim the business-use portion. A valid logbook, kept for a continuous 12-week period with odometer readings, is essential evidence if the ATO reviews your claim.
  • Depreciation method: Businesses may be eligible for simplified small business depreciation rules, allowing accelerated deductions. Confirm eligibility with your tax agent before purchase.
  • Timing: The applicable car limit is set by the income year the car is first used or held ready for use, not the invoice date. This matters if delivery slips past 1 July.

GST Credits: Also Capped

Businesses registered for GST can generally claim GST credits on vehicles bought for business use, but this is also capped by reference to the car limit. Once the price exceeds the limit, the credit is capped at one-eleventh of the limit, not one-eleventh of the actual price.

For 2026–27, the maximum GST credit on an eligible passenger vehicle is $6,353 (one-eleventh of $69,883), regardless of actual cost, and this applies to fuel-efficient and non-fuel-efficient vehicles alike.

Some flow-on consequences:

  • Selling later: GST is generally payable on the full sale price when the vehicle is sold, even though the credit claimed at purchase was capped. This asymmetry can catch owners off guard.
  • BAS reporting: Only the car-limit amount (or its business-use proportion) is reported at label G10, with the capped credit at label 1B.
  • Time limits: GST credits must generally be claimed within four years, so reconcile purchases promptly.
  • Cash flow: The credit is often a meaningful short-term benefit, worth weighing against financing or leasing.

Luxury Car Tax Thresholds Rise From 1 July 2026

Luxury car tax rate and thresholds (LCT) is a separate consideration, with its own thresholds, also increased for 2026–27:

  • $91,661 for fuel-efficient vehicles
  • $80,809 for all other vehicles

Where the GST-inclusive value exceeds the relevant threshold, LCT generally applies at 33% on the value above it. Unlike GST, LCT cannot be claimed back as a credit, even for vehicles used entirely for business.

The gap between the two thresholds is increasingly relevant: more hybrid, plug-in hybrid and electric models now qualify for the higher threshold, reducing LCT versus an equivalent petrol or diesel model. This is worth weighing for fleets or client-facing vehicles. Check the current ATO definition before assuming a model qualifies, as the eligibility test has tightened in recent years.

Planning Ahead

Since these thresholds apply to any vehicle first used or leased from 1 July 2026, now is a good time to review planned purchases. Before committing, work through:

  • Total after-tax cost of ownership: depreciation, GST credits, LCT, financing, insurance and running costs, not just the drive-away price.
  • Buy versus lease: Outright purchase, chattel mortgage, novated leasing and operating leases each carry different depreciation, GST and cash flow implications, depending on turnover, cash position and vehicle use.
  • Business-use percentage: the records needed to support it, including a logbook, odometer readings, and trip diary where relevant.
  • Cash flow timing: whether to bring a purchase forward before 30 June or defer until after 1 July.

Key Takeaways

A business vehicle can be a significant investment. While tax considerations should not be the sole factor in your decision, they can play an important role in determining the overall cost of ownership.

Before making a purchase, it is worth speaking with your accountant to assess the potential tax implications based on your individual circumstances. Planning ahead can help you make the most of available tax concessions, avoid unexpected costs and ensure the purchase supports your broader business strategy.

For more information, refer to the ATO’s Small Business Newsroom: Car thresholds from 1 July | Australian Taxation Office, or contact our team to discuss how these changes may apply to your business.

Need Help?

By working with us as your professional tax accountant and mortgage broker, you can be confident that your loans are structured to protect your tax position, maximise deductions, and avoid costly mistakes, giving you greater peace of mind and more control over your financial future.

Pitt Martin Group is a firm of Chartered Accountants, providing services including taxation, accounting, business consulting, self-managed superannuation funds, auditing and mortgage & finance. We spend hundreds of hours each year on training and researching new tax laws to ensure our clients can maximize legitimate tax benefit. Our contact information are phone +61292213345 or email info@pittmartingroup.com.au. Pitt Martin Group is located in the convenient transportation hub of Sydney’s central business district. Our honours include the 2018 CPA NSW President’s Award for Excellence, the 2020 Australian Small Business Champion Award Finalist, the 2021 Australia’s well-known media ‘Accountants Daily’ the Accounting Firm of the Year Award Finalist and the 2022 Start-up Firm of the Year Award Finalist, and the 2023 Hong Kong-Australia Business Association Business Award Finalist.

Pitt Martin Group qualifications include over fifteen years of professional experience in accounting industry, Registered Australia Tax Agents, membership certification of the Chartered Accountants Australia and New Zealand (CA ANZ), certified External Examiner of the Law Societies of New South Wales, Victoria, and Western Australia Law Trust Accounts, membership certification of the Finance Brokers Association of Australia Limited (FBAA), Registered Agents of the Australian Securities and Investments Commission (ASIC), certified Advisor of accounting software such as XERO, QUICKBOOKS, MYOB, etc.

This content is for reference only and does not constitute advice on any individual or group’s specific situation. Any individual or group should take action only after consulting with professionals. Due to the timeliness of tax laws, we have endeavoured to provide timely and accurate information at the time of publication, but cannot guarantee that the content stated will remain applicable in the future. Please indicate the source when forwarding this content.

By Nora Pham @ Pitt Martin Tax
Read more
Ending card surcharges: What you need to know before 1 October 2026

Card Surcharge Ban: What Australian Businesses Need to Know

The card surcharge ban took effect across Australia on 1 October 2026. Under the Reserve Bank of Australia (RBA) reform, businesses can no longer add surcharges to credit and debit card payments made through eftpos, Visa and Mastercard.

For many businesses, card surcharges have become a common way to recover merchant payment costs. However, these new regulations aim to simplify pricing, improve transparency, and reduce payment costs across the economy.

If your business currently applies card surcharges, now is the time to start preparing.

Why Did the RBA Introduce the Card Surcharge Ban?

According to the RBA, Australian consumers pay approximately $1.6 billion annually in card surcharges. At the same time, businesses incur even greater costs when accepting electronic payments.

The reform package is designed to:

  • Eliminate unexpected checkout fees for consumers
  • Reduce overall payment processing costs for businesses
  • Improve transparency in the payments industry
  • Encourage competition among payment providers
  • Create a simpler and fairer pricing system

The RBA estimates that merchant payment costs could fall by approximately $910 million per year, with small businesses expected to benefit the most.

What Is Changing From 1 October 2026?

The new payment reforms consist of three key changes.

1. Card Surcharges Will Be Banned

From 1 October 2026, businesses will no longer be permitted to charge additional fees for payments made using:

  • eftpos
  • Visa
  • Mastercard
  • Related payment networks

This applies whether customers pay:

  • In-store
  • Online
  • Through mobile wallets
  • Via integrated payment systems

Customers must see a single final price without additional card payment charges being added at checkout.

2. Lower Interchange Fees

Interchange fees are wholesale charges exchanged between financial institutions when card payments are processed.

Under the new reforms:

  • Existing fee caps will be reduced
  • New limits will apply to foreign-issued cards
  • Payment acceptance costs should decrease for merchants

Lower interchange fees are expected to reduce the overall cost of accepting card payments, helping businesses offset the loss of surcharge revenue.

3. Increased Fee Transparency

Banks, payment providers, and card schemes will be required to provide clearer information regarding:

  • Merchant service fees
  • Processing costs
  • Fee structures
  • Provider margins

Payment providers must also demonstrate how wholesale fee reductions are being passed on to businesses.

This increased transparency should make it easier for business owners to compare providers, negotiate better rates, and make informed decisions about their payment systems.

The reforms will be supported by oversight from the Australian Competition and Consumer Commission (ACCC) and guidance from the Australian Small Business and Family Enterprise Ombudsman.

How Businesses Should Respond to the Card Surcharge Ban

Although the changes do not take effect until October 2026, businesses should begin reviewing their payment arrangements well in advance.

Review Your Merchant Fees

Start by examining your merchant statements and identifying:

  • Current card acceptance costs
  • Monthly processing fees
  • Revenue generated from surcharges
  • The overall impact on business margins

If surcharges currently help offset payment processing costs, you may need to review your pricing strategy to maintain profitability.

Speak With Your Payment Provider

The upcoming reforms create an opportunity to revisit your arrangements with your payment provider. As interchange fees are expected to decrease and fee transparency increases, businesses may be able to negotiate lower merchant service fees, more competitive pricing plans, or upgraded payment technology. Small businesses, which often pay higher effective processing rates, may stand to benefit the most from these discussions.

Update Your Pricing and POS Systems

Before the implementation date, businesses will need to remove:

  • Card surcharge notices
  • Checkout surcharge settings
  • Automatic percentage-based fees
  • Separate payment processing charges

All displayed prices must become fully inclusive.

Review both physical and online sales channels to ensure compliance with the new requirements.

Factor the Changes Into Cash Flow Planning

While lower merchant costs may not be immediate, many businesses are expected to experience savings during the 2026–27 financial year.

Industries that process large volumes of small transactions may see the greatest impact, including:

  • Cafés
  • Restaurants
  • Retail stores
  • Trade businesses
  • Service-based businesses

Now is a good time to update budgets and financial forecasts to account for the expected changes.

Monitor Customer Payment Behaviour

The removal of surcharges may encourage more customers to choose card payments rather than cash. This could improve convenience, speed up transactions, and reduce the need for cash handling. However, businesses should continue monitoring their payment costs as customer behavior changes to ensure any increase in card usage does not offset the savings generated by lower merchant fees.

How the Card Surcharge Ban Affects Australian Businesses

Ultimately, this reform creates a more level playing field across the Australian economy. 

For businesses that never charged a surcharge will immediately benefit from lower underlying merchant fees, boosting your profitability. 

For businesses that did charge a surcharge will enjoy far simpler daily operations, less administrative friction, and zero compliance risks. 

Over time, this regulatory shakeup is expected to drive intense competition among payment providers, paving the way for superior financial products and even lower fees across the market. While banks may adjust secondary features like credit card rewards programs to offset their losses, the combined effort of the RBA and ACCC ensures savings are distributed fairly to businesses and consumers alike.

Final Thoughts

The end of card surcharges represents one of the most significant payment reforms in Australia in recent years.

For consumers, it means simpler pricing and fewer surprises at checkout. For businesses, it presents an opportunity to reduce complexity, improve operational efficiency, and potentially lower payment costs.

The key is preparation. Reviewing your payment arrangements now can help ensure a smooth transition before the 1 October 2026 deadline.

If you are unsure how these changes may affect your business, professional advice can help you assess merchant fees, evaluate pricing strategies, and identify opportunities to reduce costs before the new rules take effect.

Need Help?

By working with us as your professional tax accountant and mortgage broker, you can be confident that your loans are structured to protect your tax position, maximise deductions, and avoid costly mistakes, giving you greater peace of mind and more control over your financial future.

Pitt Martin Group is a firm of Chartered Accountants, providing services including taxation, accounting, business consulting, self-managed superannuation funds, auditing and mortgage & finance. We spend hundreds of hours each year on training and researching new tax laws to ensure our clients can maximize legitimate tax benefit. Our contact information are phone +61292213345 or email info@pittmartingroup.com.au. Pitt Martin Group is located in the convenient transportation hub of Sydney’s central business district. Our honours include the 2018 CPA NSW President’s Award for Excellence, the 2020 Australian Small Business Champion Award Finalist, the 2021 Australia’s well-known media ‘Accountants Daily’ the Accounting Firm of the Year Award Finalist and the 2022 Start-up Firm of the Year Award Finalist, and the 2023 Hong Kong-Australia Business Association Business Award Finalist.

Pitt Martin Group qualifications include over fifteen years of professional experience in accounting industry, Registered Australia Tax Agents, membership certification of the Chartered Accountants Australia and New Zealand (CA ANZ), certified External Examiner of the Law Societies of New South Wales, Victoria, and Western Australia Law Trust Accounts, membership certification of the Finance Brokers Association of Australia Limited (FBAA), Registered Agents of the Australian Securities and Investments Commission (ASIC), certified Advisor of accounting software such as XERO, QUICKBOOKS, MYOB, etc.

This content is for reference only and does not constitute advice on any individual or group’s specific situation. Any individual or group should take action only after consulting with professionals. Due to the timeliness of tax laws, we have endeavoured to provide timely and accurate information at the time of publication, but cannot guarantee that the content stated will remain applicable in the future. Please indicate the source when forwarding this content.

By Nora Pham @ Pitt Martin Tax
Read more
Payday Super Has Arrived – What Employers Need to Know

Payday Super Is Here: New rules starting 1 July 2026

From 1 July 2026, one of the biggest reforms to Australia’s superannuation system has officially taken effect. Under the new Payday Super rules, employers must ensure that superannuation contributions are received by employees’ super funds within seven business days of each payday.

This marks a significant shift from the previous quarterly payment system. While the reform aims to improve retirement outcomes for employees by ensuring super is paid sooner, it also introduces new payroll, cash flow and compliance obligations for businesses.

Whether you’re a small business owner or a larger employer, understanding the new requirements is essential to avoid penalties and maintain compliance.

What Is Payday Super?

Under the previous rules, employers generally had until 28 days after the end of each quarter to make super contributions. Under the new Payday Super system, the clock starts on each “Qualifying Earnings” (QE) day – which is essentially your payday for salary, wages, commissions, bonuses, and certain contractor payments.

Key Payday Super Requirements

  • Strict 7-Day Window: Contributions must be received and allocated to the employee’s fund within 7 business days of payday (with very limited exceptions).
  • Per-Payday Calculations: Shortfalls are now calculated per QE day rather than quarterly.
  • Clearing House Updates: The ATO’s Small Business Superannuation Clearing House has officially closed. Businesses previously using this service must now transition to a SuperStream-compliant alternative.

Penalties for Non-Compliance

The Australian Taxation Office (ATO) has introduced stronger enforcement measures under Payday Super.

Employers who fail to meet their obligations may face:

  • Superannuation Guarantee Charge (SGC) liabilities
  • Administrative penalties of up to 60% of the super shortfall
  • Additional interest and compliance costs

However, employers who voluntarily disclose mistakes early and take prompt corrective action may be eligible for reduced penalties.

During the first year of implementation, the ATO’s compliance approach under PCG 2026/1 focuses on businesses that make genuine efforts to comply. Employers who actively address issues are generally considered lower risk, although employee complaints will still be investigated.

The June – July 2026 Transition: A Common Compliance Trap

Many employers may overlook an important transitional issue when moving from the quarterly system to Payday Super.

If your business paid employees during the June 2026 quarter, the Super Guarantee deadline for that quarter remains 28 July 2026. However, any super contributions made after 1 July 2026 will first be allocated to outstanding June quarter obligations before being applied to Payday Super requirements for July payroll.

Without careful planning, businesses could unintentionally create Superannuation Guarantee Charge (SGC) liabilities despite making payments on time.

The appropriate strategy depends on your payroll schedule and the timing of July pay runs, making it worthwhile to review your payment timetable carefully.

Three Practical Steps to Prepare for Payday Super

1. Review Your Payroll Systems

Confirm that your payroll software, clearing house and internal processes are fully compatible with the new Payday Super requirements.

Check that:

  • Qualifying Earnings are correctly identified
  • Super calculations are accurate
  • SuperStream integration is functioning correctly
  • Payment workflows are automated where possible

2. Assess Cash Flow Impacts

Moving from quarterly to more frequent super payments will affect business cash flow.

Consider reviewing:

  • Payroll funding processes
  • Approval workflows
  • Bonus and commission payment procedures
  • Out-of-cycle payroll processes

Planning ahead can help minimise cash flow pressure while ensuring compliance.

3. Strengthen Internal Controls

Payroll and finance teams should clearly understand the new obligations.

Regular reviews of payroll reports, contribution records and payment confirmations can help identify issues early before they become costly compliance problems

Why Businesses Should Act Now

Payday Super isn’t simply a new payment deadline. It changes how payroll, superannuation, and compliance interact.

Even small process gaps between payroll systems, clearing houses and super funds can quickly become compliance issues if left unchecked.

Businesses that proactively review their payroll processes, improve internal controls and monitor compliance regularly will be better positioned to meet their ongoing obligations while reducing administrative risk.

Need Help?

By working with us as your professional tax accountant and mortgage broker, you can be confident that your loans are structured to protect your tax position, maximise deductions, and avoid costly mistakes, giving you greater peace of mind and more control over your financial future.

Pitt Martin Group is a firm of Chartered Accountants, providing services including taxation, accounting, business consulting, self-managed superannuation funds, auditing and mortgage & finance. We spend hundreds of hours each year on training and researching new tax laws to ensure our clients can maximize legitimate tax benefit. Our contact information are phone +61292213345 or email info@pittmartingroup.com.au. Pitt Martin Group is located in the convenient transportation hub of Sydney’s central business district. Our honours include the 2018 CPA NSW President’s Award for Excellence, the 2020 Australian Small Business Champion Award Finalist, the 2021 Australia’s well-known media ‘Accountants Daily’ the Accounting Firm of the Year Award Finalist and the 2022 Start-up Firm of the Year Award Finalist, and the 2023 Hong Kong-Australia Business Association Business Award Finalist.

Pitt Martin Group qualifications include over fifteen years of professional experience in accounting industry, Registered Australia Tax Agents, membership certification of the Chartered Accountants Australia and New Zealand (CA ANZ), certified External Examiner of the Law Societies of New South Wales, Victoria, and Western Australia Law Trust Accounts, membership certification of the Finance Brokers Association of Australia Limited (FBAA), Registered Agents of the Australian Securities and Investments Commission (ASIC), certified Advisor of accounting software such as XERO, QUICKBOOKS, MYOB, etc.

This content is for reference only and does not constitute advice on any individual or group’s specific situation. Any individual or group should take action only after consulting with professionals. Due to the timeliness of tax laws, we have endeavoured to provide timely and accurate information at the time of publication, but cannot guarantee that the content stated will remain applicable in the future. Please indicate the source when forwarding this content.

By Nora Pham @ Pitt Martin Tax
Read more
Superannuation contribution caps to increase from 1 July 2026

Superannuation contribution caps are set to rise effective from 1 July 2026

Super contribution caps increased from 1 July 2026, following the release of the December 2025 quarter Average Weekly Ordinary Time Earnings (AWOTE). The annual concessional contribution (CC) cap rose from $30,000 to $32,500, while the non-concessional contribution (NCC) cap increased from $120,000 to $130,000. These changes may provide additional opportunities to grow retirement savings and improve tax efficiency.

Concessional Contributions

Concessional contributions are pre-tax contributions and may include Superannuation Guarantee (SG) payments, salary sacrifice arrangements, and personal deductible contributions. For individuals whose SG contributions remain below the annual cap, additional concessional contributions may help reduce taxable income and lower overall tax liabilities.

Some taxpayers may also qualify to use unused concessional contribution caps from the previous five financial years under the carry-forward contribution rules, provided their total superannuation balance (TSB) was below $500,000 at the previous 30 June.

Non-Concessional Contributions

Non-concessional contributions are made using after-tax income. Although they generally do not provide an immediate tax deduction, they can still offer long-term tax advantages because superannuation earnings are typically taxed at only 15% during the accumulation phase. In retirement, earnings and pension withdrawals may become tax-free, subject to the transfer balance cap, which will increase to $2,100,000 from 1 July 2026.

Eligible individuals may also access the bring-forward rule, allowing up to three years of NCC caps to be contributed at once. From 1 July 2026, this could allow contributions of up to $390,000 in a single financial year. However, eligibility depends on factors such as total superannuation balance and prior NCC contributions.

There may also be contribution opportunities available in the current financial year for individuals whose TSB was below $2,000,000 on 30 June 2025.

Recommended Action

With superannuation rules becoming increasingly complex, individuals and business owners should regularly review their contribution strategies, contribution caps, and total superannuation balances to avoid excess contribution penalties and maximise available tax benefits.

Need Help?

By working with us as your professional tax accountant and mortgage broker, you can be confident that your loans are structured to protect your tax position, maximise deductions, and avoid costly mistakes, giving you greater peace of mind and more control over your financial future.

Pitt Martin Group is a firm of Chartered Accountants, providing services including taxation, accounting, business consulting, self-managed superannuation funds, auditing and mortgage & finance. We spend hundreds of hours each year on training and researching new tax laws to ensure our clients can maximize legitimate tax benefit. Our contact information are phone +61292213345 or email info@pittmartingroup.com.au. Pitt Martin Group is located in the convenient transportation hub of Sydney’s central business district. Our honours include the 2018 CPA NSW President’s Award for Excellence, the 2020 Australian Small Business Champion Award Finalist, the 2021 Australia’s well-known media ‘Accountants Daily’ the Accounting Firm of the Year Award Finalist and the 2022 Start-up Firm of the Year Award Finalist, and the 2023 Hong Kong-Australia Business Association Business Award Finalist.

Pitt Martin Group qualifications include over fifteen years of professional experience in accounting industry, membership certification of the Chartered Accountants Australia and New Zealand (CA ANZ), membership certification of the Australian Society of Certified Practising Accountants (CPA), Registered Australia Tax Agents, certified External Examiner of the Law Societies of New South Wales, Victoria, and Western Australia Law Trust Accounts, membership certification of the Finance Brokers Association of Australia Limited (FBAA), Registered Agents of the Australian Securities and Investments Commission (ASIC), certified Advisor of accounting software such as XERO, QUICKBOOKS, MYOB, etc.

This content is for reference only and does not constitute advice on any individual or group’s specific situation. Any individual or group should take action only after consulting with professionals. Due to the timeliness of tax laws, we have endeavoured to provide timely and accurate information at the time of publication, but cannot guarantee that the content stated will remain applicable in the future. Please indicate the source when forwarding this content.

Read more