皮特马丁会计师事务所 Pitt Martin Group是一家提供税务,会计,生意咨询,自管养老金,审计及贷款等综合性服务的经澳洲特许会计师协会认证的注册会计师事务所。我们每年会花上几百个小时去研究新的税法,以保证我们的客户可以最大化合理避税。我们的中文联系方式是 Robert Liu +61292213345 或邮件 info@pittmartingroup.com.au。皮特马丁会计师事务所Pitt Martin Group坐落在交通便利的悉尼市市中心,是一家拥有可以说中文合伙人的会计师事务所。我们的荣誉包括2018年CPA新州首席优秀奖, 2020年澳大利亚小生意年度冠军入围奖, 2021年澳洲知名媒体《每日会计师》年度最佳会计师事务所冠军入围奖,2022年最佳会计师事务所新人入围奖和2023香港澳大利亚商业协会最佳积极生意入围奖。
皮特马丁会计师事务所 Pitt Martin Group资质包括超过十五年的从业经验,澳大利亚税务注册代理,澳大利亚与新西兰特许会计师协会(CAANZ)会员,新州、维州和西澳律师协会信托账户 (Trust Account) 认证审计师,澳大利亚金融贷款经纪人协会(FBAA)执业认证会员,澳大利亚证券及投资委员会注册代理,XERO, QUICKBOOKS, MYOB等会计软件授权单位及认证顾问。
Experienced Tax Accountant and Business Advisor with a demonstrated history of working in the accounting and mortgage industry. Skilled in Tax, Accounting, Business Advisory, SMSF, Audit and Mortgage. Strong entrepreneurship professional with qualification Master of Professional Accounting, CA Public Practice, Registered Tax Agent, Registered ASIC Agent, NSW Law Society External Examiner, Trust Account Auditor and Diploma of Finanical Planning. Specialised in SME, tax planning and international tax, he helped client save ample money and create wealth.
If your business is planning to buy or lease a vehicle in the new financial year, the updated 2026–27 car thresholds from the Australian Taxation Office (ATO) are worth a look before you sign anything. They shape three things that matter to your bottom line: depreciation, GST recovery, and whether Luxury Car Tax (LCT) applies.
For vehicles first used or leased from 1 July 2026, the car limit, GST credit cap, and LCT thresholds have all increased with indexation. Understanding how they interact can help you time a purchase and avoid surprises at tax time.
The Car Limit: The Depreciation Cap
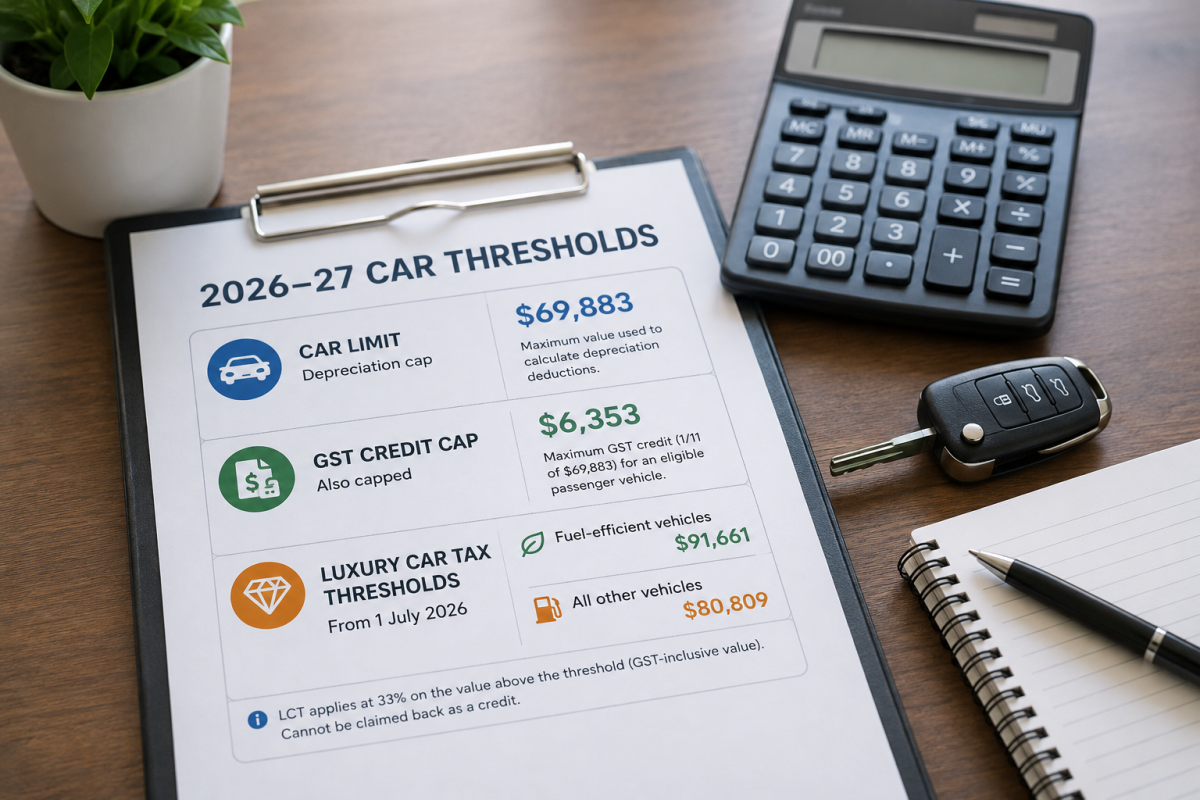
For 2026–27, the ATO car limit is $69,883, the maximum value used to calculate depreciation deductions for a passenger vehicle, regardless of actual purchase price. Buy above this and the excess generally cannot be depreciated. There may be good commercial reasons to buy something pricier, but beyond the car limit, extra spend typically produces no additional tax benefit.
A few points worth noting:
Mixed use: If a vehicle is used for both business and private purposes, you can only claim the business-use portion. A valid logbook, kept for a continuous 12-week period with odometer readings, is essential evidence if the ATO reviews your claim.
Depreciation method: Businesses may be eligible for simplified small business depreciation rules, allowing accelerated deductions. Confirm eligibility with your tax agent before purchase.
Timing: The applicable car limit is set by the income year the car is first used or held ready for use, not the invoice date. This matters if delivery slips past 1 July.
GST Credits: Also Capped
Businesses registered for GST can generally claim GST credits on vehicles bought for business use, but this is also capped by reference to the car limit. Once the price exceeds the limit, the credit is capped at one-eleventh of the limit, not one-eleventh of the actual price.
For 2026–27, the maximum GST credit on an eligible passenger vehicle is $6,353 (one-eleventh of $69,883), regardless of actual cost, and this applies to fuel-efficient and non-fuel-efficient vehicles alike.
Some flow-on consequences:
Selling later: GST is generally payable on the full sale price when the vehicle is sold, even though the credit claimed at purchase was capped. This asymmetry can catch owners off guard.
BAS reporting: Only the car-limit amount (or its business-use proportion) is reported at label G10, with the capped credit at label 1B.
Time limits: GST credits must generally be claimed within four years, so reconcile purchases promptly.
Cash flow: The credit is often a meaningful short-term benefit, worth weighing against financing or leasing.
Where the GST-inclusive value exceeds the relevant threshold, LCT generally applies at 33% on the value above it. Unlike GST, LCT cannot be claimed back as a credit, even for vehicles used entirely for business.
The gap between the two thresholds is increasingly relevant: more hybrid, plug-in hybrid and electric models now qualify for the higher threshold, reducing LCT versus an equivalent petrol or diesel model. This is worth weighing for fleets or client-facing vehicles. Check the current ATO definition before assuming a model qualifies, as the eligibility test has tightened in recent years.
Planning Ahead
Since these thresholds apply to any vehicle first used or leased from 1 July 2026, now is a good time to review planned purchases. Before committing, work through:
Total after-tax cost of ownership: depreciation, GST credits, LCT, financing, insurance and running costs, not just the drive-away price.
Buy versus lease: Outright purchase, chattel mortgage, novated leasing and operating leases each carry different depreciation, GST and cash flow implications, depending on turnover, cash position and vehicle use.
Business-use percentage: the records needed to support it, including a logbook, odometer readings, and trip diary where relevant.
Cash flow timing: whether to bring a purchase forward before 30 June or defer until after 1 July.
Key Takeaways
A business vehicle can be a significant investment. While tax considerations should not be the sole factor in your decision, they can play an important role in determining the overall cost of ownership.
Before making a purchase, it is worth speaking with your accountant to assess the potential tax implications based on your individual circumstances. Planning ahead can help you make the most of available tax concessions, avoid unexpected costs and ensure the purchase supports your broader business strategy.
By working with us as your professional tax accountant and mortgage broker, you can be confident that your loans are structured to protect your tax position, maximise deductions, and avoid costly mistakes, giving you greater peace of mind and more control over your financial future.
Pitt Martin Group is a firm of Chartered Accountants, providing services including taxation, accounting, business consulting, self-managed superannuation funds, auditing and mortgage & finance. We spend hundreds of hours each year on training and researching new tax laws to ensure our clients can maximize legitimate tax benefit. Our contact information are phone +61292213345 or email info@pittmartingroup.com.au. Pitt Martin Group is located in the convenient transportation hub of Sydney’s central business district. Our honours include the 2018 CPA NSW President’s Award for Excellence, the 2020 Australian Small Business Champion Award Finalist, the 2021 Australia’s well-known media ‘Accountants Daily’ the Accounting Firm of the Year Award Finalist and the 2022 Start-up Firm of the Year Award Finalist, and the 2023 Hong Kong-Australia Business Association Business Award Finalist.
Pitt Martin Groupqualifications include over fifteen years of professional experience in accounting industry, Registered Australia Tax Agents, membership certification of the Chartered Accountants Australia and New Zealand (CA ANZ), certified External Examiner of the Law Societies of New South Wales, Victoria, and Western Australia Law Trust Accounts, membership certification of the Finance Brokers Association of Australia Limited (FBAA), Registered Agents of the Australian Securities and Investments Commission (ASIC), certified Advisor of accounting software such as XERO, QUICKBOOKS, MYOB, etc.
This content is for reference only and does not constitute advice on any individual or group’s specific situation. Any individual or group should take action only after consulting with professionals. Due to the timeliness of tax laws, we have endeavoured to provide timely and accurate information at the time of publication, but cannot guarantee that the content stated will remain applicable in the future. Please indicate the source when forwarding this content.
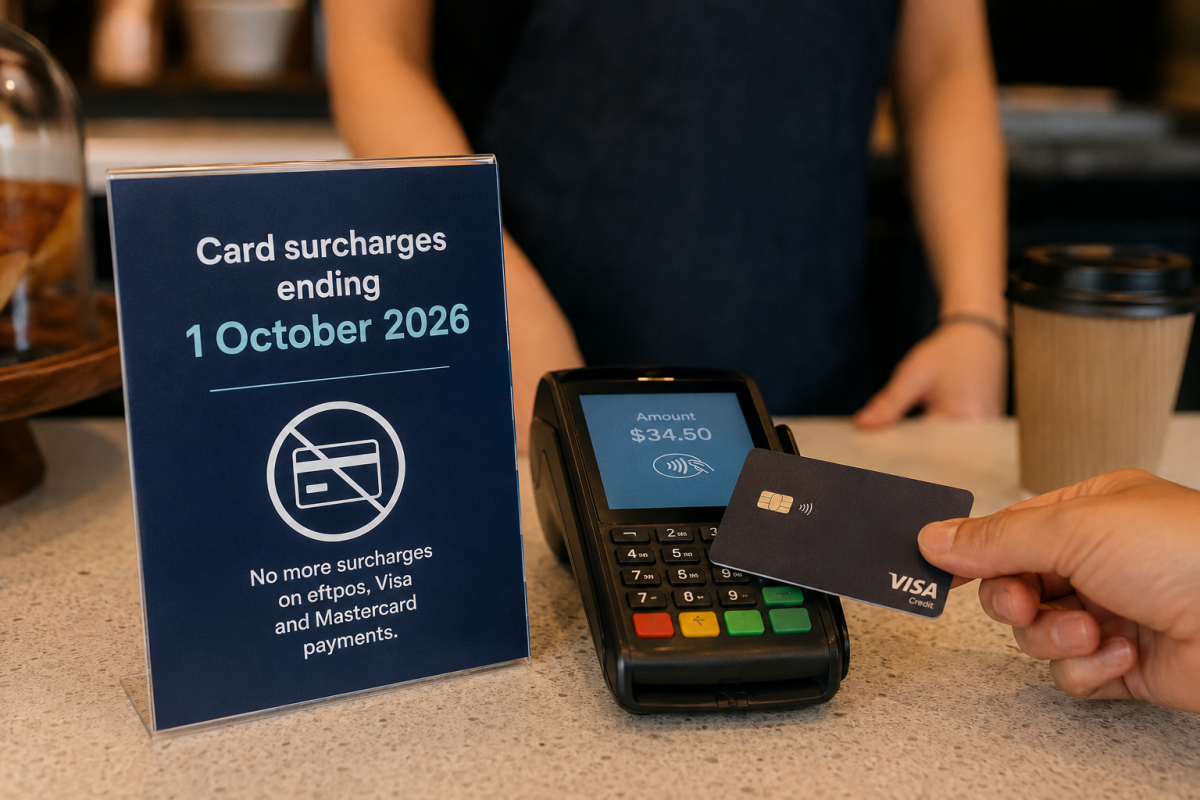
The card surcharge ban took effect across Australia on 1 October 2026. Under the Reserve Bank of Australia (RBA) reform, businesses can no longer add surcharges to credit and debit card payments made through eftpos, Visa and Mastercard.
For many businesses, card surcharges have become a common way to recover merchant payment costs. However, these new regulations aim to simplify pricing, improve transparency, and reduce payment costs across the economy.
If your business currently applies card surcharges, now is the time to start preparing.
Why Did the RBA Introduce the Card Surcharge Ban?
According to the RBA, Australian consumers pay approximately $1.6 billion annually in card surcharges. At the same time, businesses incur even greater costs when accepting electronic payments.
The reform package is designed to:
Eliminate unexpected checkout fees for consumers
Reduce overall payment processing costs for businesses
Improve transparency in the payments industry
Encourage competition among payment providers
Create a simpler and fairer pricing system
The RBA estimates that merchant payment costs could fall by approximately $910 million per year, with small businesses expected to benefit the most.
What Is Changing From 1 October 2026?
The new payment reforms consist of three key changes.
1. Card Surcharges Will Be Banned
From 1 October 2026, businesses will no longer be permitted to charge additional fees for payments made using:
eftpos
Visa
Mastercard
Related payment networks
This applies whether customers pay:
In-store
Online
Through mobile wallets
Via integrated payment systems
Customers must see a single final price without additional card payment charges being added at checkout.
2. Lower Interchange Fees
Interchange fees are wholesale charges exchanged between financial institutions when card payments are processed.
Under the new reforms:
Existing fee caps will be reduced
New limits will apply to foreign-issued cards
Payment acceptance costs should decrease for merchants
Lower interchange fees are expected to reduce the overall cost of accepting card payments, helping businesses offset the loss of surcharge revenue.
3. Increased Fee Transparency
Banks, payment providers, and card schemes will be required to provide clearer information regarding:
Merchant service fees
Processing costs
Fee structures
Provider margins
Payment providers must also demonstrate how wholesale fee reductions are being passed on to businesses.
This increased transparency should make it easier for business owners to compare providers, negotiate better rates, and make informed decisions about their payment systems.
The reforms will be supported by oversight from the Australian Competition and Consumer Commission (ACCC) and guidance from the Australian Small Business and Family Enterprise Ombudsman.
How Businesses Should Respond to the Card Surcharge Ban
Although the changes do not take effect until October 2026, businesses should begin reviewing their payment arrangements well in advance.
Review Your Merchant Fees
Start by examining your merchant statements and identifying:
Current card acceptance costs
Monthly processing fees
Revenue generated from surcharges
The overall impact on business margins
If surcharges currently help offset payment processing costs, you may need to review your pricing strategy to maintain profitability.
Speak With Your Payment Provider
The upcoming reforms create an opportunity to revisit your arrangements with your payment provider. As interchange fees are expected to decrease and fee transparency increases, businesses may be able to negotiate lower merchant service fees, more competitive pricing plans, or upgraded payment technology. Small businesses, which often pay higher effective processing rates, may stand to benefit the most from these discussions.
Update Your Pricing and POS Systems
Before the implementation date, businesses will need to remove:
Card surcharge notices
Checkout surcharge settings
Automatic percentage-based fees
Separate payment processing charges
All displayed prices must become fully inclusive.
Review both physical and online sales channels to ensure compliance with the new requirements.
Factor the Changes Into Cash Flow Planning
While lower merchant costs may not be immediate, many businesses are expected to experience savings during the 2026–27 financial year.
Industries that process large volumes of small transactions may see the greatest impact, including:
Cafés
Restaurants
Retail stores
Trade businesses
Service-based businesses
Now is a good time to update budgets and financial forecasts to account for the expected changes.
Monitor Customer Payment Behaviour
The removal of surcharges may encourage more customers to choose card payments rather than cash. This could improve convenience, speed up transactions, and reduce the need for cash handling. However, businesses should continue monitoring their payment costs as customer behavior changes to ensure any increase in card usage does not offset the savings generated by lower merchant fees.
How the Card Surcharge Ban Affects Australian Businesses
Ultimately, this reform creates a more level playing field across the Australian economy.
For businesses that never charged a surcharge will immediately benefit from lower underlying merchant fees, boosting your profitability.
For businesses that did charge a surcharge will enjoy far simpler daily operations, less administrative friction, and zero compliance risks.
Over time, this regulatory shakeup is expected to drive intense competition among payment providers, paving the way for superior financial products and even lower fees across the market. While banks may adjust secondary features like credit card rewards programs to offset their losses, the combined effort of the RBA and ACCC ensures savings are distributed fairly to businesses and consumers alike.
Final Thoughts
The end of card surcharges represents one of the most significant payment reforms in Australia in recent years.
For consumers, it means simpler pricing and fewer surprises at checkout. For businesses, it presents an opportunity to reduce complexity, improve operational efficiency, and potentially lower payment costs.
The key is preparation. Reviewing your payment arrangements now can help ensure a smooth transition before the 1 October 2026 deadline.
If you are unsure how these changes may affect your business, professional advice can help you assess merchant fees, evaluate pricing strategies, and identify opportunities to reduce costs before the new rules take effect.
Need Help?
By working with us as your professional tax accountant and mortgage broker, you can be confident that your loans are structured to protect your tax position, maximise deductions, and avoid costly mistakes, giving you greater peace of mind and more control over your financial future.
Pitt Martin Group is a firm of Chartered Accountants, providing services including taxation, accounting, business consulting, self-managed superannuation funds, auditing and mortgage & finance. We spend hundreds of hours each year on training and researching new tax laws to ensure our clients can maximize legitimate tax benefit. Our contact information are phone +61292213345 or email info@pittmartingroup.com.au. Pitt Martin Group is located in the convenient transportation hub of Sydney’s central business district. Our honours include the 2018 CPA NSW President’s Award for Excellence, the 2020 Australian Small Business Champion Award Finalist, the 2021 Australia’s well-known media ‘Accountants Daily’ the Accounting Firm of the Year Award Finalist and the 2022 Start-up Firm of the Year Award Finalist, and the 2023 Hong Kong-Australia Business Association Business Award Finalist.
Pitt Martin Groupqualifications include over fifteen years of professional experience in accounting industry, Registered Australia Tax Agents, membership certification of the Chartered Accountants Australia and New Zealand (CA ANZ), certified External Examiner of the Law Societies of New South Wales, Victoria, and Western Australia Law Trust Accounts, membership certification of the Finance Brokers Association of Australia Limited (FBAA), Registered Agents of the Australian Securities and Investments Commission (ASIC), certified Advisor of accounting software such as XERO, QUICKBOOKS, MYOB, etc.
This content is for reference only and does not constitute advice on any individual or group’s specific situation. Any individual or group should take action only after consulting with professionals. Due to the timeliness of tax laws, we have endeavoured to provide timely and accurate information at the time of publication, but cannot guarantee that the content stated will remain applicable in the future. Please indicate the source when forwarding this content.
From 1 July 2026, one of the biggest reforms to Australia’s superannuation system has officially taken effect. Under the new Payday Super rules, employers must ensure that superannuation contributions are received by employees’ super funds within seven business days of each payday.
This marks a significant shift from the previous quarterly payment system. While the reform aims to improve retirement outcomes for employees by ensuring super is paid sooner, it also introduces new payroll, cash flow and compliance obligations for businesses.
Whether you’re a small business owner or a larger employer, understanding the new requirements is essential to avoid penalties and maintain compliance.
What Is Payday Super?
Under the previous rules, employers generally had until 28 days after the end of each quarter to make super contributions. Under the new Payday Super system, the clock starts on each “Qualifying Earnings” (QE) day – which is essentially your payday for salary, wages, commissions, bonuses, and certain contractor payments.
Key Payday Super Requirements
Strict 7-Day Window: Contributions must be received and allocated to the employee’s fund within 7 business days of payday (with very limited exceptions).
Per-Payday Calculations: Shortfalls are now calculated per QE day rather than quarterly.
Clearing House Updates: The ATO’s Small Business Superannuation Clearing House has officially closed. Businesses previously using this service must now transition to a SuperStream-compliant alternative.
Penalties for Non-Compliance
The Australian Taxation Office (ATO) has introduced stronger enforcement measures under Payday Super.
Employers who fail to meet their obligations may face:
Superannuation Guarantee Charge (SGC) liabilities
Administrative penalties of up to 60% of the super shortfall
Additional interest and compliance costs
However, employers who voluntarily disclose mistakes early and take prompt corrective action may be eligible for reduced penalties.
During the first year of implementation, the ATO’s compliance approach under PCG 2026/1 focuses on businesses that make genuine efforts to comply. Employers who actively address issues are generally considered lower risk, although employee complaints will still be investigated.
The June – July 2026 Transition: A Common Compliance Trap
Many employers may overlook an important transitional issue when moving from the quarterly system to Payday Super.
If your business paid employees during the June 2026 quarter, the Super Guarantee deadline for that quarter remains 28 July 2026. However, any super contributions made after 1 July 2026 will first be allocated to outstanding June quarter obligations before being applied to Payday Super requirements for July payroll.
Without careful planning, businesses could unintentionally create Superannuation Guarantee Charge (SGC) liabilities despite making payments on time.
The appropriate strategy depends on your payroll schedule and the timing of July pay runs, making it worthwhile to review your payment timetable carefully.
Three Practical Steps to Prepare for Payday Super
1. Review Your Payroll Systems
Confirm that your payroll software, clearing house and internal processes are fully compatible with the new Payday Super requirements.
Check that:
Qualifying Earnings are correctly identified
Super calculations are accurate
SuperStream integration is functioning correctly
Payment workflows are automated where possible
2. Assess Cash Flow Impacts
Moving from quarterly to more frequent super payments will affect business cash flow.
Consider reviewing:
Payroll funding processes
Approval workflows
Bonus and commission payment procedures
Out-of-cycle payroll processes
Planning ahead can help minimise cash flow pressure while ensuring compliance.
3. Strengthen Internal Controls
Payroll and finance teams should clearly understand the new obligations.
Regular reviews of payroll reports, contribution records and payment confirmations can help identify issues early before they become costly compliance problems
Why Businesses Should Act Now
Payday Super isn’t simply a new payment deadline. It changes how payroll, superannuation, and compliance interact.
Even small process gaps between payroll systems, clearing houses and super funds can quickly become compliance issues if left unchecked.
Businesses that proactively review their payroll processes, improve internal controls and monitor compliance regularly will be better positioned to meet their ongoing obligations while reducing administrative risk.
By working with us as your professional tax accountant and mortgage broker, you can be confident that your loans are structured to protect your tax position, maximise deductions, and avoid costly mistakes, giving you greater peace of mind and more control over your financial future.
Pitt Martin Group is a firm of Chartered Accountants, providing services including taxation, accounting, business consulting, self-managed superannuation funds, auditing and mortgage & finance. We spend hundreds of hours each year on training and researching new tax laws to ensure our clients can maximize legitimate tax benefit. Our contact information are phone +61292213345 or email info@pittmartingroup.com.au. Pitt Martin Group is located in the convenient transportation hub of Sydney’s central business district. Our honours include the 2018 CPA NSW President’s Award for Excellence, the 2020 Australian Small Business Champion Award Finalist, the 2021 Australia’s well-known media ‘Accountants Daily’ the Accounting Firm of the Year Award Finalist and the 2022 Start-up Firm of the Year Award Finalist, and the 2023 Hong Kong-Australia Business Association Business Award Finalist.
Pitt Martin Groupqualifications include over fifteen years of professional experience in accounting industry, Registered Australia Tax Agents, membership certification of the Chartered Accountants Australia and New Zealand (CA ANZ), certified External Examiner of the Law Societies of New South Wales, Victoria, and Western Australia Law Trust Accounts, membership certification of the Finance Brokers Association of Australia Limited (FBAA), Registered Agents of the Australian Securities and Investments Commission (ASIC), certified Advisor of accounting software such as XERO, QUICKBOOKS, MYOB, etc.
This content is for reference only and does not constitute advice on any individual or group’s specific situation. Any individual or group should take action only after consulting with professionals. Due to the timeliness of tax laws, we have endeavoured to provide timely and accurate information at the time of publication, but cannot guarantee that the content stated will remain applicable in the future. Please indicate the source when forwarding this content.
A new financial year is an important time for all kinds of businesses, from sole traders to big corporate. It is not only to meet your tax obligations with the Australian Taxation Office, but also the perfect time to plan for the next 12 months of your business.
There
is certainly lots to do as a small business owner as you focus on year-end
accounting and bookkeeping tasks besides some planning for the new financial
year. To help you organise your financial records, Pitt Martin has put together
a handy EOFY checklist for businesses.
You need to ensure your BAS lodgements are up-to-date and accurate. This is not only making it easier for you to finalise your financial statements but also avoid penalty from the ATO
You need to ensure your superannuation guarantee (SG) contributions are accurate and up to date. Please note that your March SG is due 28 April 2020 and if you have previous quarters outstanding, you need to act as soon as possible or contact your accountant and bookkeeper for guidance.
If you are reporting to the ATO via Single Touch Payroll (STP), you are exempt from lodging a PAYG payment summary (Group Certificate) annual report for the amount you’ve reported through STP and from providing payment summaries to your employees so long as you undertake the finalisation declaration by the appropriate date. Please note that you can finalise your employees’ EOFY payroll information through your STP enabled software as soon as you have reconciled the information. Otherwise, you have up until 31 July to do so. Your employees will be able to access their income statements via myGov under the employment tab. If they do not have a myGov account and cannot create one, or do not have a registered agent, you can direct them to contact ATO on 13 28 61.
You need to ensure that you keep records for at least 5 years, and they are compliant with the ATO requirements
If you prepared your bookkeeping during the year, please make sure you have your accountant to review the transactions and GST codes assigned to the Profit and Loss and Balance Sheet items to ensure you are lodging a correct BAS.
The stocktake of your inventory should be done by 30 June 2020, if your business carries stock. Any adjustment on stock quantities and wastage should be reflected in the 2020 accounts.
If you maintain an asset register for your business, you need to review with your accountant or bookkeeper and remove any assets that had been disposed of or write off. Speak to your accountant about the instant asset write-off that the government introduced as part of the Australian Government’s economic response to coronavirus.
You need to ensure the following have been completed and reflected in your Profit and Loss and Balance Sheet,
Bank accounts, petty cash, prepayments, credit cards, borrowing cost, loans, Chattel Mortgages, and Division 7A Loans are reconciled
Depreciation has been properly accounted up to 30 June 2020 in the Profit and Loss and Balance Sheet
Review your Debtors and Creditors balance to ensure the accuracy
GST and PAYG withholding accounts are reconciled to the June quarter BAS
Wages and Superannuation in the Profit and Loss are reconciled to the Payment Summaries.
Superannuation Payable in the Balance Sheet is reconciled to the June quarter superannuation guarantee contributions
Review the suspense account and ensure all amounts are allocated to the appropriate account
Ensure there have been no personal expenses claimed as business expenses
With
many businesses facing unprecedented challenges from COVID-19, there is no
better time for small business owners to start afresh and thinking about
improving their current business performance.
We
have included additional checklist which hopefully can help you improve your
business performance and financial health going forward,
You need to revisit your business plan and adjust accordingly to provide a better and clearer direction for your business amid the pandemic. You need to think about what areas of your business do you want to improve? Your accountant can be an important resource to help you put in place a plan to get where you want your business to be.
You need to update your cash flow budgets for the next 12 months by comparing it to the actual performance. Cash flow is the lifeblood of your small business and needs to be looked at closely for your business to sustain. Review your pricing structure and if you need to raise your price, now is the best time to do. Again, your accountant will be able to assist in the pricing and cash flow budgets.
You need to review your business insurances or public liability to ensure you have a sufficient level of coverage
You need to review your financing arrangements to ensure that you have a better deal
You need to review your own personal insurances including life insurance and income protection insurance to ensure you have adequate coverage should your circumstances have changed
You need to review your health and safety policies and procedures to ensure your workplace is COVID Safe by following the guidance from the government for the safety plan.
If you are still using a spreadsheet or other manual accounting system, you might want to consider switching to cloud-based accounting software. Your accountant will be able to assist you with the transition.
In the face of uncertainty caused by the global pandemic, actions taken now can have an immediate impact on how quickly your business rebounds from the global downturn.
Need Help?
If you are unsure whether your accounts are ready for year end, or whether your BAS, super and STP reporting are up to date, Pitt Martin Group can help you review and document your business records, weigh up reconciliations, stocktake and asset write-offs, and prepare accurate financial statements before the new year begins.
As Sydney tax accountants, we assist businesses with year-end accounts, BAS lodgement and practical cash flow advice.
Pitt Martin Group is a firm of Chartered Accountants, providing services including taxation, accounting, business consulting, self-managed superannuation funds, auditing and mortgage & finance. We spend hundreds of hours each year on training and researching new tax laws to ensure our clients can maximize legitimate tax benefit. Our contact information are phone +61292213345 or email info@pittmartingroup.com.au. Pitt Martin Group, Sydney tax accountants, is located in the convenient transportation hub of Sydney’s central business district. Our honours include the 2018 CPA NSW President’s Award for Excellence, the 2020 Australian Small Business Champion Award Finalist, the 2021 Australia’s well-known media ‘Accountants Daily’ the Accounting Firm of the Year Award Finalist and the 2022 Start-up Firm of the Year Award Finalist, and the 2023 Hong Kong-Australia Business Association Business Award Finalist.
Pitt Martin Group qualifications include over fifteen years of professional experience in accounting industry, Registered Australia Tax Agents, membership certification of the Chartered Accountants Australia and New Zealand (CA ANZ), certified External Examiner of the Law Societies of New South Wales, Victoria, and Western Australia Law Trust Accounts, membership certification of the Finance Brokers Association of Australia Limited (FBAA), Registered Agents of the Australian Securities and Investments Commission (ASIC), certified Advisor of accounting software such as XERO, QUICKBOOKS, MYOB, etc.
This content is for reference only and does not constitute advice on any individual or group’s specific situation. Any individual or group should take action only after consulting with professionals. Due to the timeliness of tax laws, we have endeavoured to provide timely and accurate information at the time of publication, but cannot guarantee that the content stated will remain applicable in the future. Please indicate the source when forwarding this content.
Experienced Tax Accountant and Business Advisor with a demonstrated history of working in the accounting and mortgage industry. Skilled in Tax, Accounting, Business Advisory, SMSF, Audit and Mortgage. Strong entrepreneurship professional with qualification Master of Professional Accounting, CA Public Practice, Registered Tax Agent, Registered ASIC Agent, NSW Law Society External Examiner, Trust Account Auditor and Diploma of Finanical Planning. Specialised in SME, tax planning and international tax, he helped client save ample money and create wealth.
Don’t let coronavirus sink your business. The last few months have brought constant and unexpected challenges for business owners and leaders as they try to keep operating during the COVID-19 pandemic. Now, with the government announcing a major easing of restrictions, the latest challenge may be the trickiest yet: how to reopen safely and carefully.
Businesses
will be faced with many logistical details including how to maintain social
distance, limit crowd size, and ensure spaces are cleaned thoroughly and
regularly. It will take some time to lift the level of confidence in people to
start visiting shops, restaurants, and other public venues. In such an
uncertain and diverging environment, how can small businesses move forward and
back to “business as usual”? There are many opportunities for us as business
owners and leaders to unify and build this together amid the uncertainty.
Patience
Patience
is not the ability to wait, but the ability to keep a good attitude while
waiting. In today’s world, where technology has created the expectation that
everything should move more quickly, patience becomes one of the rarest
virtues. No one has the patience to wait for anything anymore. However, we need
to be careful to not rush everything. We should be careful not to move faster
than governments allow.
We
should be patient with a timeline that might be slower than we anticipated;
patient with a reopening process that might be awkward; patient with the line-up
that we have to face when entering the shops; patient with our leaders feeling
the pressure of this difficult situation; patient with one another as we are
getting used to with the new normal. As hard as it will be to practice
patience, we must be determined as it is unquestionable the second wave of
Covid-19 cases, or a local outbreak would detrimentally impact businesses.
Humility
Humility
is to have a student mindset and always be willing to learn new things. With so
many changes in the world amid the pandemic, we need to quick to hear, slow to
speak, and slow to anger. When you listen, it may slow down the process of
consideration and planning, but it is worth it. We need to be humble to learn to
adapt and to accept that things might not be the same as they used to be.
We
need humility in how we react to the plans by the government leaders, even if
we do not agree with every aspect of it. There is no definitive answer on how
to do this well and everyone is just trying to do the best they can to get
through this crisis. If we are willing to learn and adapt with all humility, we
will be able to survive.
Service
This
pandemic is affecting us individually, societally, and organisationally. During
this pandemic, we all need to step up and be a leader to do what we can for the
greater good. If you are fortunate enough to have cash in your pockets, you can
use it to support other businesses. We need to think of ways we can serve our
friends, family, neighbours, and community as a whole. We need to encourage
“we” before “me” and show gratitude and compassion for others.
If
you can make your business about helping others during this crisis, you will
always have plenty of work because no one has ever become poor by giving. There
is no better time than now to put the needs of others ahead of our own. Remember,
success has nothing to do with what you gain in life or accomplish for yourself;
it is what you do for others.
There
is no need to panic. Tough times never last but tough people do. If we can all
continue to show up as servant leaders with patience and humility to serve
others, we can get through this uncertainty and crisis stronger than ever.
Don’t
let this uncertainty sink your business, reach out for help not because you are
weak, but because you want to remain strong.
Need Help?
If you are unsure how to restart your business safely as restrictions ease, or whether your plans still match the pace of recovery, Pitt Martin Group can help you review and document your financial position, weigh up cash flow, staffing and reopening costs, and prepare a realistic plan to move forward with confidence.
As Sydney tax accountants, we assist businesses with reopening plans, cash flow forecasts and practical recovery advice.
Pitt Martin Group is a firm of Chartered Accountants, providing services including taxation, accounting, business consulting, self-managed superannuation funds, auditing and mortgage & finance. We spend hundreds of hours each year on training and researching new tax laws to ensure our clients can maximize legitimate tax benefit. Our contact information are phone +61292213345 or email info@pittmartingroup.com.au. Pitt Martin Group, Sydney tax accountants, is located in the convenient transportation hub of Sydney’s central business district. Our honours include the 2018 CPA NSW President’s Award for Excellence, the 2020 Australian Small Business Champion Award Finalist, the 2021 Australia’s well-known media ‘Accountants Daily’ the Accounting Firm of the Year Award Finalist and the 2022 Start-up Firm of the Year Award Finalist, and the 2023 Hong Kong-Australia Business Association Business Award Finalist.
Pitt Martin Group qualifications include over fifteen years of professional experience in accounting industry, Registered Australia Tax Agents, membership certification of the Chartered Accountants Australia and New Zealand (CA ANZ), certified External Examiner of the Law Societies of New South Wales, Victoria, and Western Australia Law Trust Accounts, membership certification of the Finance Brokers Association of Australia Limited (FBAA), Registered Agents of the Australian Securities and Investments Commission (ASIC), certified Advisor of accounting software such as XERO, QUICKBOOKS, MYOB, etc.
This content is for reference only and does not constitute advice on any individual or group’s specific situation. Any individual or group should take action only after consulting with professionals. Due to the timeliness of tax laws, we have endeavoured to provide timely and accurate information at the time of publication, but cannot guarantee that the content stated will remain applicable in the future. Please indicate the source when forwarding this content.
Experienced Tax Accountant and Business Advisor with a demonstrated history of working in the accounting and mortgage industry. Skilled in Tax, Accounting, Business Advisory, SMSF, Audit and Mortgage. Strong entrepreneurship professional with qualification Master of Professional Accounting, CA Public Practice, Registered Tax Agent, Registered ASIC Agent, NSW Law Society External Examiner, Trust Account Auditor and Diploma of Finanical Planning. Specialised in SME, tax planning and international tax, he helped client save ample money and create wealth.
Tax time is fast approaching and for some of you this might
be the last thing on your mind. There might be other things that are more
important for you to get through this uncertainty. However, now is the best
time to get your tax affair in order and avoid last minute planning that can
cost you.
As you have spent more time working from home during the
lockdown period, it might be a good idea to put together all the information
you need to prepare your returns as it will take some time especially if you have
not organised them as you go. You can collect all your receipts or invoices for
work related expenses and any credit card statements for invoices that you no
longer had and discuss with your tax agent to ensure you are maximising your
claims.
If you have been working from home as a result of COVID-19, the Australian Taxation Office has introduced special arrangements which will allow people to claim 80 cents per hour for all their running expenses, rather than needing to calculate costs for specific running expenses. You will need to keep a record of the number of hours you have worked from home. This will apply from March 1 to June 30, after which the ATO will review the arrangement for the next financial year.
If you choose to use the 80 cents per hour for all your
running expenses, you can’t make other claims in relation to working from home because
items such as mobile phone and internet are included in the 80 cent rate.
You still had the option to use the old claiming method which
is known as the 52 cents per work hour method for claiming items such as
heating, cooling, lighting, cleaning and the decline in value of office
furniture. You need to keep a diary of when your start and finish work each day.
This old method also allowed you to calculate the work-related portion of phone
and internet expenses, computer consumables, stationery and the decline in
value of a computer, laptop or similar device. Nevertheless, you would still require
to work out what private use and work use is on ‘a reasonable basis”
You can claim tools or equipment as a deduction in your tax
return if you have to use them as part of your job and your employer didn’t
reimburse you. You can claim a deduction straight away if the tools or
equipment are $300 or less otherwise you will need to depreciate over the life
of the item. On the other hand, if you run your own business and acquired all
your capital items from 12 March 2020 and the cost of all of them less than
$150,000, you can claim a deduction straight away. The capital items included
work related IT equipment, cars and tools. Please note that you will still
require to apportion the cost if you use them for private use.
As we are approaching the end of financial year, we still have
plenty of time to generate some extra common tax deductions if you made the
payment by 30 June:
Donation to a charity registered as a deductible gift recipient
over $2 with a receipt are tax deductible
A personal contribution into your super fund including the
contribution made on your behalf by your employer which are less than $25,000
can be claim as a tax deduction providing the payment made by 30 June. You need
to advise your super fund by completing the relevant form or speak to your
accountant for guidance.
You need to pay by 30 June your professional membership or
subscriptions and union fees to claim the deduction this year
Remember that good record keeping including invoices and
receipts will ensure the finalisation of your tax return easier and you can
claim for everything you’re eligible to.
If you know anyone in your circle who need any assistance during tax time, please reach out to them because “We can’t help everyone, but everyone can help someone” and “Together We Can Make A Difference”
Need Help?
If you are unsure which work-related expenses you can claim this year, or what you should pay before 30 June to maximise your deductions, Pitt Martin Group can help you review and document your records, weigh up home office, equipment and super contributions, and prepare an accurate return you can lodge with confidence.
As Sydney tax accountants, we assist individuals with tax returns, deduction reviews and practical year-end planning advice.
Pitt Martin Group is a firm of Chartered Accountants, providing services including taxation, accounting, business consulting, self-managed superannuation funds, auditing and mortgage & finance. We spend hundreds of hours each year on training and researching new tax laws to ensure our clients can maximize legitimate tax benefit. Our contact information are phone +61292213345 or email info@pittmartingroup.com.au. Pitt Martin Group, Sydney tax accountants, is located in the convenient transportation hub of Sydney’s central business district. Our honours include the 2018 CPA NSW President’s Award for Excellence, the 2020 Australian Small Business Champion Award Finalist, the 2021 Australia’s well-known media ‘Accountants Daily’ the Accounting Firm of the Year Award Finalist and the 2022 Start-up Firm of the Year Award Finalist, and the 2023 Hong Kong-Australia Business Association Business Award Finalist.
Pitt Martin Group qualifications include over fifteen years of professional experience in accounting industry, Registered Australia Tax Agents, membership certification of the Chartered Accountants Australia and New Zealand (CA ANZ), certified External Examiner of the Law Societies of New South Wales, Victoria, and Western Australia Law Trust Accounts, membership certification of the Finance Brokers Association of Australia Limited (FBAA), Registered Agents of the Australian Securities and Investments Commission (ASIC), certified Advisor of accounting software such as XERO, QUICKBOOKS, MYOB, etc.
This content is for reference only and does not constitute advice on any individual or group’s specific situation. Any individual or group should take action only after consulting with professionals. Due to the timeliness of tax laws, we have endeavoured to provide timely and accurate information at the time of publication, but cannot guarantee that the content stated will remain applicable in the future. Please indicate the source when forwarding this content.
Experienced Tax Accountant and Business Advisor with a demonstrated history of working in the accounting and mortgage industry. Skilled in Tax, Accounting, Business Advisory, SMSF, Audit and Mortgage. Strong entrepreneurship professional with qualification Master of Professional Accounting, CA Public Practice, Registered Tax Agent, Registered ASIC Agent, NSW Law Society External Examiner, Trust Account Auditor and Diploma of Finanical Planning. Specialised in SME, tax planning and international tax, he helped client save ample money and create wealth.
The tax-free payments to employers, officially called the Boosting Cash Flow for Employers measure, are part of the Federal Government‘s economic response to COVID-19. They are designed to support small and medium businesses that employ staff and to improve business confidence. The measure also supports not-for-profits, including charities, at a time when they are facing increased demand for services.
On 12 March 2020, the Government announced the cash flow grant for employers measure and initially provided up to $25,000 with a minimum payment of $2,000 for eligible businesses. Small and medium sized business entities that employ workers with aggregated annual turnover less than $50 million are eligible.
The Government has then improved this measure as part of the second economic stimulus package. Not-for-profit entities (NFPs), including charities that employ workers, with aggregated annual turnover less than $50 million will now also be eligible. This will support employment activities at a time where NFPs are facing increasing demand for services.
Under the improved scheme, employers will receive a payment equal to 100 per cent of their salary and wages withheld (increase from 50 per cent), with the maximum payment being increased from $25,000 to $50,000. Furthermore, the minimum payment is being increased from $2,000 to $10,000.
An additional payment is also being introduced in the July to October 2020 period. Eligible entities will receive an additional payment equal to the total of all of the cash flow grant for employers payments they have received. This means that eligible entities will receive at least $20,000 up to a total of $100,000 under both payments. The cash flow grant for employers is tax-free payment with no new forms required and automatically calculated by the ATO
This additional payment continues to support businesses over a longer period to help them maintain staff, improve confidence, continue operating and at the same time stimulating the economy. It’s crucial for the government to help small businesses because they are the backbone of the economy.
Who is eligibleand what is the timing?
SME business entities and NFPs that employ workers, with aggregated annual turnover less than $50 million will be eligible with the eligibility generally be based on prior year turnover.
The payment will be an automatic credit in the activity statement system from 28 April 2020 upon employers lodging eligible upcoming activity statements.
Eligible employers that withhold tax on their employees’ salary and wages will receive a payment equal to 100 per cent of the amount withheld, up to a maximum payment of $50,000.
Eligible employers that pay salary and wages will receive a minimum payment of $10,000, even if they are not required to withhold tax.
The payments will only be available to active eligible employers established prior to 12 March 2020 except charities which are registered with the Australian Charities and Not-for-profits Commission will be eligible regardless of when they were registered, subject to meeting other eligibility requirements.
The cash flow grant for employers payment will be applied to a limited number of activity statement lodgements. The ATO will send the payment as a credit to the entity upon lodgement of their activity statements. The ATO will send the refund within 14 days if the entity is entitled to a refund.
Type of lodger
Eligible period
Lodgement due date
Quarterly
Quarter 3 (January, February and March 2020) Quarter 4 (April, May and June 2020)
28 April 2020 28 July 2020
Monthly
March 2020 April 2020 May 2020 June 2020
21 April 2020 21 May 2020 22 June 2020 21 July 2020
If you lodged quarterly, you will be eligible to receive the payment for the quarters ending March and June 2020.
If you lodged monthly, you will be eligible to receive the payment for the March, April, May and June 2020 lodgements. To provide a similar treatment to quarterly lodgers, the payment for monthly lodgers will be calculated at three times the rate (which is 300 per cent) in the March 2020 activity statement with the minimum payment will be applied to the entities’ first lodgement.
Additional payment eligibility and timing
Your entity must remain active in order to qualify for the additional payment from the Government.
If you lodged activity statements monthly, the additional payments will be delivered as an automatic credit in the activity statement system. This will be equal to a quarter of their total initial cash flow grant for employers payment following the lodgement of their June, July, August and September 2020 activity statements up to a total of $50,000.
If you lodged activity statements quarterly, the additional payments will be sent as an automatic credit in the activity statement system. This will be equal to half of their total initial cash flow grant for employers payment following the lodgement of their June and September 2020 activity statements up to a total of $50,000.
The additional payment will be applied to a limited number of activity statement lodgements. The ATO will send the payment as a credit to the entity upon lodgement of their activity statements. The ATO will send the refund within 14 days if the entity is entitled to a refund.
Type of lodger
Eligible period
Lodgement due date
Quarterly
Quarter 4 (April, May and June 2020) Quarter 1 (July, August and September 2020)
28 July 2020 28 October 2020
Monthly
June 2020 July 2020 August 2020 September 2020
21 July 2020 21 August 2020 22 September 2020 21 October 2020
If you lodged quarterly, you will be eligible to receive the additional payment for the quarters ending June 2020 and September 2020. Each additional payment will be equal to half of their total initial cash flow grant for employers payment with up to a total of $50,000.
If you lodged monthly, you will be eligible to receive the additional payment for the June, July, August and September 2020 lodgements. Each additional payment will be equal to a quarter of their total initial cash flow grant for Employers payment with up to a total of $50,000.
Examples of Tax-Free Payment to Employers
Example 1 – John’s Removalist Business
John owns and runs a removalist business in Western Australia and employs 10 workers on average full-time weekly earnings, who each earn $90,750 per year. John reports withholding of $15,600 for his employees on each of his monthly Business Activity Statements (BAS).
Under the Government’s measure, John will be eligible to obtain the payment on lodgement of his BAS. John’s business receives:
A credit of $46,800 for the March period
A credit of $3,200 for the April period, before he reaches the $50,000 cap.
No payment for the May period, as he has now reached the $50,000 cap.
An additional payment of $12,500 for the June, July, August and September period, respectively
Under the Government’s enhanced cash flow grant for employers measure, John’s business will receive $100,000.
Example 2 – Tony’s Barber Shop
Tony owns a barber shop on the Surfers Paradise. He employs 10 employees, with average salary of $45,000 per year. Tony reports withholding of $8,601 for his employees in each of his monthly BAS. Under the measure, Tony will be eligible to receive the payments on lodgement of his relevant BAS.
Tony’s business will receive:
A credit of $25,803 for the March period
A credit of $8,601 for the April and May period, respectively
A credit of $6,995 for the June period, before he reaches the $50,000 cap. Tony will also receive an additional payment of $12,500 for the June, July, August and September period, respectively
Under the Government’s enhanced cash flow grant for employers measure, Tony’s business will receive $100,000.
Example 3 – Todd’s Courier Run
Todd owns and runs a small paper delivery business in South Australia and employs two casual employees who each earn $10,000 per year. In his quarterly BAS, Todd reports $0 withholding tax for his employees as they are under the tax-free threshold.
Under the Government’s measure, Todd will be eligible to receive the payment on lodgement of his BAS.
Todd’s business will receive:
A credit of $10,000 for the March quarter, as he pays salary and wages but is not required to withhold tax.
An additional payment of $5,000 for the June and September quarter, respectively
If Todd begins withholding tax for the June quarter, he would need to withhold more than $10,000 before he receives any additional payment.
Under the Government’s enhanced cash flow grant for employers measure, Todd’s business will receive $20,000.
If you know anyone in your circle who need any assistance during these times, please reach out to them because “We can’t help everyone, but everyone can help someone”and “Together We Can Make A Difference”
Need Help?
If you are unsure whether your business or charity qualifies for the cash flow grant for employers, or how much you will receive from each lodgement, Pitt Martin Group can help you review and document your withholding, weigh up eligibility, reporting periods and additional payments, and prepare accurate statements that maximise your entitlement.
As Sydney tax accountants, we assist employers with BAS lodgement, cash flow grants and practical compliance advice.
Pitt Martin Group is a firm of Chartered Accountants, providing services including taxation, accounting, business consulting, self-managed superannuation funds, auditing and mortgage & finance. We spend hundreds of hours each year on training and researching new tax laws to ensure our clients can maximize legitimate tax benefit. Our contact information are phone +61292213345 or email info@pittmartingroup.com.au. Pitt Martin Group, Sydney tax accountants, is located in the convenient transportation hub of Sydney’s central business district. Our honours include the 2018 CPA NSW President’s Award for Excellence, the 2020 Australian Small Business Champion Award Finalist, the 2021 Australia’s well-known media ‘Accountants Daily’ the Accounting Firm of the Year Award Finalist and the 2022 Start-up Firm of the Year Award Finalist, and the 2023 Hong Kong-Australia Business Association Business Award Finalist.
Pitt Martin Group qualifications include over fifteen years of professional experience in accounting industry, Registered Australia Tax Agents, membership certification of the Chartered Accountants Australia and New Zealand (CA ANZ), certified External Examiner of the Law Societies of New South Wales, Victoria, and Western Australia Law Trust Accounts, membership certification of the Finance Brokers Association of Australia Limited (FBAA), Registered Agents of the Australian Securities and Investments Commission (ASIC), certified Advisor of accounting software such as XERO, QUICKBOOKS, MYOB, etc.
This content is for reference only and does not constitute advice on any individual or group’s specific situation. Any individual or group should take action only after consulting with professionals. Due to the timeliness of tax laws, we have endeavoured to provide timely and accurate information at the time of publication, but cannot guarantee that the content stated will remain applicable in the future. Please indicate the source when forwarding this content.
Experienced Tax Accountant and Business Advisor with a demonstrated history of working in the accounting and mortgage industry. Skilled in Tax, Accounting, Business Advisory, SMSF, Audit and Mortgage. Strong entrepreneurship professional with qualification Master of Professional Accounting, CA Public Practice, Registered Tax Agent, Registered ASIC Agent, NSW Law Society External Examiner, Trust Account Auditor and Diploma of Finanical Planning. Specialised in SME, tax planning and international tax, he helped client save ample money and create wealth.
A business continuity plan has never been more important. The COVID-19 situation is bigger than anything most of us have faced. Many business owners, professionals, mums and dads are scared, don’t know what to do and may not have thought through the consequences for them, or how much an accountant’s help could make a difference.
As
a business owner, there’s one key thing you need to focus on now which is keeping
your business alive during these tough times. Downturn can be scary usually
because there is no plan in place for your business and the world around you
appear to be panicking. There is no reason to be panicking. In times of
difficulty lies an opportunity. If your cash flow is under control then so is your
business.
You
need to take actionable appropriate steps to create a Continuity Plan, then in
reality a downturn is just a stop gap to the next upturn, where your business
will be cash flow fit and ready to take full advantage.
To
maintain your cash, you may need to consider options that you haven’t consider
before. You need to work with your accountant to identify which key parts your
business is eligible for Australian Government stimulus package and get the
process started to obtain these cash flow bonuses. When you meet with your
accountant, it’s important to update your business cash flow plan over the
coming months.
As
an employer, you need to openly discuss reduced working hours with your
employees to save cash (if this does save cash) and working from home
arrangements. Employees will be scared. They will need to be assured, so they
need to be given an understanding of the plan to keep the business alive.
Constant communication and a payment plan with the ATO could be an option especially if you need to delay making payments of GST and PAYG Withholding Tax. However it’s vital that you keep lodging you Business Activity Statements (BAS) and Instalment Activity Statements (IAS) by their due dates. The Australian Taxation Office (ATO) is implementing a series of relief options to assist those impacted by the coronavirus. The relief will not be automatically applied. You can contact your accountant to contact the ATO to make any requests for assistance.
In
addition, you can contact your Bank Manager as soon as possible and arrange for
additional bank funding or lines of credit that can be approved now for use in
an emergency. Making these arrangements early before things have gone bad is
the key. Bank approvals may take up to one month or longer. Consider also using
alternative funders to set up a short term line of credit now to pay for
inventory and operating costs. You should consider doing this as a backup now
to any other bank lending arrangements you may have.
If
you have to self-quarantine or if you incapacitated in any way, you need to have
an Enduring Power of Attorney (EPOA) in place so your business can continue to operate.
Ensure your EPOA and Will are up to date now and ensure your family and your
Accountant know where the original signed documents are.
Now
is the time to contact your insurance agent to review your policy to understand
precisely what you are and are not covered for in the event of an extended
incident. Review your general insurance policies for any Business Interruption
Insurance inclusions.
We
need to stay calm and rely on reliable sources of information from State and
Australian Government. In the meantime, below is the link directly to the
Government Media release of the second Economic Stimulus Plan, https://www.pm.gov.au/media/supporting-australian-workers-and-business
Need Help?
If you are unsure how to keep your business running through COVID-19, or which parts of the stimulus package you can access, Pitt Martin Group can help you review and document your cash flow, weigh up stimulus support, ATO payment plans and funding options, and prepare a continuity plan for the months ahead.
As Sydney tax accountants, we assist businesses with continuity planning, ATO relief and practical cash flow advice.
Pitt Martin Group is a firm of Chartered Accountants, providing services including taxation, accounting, business consulting, self-managed superannuation funds, auditing and mortgage & finance. We spend hundreds of hours each year on training and researching new tax laws to ensure our clients can maximize legitimate tax benefit. Our contact information are phone +61292213345 or email info@pittmartingroup.com.au. Pitt Martin Group, Sydney tax accountants, is located in the convenient transportation hub of Sydney’s central business district. Our honours include the 2018 CPA NSW President’s Award for Excellence, the 2020 Australian Small Business Champion Award Finalist, the 2021 Australia’s well-known media ‘Accountants Daily’ the Accounting Firm of the Year Award Finalist and the 2022 Start-up Firm of the Year Award Finalist, and the 2023 Hong Kong-Australia Business Association Business Award Finalist.
Pitt Martin Group qualifications include over fifteen years of professional experience in accounting industry, Registered Australia Tax Agents, membership certification of the Chartered Accountants Australia and New Zealand (CA ANZ), certified External Examiner of the Law Societies of New South Wales, Victoria, and Western Australia Law Trust Accounts, membership certification of the Finance Brokers Association of Australia Limited (FBAA), Registered Agents of the Australian Securities and Investments Commission (ASIC), certified Advisor of accounting software such as XERO, QUICKBOOKS, MYOB, etc.
This content is for reference only and does not constitute advice on any individual or group’s specific situation. Any individual or group should take action only after consulting with professionals. Due to the timeliness of tax laws, we have endeavoured to provide timely and accurate information at the time of publication, but cannot guarantee that the content stated will remain applicable in the future. Please indicate the source when forwarding this content.
Experienced Tax Accountant and Business Advisor with a demonstrated history of working in the accounting and mortgage industry. Skilled in Tax, Accounting, Business Advisory, SMSF, Audit and Mortgage. Strong entrepreneurship professional with qualification Master of Professional Accounting, CA Public Practice, Registered Tax Agent, Registered ASIC Agent, NSW Law Society External Examiner, Trust Account Auditor and Diploma of Finanical Planning. Specialised in SME, tax planning and international tax, he helped client save ample money and create wealth.
COVID-19 and your business are now closely linked, as the virus has moved from an epidemic to a pandemic and businesses across Australia face the possibility of serious disruption. We are all aware of the impact of the coronavirus on the world, but what are the potential impacts on the Australian economy in 2020, and how can they be managed and reduced?
It
is unknown if Covid-19 will be long forgotten in 12 months or something that we
all have to accept as part of our lives. The truth is Australian businesses are
likely to face many challenges including cash flow issues, loss of trades,
supply shortages and changes to working arrangement for staffs which resulting
in operational disruption.
As the situation develops there is more uncertainty than assurance that the issue will be resolves at this time. It is important to keep yourself constantly updated with Government advice releases.
What to do?
There
is no need to be panic. Remember that tough times don’t last, tough people do. Businesses
should consider taking an immediate action to develop strategic plan to mitigate
the disruption and financial loss for immediate and future threats. It is vital
for businesses to identify all significant risks and potential opportunities it
may be exposed to during this time and develop an action plan to ensure
business continuity throughout.
Businesses
can assess and evaluate their trading performance, financial position and
current cash flow position via review of the relevant aspects. This process
will enable assessment of the business financially, the business challenges in
the short to medium term and thoroughly test financial forecast assumptions.
Constant
communication with clients, suppliers, employees, financiers and all other key
stakeholders regarding the development of this situation is important.
Government
The Australian Government is acting decisively in the national interest to address the potentially significant economic consequences of the virus, without a permanent or structural impact on the budget balance.
The
government has now announced an economic response totalling $17.6 billion
across the forward estimates, representing 0.9 percent of annual GDP to strengthen
the economy during this tough period.
The
package is intended to support confidence, employment and business continuity.
It is designed to support business investment, help small businesses manage
short-term cash flow challenges, provide targeted support to individuals and
assistance to the most severely affected communities and regions. It includes
cash grant of up to $25,000 for small businesses, $750 one-off payments for
potential consumers, and a significant temporary extension to the instant asset
write-off scheme (from $30,000 to $150,000)
The Australian Taxation Office (ATO) is also providing administrative relief for some tax obligations for people affected by the Coronavirus outbreak, on a case-by-case basis including potential deferrals of lodgements.
If you are unsure how COVID-19 will affect your cash flow, or whether your business qualifies for the Government’s stimulus measures, Pitt Martin Group can help you review and document your financial position, weigh up grants, write-offs and ATO relief, and prepare a practical action plan that supports your business continuity and recovery.
As Sydney tax accountants, we assist businesses with cash flow forecasts, stimulus measures and practical continuity advice.
Pitt Martin Group is a firm of Chartered Accountants, providing services including taxation, accounting, business consulting, self-managed superannuation funds, auditing and mortgage & finance. We spend hundreds of hours each year on training and researching new tax laws to ensure our clients can maximize legitimate tax benefit. Our contact information are phone +61292213345 or email info@pittmartingroup.com.au. Pitt Martin Group, Sydney tax accountants, is located in the convenient transportation hub of Sydney’s central business district. Our honours include the 2018 CPA NSW President’s Award for Excellence, the 2020 Australian Small Business Champion Award Finalist, the 2021 Australia’s well-known media ‘Accountants Daily’ the Accounting Firm of the Year Award Finalist and the 2022 Start-up Firm of the Year Award Finalist, and the 2023 Hong Kong-Australia Business Association Business Award Finalist.
Pitt Martin Group qualifications include over fifteen years of professional experience in accounting industry, Registered Australia Tax Agents, membership certification of the Chartered Accountants Australia and New Zealand (CA ANZ), certified External Examiner of the Law Societies of New South Wales, Victoria, and Western Australia Law Trust Accounts, membership certification of the Finance Brokers Association of Australia Limited (FBAA), Registered Agents of the Australian Securities and Investments Commission (ASIC), certified Advisor of accounting software such as XERO, QUICKBOOKS, MYOB, etc.
This content is for reference only and does not constitute advice on any individual or group’s specific situation. Any individual or group should take action only after consulting with professionals. Due to the timeliness of tax laws, we have endeavoured to provide timely and accurate information at the time of publication, but cannot guarantee that the content stated will remain applicable in the future. Please indicate the source when forwarding this content.
Experienced Tax Accountant and Business Advisor with a demonstrated history of working in the accounting and mortgage industry. Skilled in Tax, Accounting, Business Advisory, SMSF, Audit and Mortgage. Strong entrepreneurship professional with qualification Master of Professional Accounting, CA Public Practice, Registered Tax Agent, Registered ASIC Agent, NSW Law Society External Examiner, Trust Account Auditor and Diploma of Finanical Planning. Specialised in SME, tax planning and international tax, he helped client save ample money and create wealth.