Skip to main content Skip to search

Archives for Tax

Australian Tax Residency

Australian Tax Residency: ATO Travel Rules

If you travel overseas regularly for work, family or personal reasons, your Australian tax residency status and international travel records could become increasingly important when managing your tax affairs.

On 24 August 2026, the Australian Taxation Office (ATO) gazetted its latest passenger movements data-matching program. Under the program, the Department of Home Affairs is expected to provide the ATO with international travel information relating to approximately 115,000 individuals each year, covering the 2026–27 to 2028–29 income years.

The ATO can use this information to compare travel movements against existing tax records and identify potential discrepancies involving tax residency, income reporting, tax return lodgements and other tax obligations.

For Australians working overseas, people who have moved abroad and taxpayers who spend extended periods outside Australia, understanding the relevant tax residency rules and maintaining accurate travel records can help reduce uncertainty and support a consistent tax position.

What Is the ATO’s Passenger Movements Data-Matching Program?

The ATO’s passenger movements data-matching program allows it to obtain international travel information from the Department of Home Affairs and compare that information with its own records.

The information may include:

  • An individual’s name and date of birth
  • International arrival and departure dates
  • Passport details
  • Citizenship and visa status

The program is intended to help the ATO identify potential inconsistencies in tax registration, lodgement, income reporting, payment obligations and tax residency.

For example, if a taxpayer reports that they moved overseas on a particular date but passenger movement records indicate a different departure date, the ATO may seek further information to understand the discrepancy.

A difference in travel dates does not automatically mean that a taxpayer has made an error. However, accurate records can help explain the circumstances and support the position adopted in a tax return.

Why Is Australian Tax Residency Important?

Your Australian tax residency status can significantly affect how your income and other tax obligations are treated.

Australian tax residents are generally taxed on their worldwide income, while foreign residents are generally taxed on their Australian-sourced income, subject to applicable Australian tax law and any relevant double tax agreements.

Your residency status may also affect:

  • Income tax: Whether foreign employment income, overseas investments and other foreign income must be reported in Australia.
  • Tax-free threshold: Whether you qualify for the Australian tax-free threshold and how it applies to your circumstances.
  • Medicare levy: Whether you have Medicare levy obligations or qualify for an exemption.
  • Capital gains tax (CGT): How gains from Australian property and other assets are treated, including eligibility for certain exemptions.
  • Part-year residency: How your tax obligations are calculated if you become or cease to be an Australian tax resident during an income year.

If you have moved overseas, returned to Australia after an extended absence or maintained connections with Australia while living abroad, reviewing your residency position can be an important part of preparing your tax return.

For further information, refer to the Australian Taxation Office’s guidance on Australian residency for tax purposes.

Does Spending Time Overseas Automatically Make You a Foreign Tax Resident?

No. Spending time overseas does not automatically make you a foreign resident for Australian tax purposes.

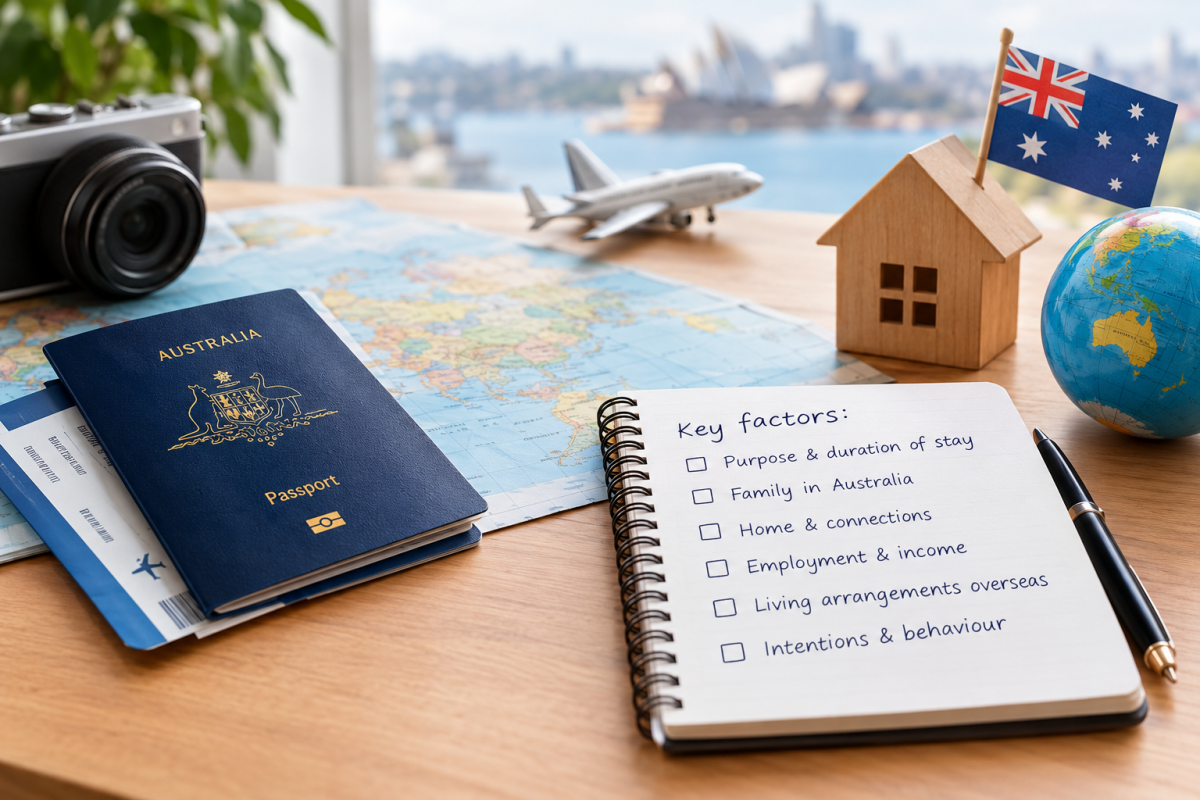
The ATO considers the relevant residency tests and the overall circumstances of each individual. Depending on the circumstances, relevant factors may include:

  • The purpose and intended duration of your overseas stay
  • Whether your spouse, children or other immediate family remain in Australia
  • Whether you maintain a home or other significant connections in Australia
  • Your employment arrangements and economic ties
  • Your living arrangements and connections in another country
  • Your intentions and behaviour before, during and after the move

The number of days you spend outside Australia may be relevant, but it does not determine your residency status in every case.

For example, someone working overseas temporarily may retain Australian tax residency, while another individual who establishes a life in another country may have different residency outcomes depending on their circumstances.

The key point is that Australian tax residency is determined by the applicable legal tests and your overall circumstances, not simply by the number of days you spend overseas.

Keeping a clear record of your travel dates, living arrangements and significant changes in circumstances can help support an assessment of your residency position.

When Can Your Overseas Travel History Affect Your Tax Return?

Your international travel history may be particularly relevant in several common situations.

1. Becoming or Ceasing to Be an Australian Tax Resident

If you become or cease to be an Australian tax resident during an income year, your arrival and departure dates may help establish the timeline of your move.

These dates can form part of the evidence supporting your residency position and may be relevant when determining how income is treated during different periods of the year.

They may also affect the calculation of your part-year tax-free threshold, where applicable.

However, departure from Australia does not, by itself, establish that you have ceased to be an Australian tax resident. Your living arrangements, intentions, family connections and other relevant circumstances must also be considered.

2. Working Overseas or Earning Foreign Income

If you regularly travel overseas for work, your travel records may help establish when you were in Australia and when you were working or staying overseas.

This can be relevant if you:

  • Work for an overseas employer
  • Undertake international assignments
  • Earn foreign employment income
  • Operate a business across multiple countries
  • Receive overseas investment income while maintaining Australian connections

Your Australian tax obligations will depend on factors such as your residency status, the nature and source of your income, and any applicable double tax agreement.

Maintaining accurate travel records alongside employment contracts, payslips and other supporting documents can help substantiate the tax treatment adopted in your return.

3. Selling an Australian Property After Moving Overseas

If you move overseas and later sell an Australian property, your tax residency history may affect the capital gains tax treatment of the sale.

Australian real estate can remain subject to Australian CGT even when the owner is a foreign resident. Foreign residency can also restrict access to certain concessions, including the main residence exemption, subject to applicable exceptions and transitional rules.

The dates you lived in your property, moved overseas, changed tax residency status and eventually sold the property may be relevant when assessing your CGT position.

If you are considering selling an Australian property while living overseas, obtaining tax advice before the sale can help you understand the potential tax consequences and any applicable restrictions.

For more information, see the ATO’s guidance on Capital Gains Tax.

How to Keep Accurate Overseas Travel Records

Maintaining accurate records is a practical way to support your Australian tax residency position and respond to questions if the ATO requests further information.

Consider the following steps.

Keep a Detailed Travel History

Record the departure and arrival dates for each international trip, including the relevant income year. Where necessary, distinguish between your physical travel dates and the dates you established or ceased a particular living arrangement.

Retain Supporting Documents

Keep relevant documents where available, including:

  • Flight itineraries and boarding passes
  • Passport records and travel confirmations
  • Employment contracts and overseas assignment details
  • Overseas accommodation or residential records
  • Documents relating to a move to or from Australia

These records may help explain your movements and provide context for your residency position.

Document Significant Changes in Your Circumstances

If you move overseas, relocate your family, change employers or establish a home in another country, retain records of those changes.

Travel dates alone may not establish your tax residency status, so documenting the wider circumstances can be valuable.

Review Your Tax Residency Before Lodging Your Return

Before lodging your Australian tax return, check that your travel dates and other relevant information are accurate and consistent with your supporting documents.

If you have spent substantial time overseas or your circumstances have changed during the year, consider reviewing your residency position before finalising your return.

Seek Professional Advice When Your Position Is Unclear

Australian tax residency can be complex, particularly when you maintain homes, family connections, employment or financial interests in more than one country.

An experienced tax adviser can help you assess the relevant residency tests, understand potential tax obligations and identify the records needed to support your position.

What Happens If Your Travel Records Do Not Match ATO Information?

If the dates reported to the ATO differ from passenger movement information, the discrepancy could prompt the ATO to request clarification or supporting evidence.

A discrepancy does not automatically mean you have breached your tax obligations. Differences may arise for legitimate reasons, and international travel dates are only one part of assessing tax residency.

However, having reliable records can make it easier to explain the difference and demonstrate how you arrived at your tax position.

This is particularly important if you have moved between countries, worked overseas for extended periods or have a residency position that depends on several factors.

Rather than waiting for a query, reviewing your records before lodging your tax return can help identify potential inconsistencies early.

Frequently Asked Questions About Australian Tax Residency and Overseas Travel

Does the ATO track overseas travel?

Under its passenger movements data-matching program, the ATO is expected to receive travel information from the Department of Home Affairs for approximately 115,000 individuals each year from 2026–27 to 2028–29. The information may be compared with tax records to identify potential discrepancies and compliance issues.

How long can I stay overseas without losing Australian tax residency?

There is no single period of overseas absence that automatically determines whether you remain an Australian tax resident. The applicable residency tests and your overall circumstances must be considered, including your intentions, family connections, living arrangements and ties to Australia.

Do Australian tax residents need to declare overseas income?

Australian tax residents are generally required to declare their worldwide income, including relevant foreign income, subject to applicable tax rules and any available relief. The treatment of specific income depends on your circumstances and any relevant double tax agreement.

Can I be an Australian tax resident while living overseas?

Yes. Living or working overseas does not automatically mean you cease to be an Australian tax resident. Your status depends on the relevant residency tests and the facts of your situation.

Why should I keep records of my arrival and departure dates?

Accurate travel records can help establish the timeline of your movements, support your residency assessment and explain differences between the information reported in your tax return and the information available to the ATO.

Can my tax residency affect the sale of my Australian home?

Yes. Your residency status can affect the availability of certain capital gains tax concessions, including the main residence exemption. The outcome depends on the applicable rules, the property and your individual circumstances. Seek advice before selling if you live overseas or expect to change residency status.

Need Help?

Pitt Martin Group’s Sydney tax accountants can assist with Australian tax residency assessments, international tax compliance, foreign income reporting, capital gains tax implications and tax return preparation. Whether you are relocating overseas, returning to Australia or concerned about discrepancies between your travel history and tax records, contact our experienced tax advisers for professional guidance tailored to your circumstances.

Pitt Martin Group is a firm of Chartered Accountants, providing services including taxation, accounting, business consulting, self-managed superannuation funds, auditing and mortgage & finance. We spend hundreds of hours each year on training and researching new tax laws to ensure our clients can maximize legitimate tax benefit. Our contact information are phone +61292213345 or email info@pittmartingroup.com.au. Pitt Martin Group, Sydney tax accountants, is located in the convenient transportation hub of Sydney’s central business district. Our honours include the 2018 CPA NSW President’s Award for Excellence, the 2020 Australian Small Business Champion Award Finalist, the 2021 Australia’s well-known media ‘Accountants Daily’ the Accounting Firm of the Year Award Finalist and the 2022 Start-up Firm of the Year Award Finalist, and the 2023 Hong Kong-Australia Business Association Business Award Finalist.

Pitt Martin Group qualifications include over fifteen years of professional experience in accounting industry, Registered Australia Tax Agents, membership certification of the Chartered Accountants Australia and New Zealand (CA ANZ), certified External Examiner of the Law Societies of New South Wales, Victoria, and Western Australia Law Trust Accounts, membership certification of the Finance Brokers Association of Australia Limited (FBAA), Registered Agents of the Australian Securities and Investments Commission (ASIC), certified Advisor of accounting software such as XERO, QUICKBOOKS, MYOB, etc.

This content is for reference only and does not constitute advice on any individual or group’s specific situation. Any individual or group should take action only after consulting with professionals. Due to the timeliness of tax laws, we have endeavoured to provide timely and accurate information at the time of publication, but cannot guarantee that the content stated will remain applicable in the future. Please indicate the source when forwarding this content.

By Alex Cramery @ Pitt Martin Tax

Read more
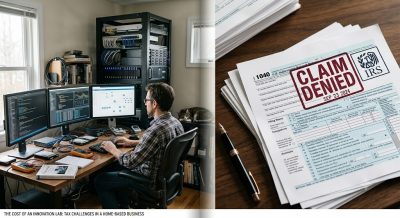
Work-Related Computer Deductions: What the Hartley Case Means for Taxpayers

工作相关电脑费用抵扣:Hartley 案对纳税人的启示

澳大利亚行政复审仲裁庭(Administrative Review Tribunal)近期的一项判决提醒纳税人,在申报工作相关电脑费用抵扣(work-related computer deductions)时需要特别注意:即使使用电脑设备进行的活动对雇主有帮助,也不代表相关费用就一定可以获得税务抵扣。

工作相关电脑费用抵扣:案件发生了什么?

近期的一项仲裁庭判决凸显了员工申报工作相关电脑费用时一个非常重要的问题:电脑设备及科技相关支出,并不会仅仅因为有关活动使雇主受益,就自动成为可抵扣费用。

在 Hartley and Commissioner of Taxation [2026] ARTA 1590 一案中,仲裁庭审理了一名高级 IT 销售员工是否可以就其家庭电脑“实验室”申报大额税务抵扣。

虽然该员工能够证明,他在家进行的多个项目获得了雇主的鼓励,并且确实使雇主受益,但仲裁庭最终仍然全额否决了相关税务抵扣。

这一判决再次说明,在判断一项工作相关支出是否可以抵税时,该项支出与员工实际赚取收入的工作职责之间是否存在足够紧密的联系至关重要。

Hartley 申报了哪些工作相关电脑费用?

Hartley 先生受雇于 Ericsson Australia,担任领域销售经理。

他认为自己的工作职责并不仅限于传统的销售活动。根据他提供的证据,其工作还涉及创新、寻找新的产品机会,以及在行业内提供专业思想和技术方面的领导。

在 2022 财政年度,Hartley 先生就其家中的电脑“实验室”申报了大额工作相关费用及资本折旧抵扣。

最终提交仲裁庭争议的抵扣总额为 31,870 澳元。其中大部分涉及科技和电脑相关支出,包括:

  • 数字存储设备
  • 电脑
  • 电脑显示器
  • 电脑软件
  • 各类电脑及科技服务订阅费用

澳大利亚税务局(ATO)在对 Hartley 先生的税务事项进行审计后,否决了这些抵扣。

纳税人随后对 ATO 的决定提出异议,但相关抵扣仍未获认可,因此案件最终提交至行政复审仲裁庭审理。

由于申报金额较大,而且涉及大量电脑及科技设备,该案对于因受雇工作而产生较高科技设备支出的纳税人具有一定参考意义。

电脑相关活动确实使雇主受益

Hartley 先生提供了有关其利用家庭电脑实验室完成多个项目的证据,包括:

  • 一个网络虚拟化项目,该项目后来由 Ericsson 进一步开发并推向市场;
  • 通过包括 Ericsson 在内的行业合作项目进行的云基础设施相关工作;以及
  • 视频接口技术相关工作,该技术曾出现在 Ericsson 的新闻稿中,之后也被应用于公司的业务。

仲裁庭认可 Hartley 先生具有专业技术知识,并且其高级职位确实涉及参与具有商业价值技术的开发。

但是,仅仅证明这些工作使雇主受益,并不足以证明相关支出可以获得税务抵扣。

为什么工作相关电脑费用抵扣被否决?

尽管上述活动确实给雇主带来了利益,仲裁庭最终仍然全额否决了有关抵扣。

案件的关键在于这些支出究竟是为了履行受雇工作职责,还是主要服务于纳税人自己的目的。

主要原因包括:

  1. 这些活动并非其职位所要求的工作。
    Ericsson 并没有要求 Hartley 先生进行这些工作,也没有允许他使用公司的设备完成有关活动。
  2. 纳税人本人可能保留有关工作的利益。
    证据显示,Hartley 先生选择在家中进行部分工作,其中一个原因是,如果日后离开 Ericsson,他可能可以保留有关开发成果的所有权。
  3. 一般性的专业兴趣并不足以产生税务抵扣。
    仲裁庭认为,这些活动更接近于维持个人的一般专业水平及其对 IT 技术的个人兴趣,而不是履行其实际受雇工作职责。

仲裁庭引用了澳大利亚高等法院 Federal Commissioner of Taxation v Hatchett [1971] HCA 47 一案。

该案所确立的原则说明,仅仅因为雇主鼓励某项活动,并不会因此自动使有关支出成为可抵扣的工作费用。

Hartley 案对工作相关电脑费用抵扣意味着什么?

ATO 一直将工作相关费用抵扣作为税务合规关注领域之一,而金额较大或不寻常的抵扣申报尤其可能受到关注。

Hartley 案再次提醒纳税人,在判断有关支出是否可以抵税时,仅仅能够证明以下情况通常并不足够:

  • 设备是在家中用于有关活动;
  • 雇主知道或者鼓励有关活动;
  • 有关工作使雇主获得利益;或
  • 纳税人使用有关设备提高自己的专业技能或维持行业知识。

纳税人的实际受雇工作职责以及产生有关支出的目的,仍然是判断费用能否获得税务抵扣的重要因素。

对于申报大额电脑、显示器、存储设备、软件或者在线电脑服务费用的员工来说,这一点尤其值得注意。

给纳税人的重要提示

在申报工作相关电脑费用抵扣之前,纳税人应考虑有关支出是否真正与其目前赚取收入的工作职责有关,而不是仅仅与更广泛的专业兴趣或者个人项目有关。

Hartley 案说明,即使员工进行的工作最终确实使雇主获得了明显利益,如果有关活动超出了员工实际受雇工作职责的范围,相关费用仍然可能无法获得税务抵扣。

对于金额较大的申报,企业和员工应保存适当的记录,并认真考虑以下几者之间的联系:

有关支出、实际工作职责以及所赚取的收入。

常见问题

Hartley and Commissioner of Taxation [2026] ARTA 1590 一案的结果是什么?

行政复审仲裁庭维持了 ATO 的决定,否决 Hartley 先生就其家庭电脑“实验室”申报的 31,870 澳元费用抵扣。仲裁庭认为,这些费用与其实际受雇工作职责之间没有足够紧密的联系。

如果雇主鼓励某项活动,相关费用就可以抵税吗?

不一定。仲裁庭确认,仅仅因为雇主鼓励某项活动或者从该活动中获得利益,本身并不足以支持税务抵扣。有关支出必须与员工履行其具体工作职责具有足够的联系。

仲裁庭参考了哪个重要判例?

仲裁庭引用了 Federal Commissioner of Taxation v Hatchett [1971] HCA 47。

该案是有关自我教育及工作相关费用税务抵扣范围的一项重要判例。

从这个判决中应该注意什么?

在申报大额工作相关费用之前,应判断有关支出是否真正与纳税人的实际工作职责相关,而不能仅仅因为有关支出对工作有帮助、受到雇主鼓励或者有利于个人专业发展,就认为一定可以抵税。

同时,还应考虑相关工作成果最终由谁拥有和享有。

使用电脑是否与实际工作职责直接相关?

这是判断费用能否获得税务抵扣的重要问题。仅仅出于一般性的专业兴趣使用电脑,可能不足以支持税务抵扣。

需要专业税务协助?

如果您不确定电脑、科技设备或其他工作相关费用是否可以获得税务抵扣,Pitt Martin Group 皮特马丁会计师事务所可以协助您分析有关费用与赚取收入活动之间的联系、判断是否需要进行私人及工作用途的合理分摊,并了解相关税务记录保存要求。

皮特马丁会计师事务所 Pitt Martin Group 是一家提供税务,会计,生意咨询,自管养老金,审计及贷款等综合性服务的经澳洲特许会计师协会认证的注册会计师事务所。我们每年会花上几百个小时去研究新的税法,以保证我们的客户可以最大化合理避税。我们的中文联系方式是 Robert Liu +61292213345 或邮件 info@pittmartingroup.com.au。皮特马丁会计师事务所Pitt Martin Group坐落在交通便利的悉尼市市中心,是一家拥有可以说中文合伙人的悉尼会计师事务所。我们的荣誉包括2018年CPA新州首席优秀奖, 2020年澳大利亚小生意年度冠军入围奖, 2021年澳洲知名媒体《每日会计师》年度最佳会计师事务所冠军入围奖,2022年最佳会计师事务所新人入围奖和2023香港澳大利亚商业协会最佳积极生意入围奖。

皮特马丁会计师事务所 Pitt Martin Group资质包括超过十五年的从业经验,澳大利亚税务注册代理,澳大利亚与新西兰特许会计师协会(CAANZ)会员,新州、维州和西澳律师协会信托账户 (Trust Account) 认证审计师,澳大利亚金融贷款经纪人协会(FBAA)执业认证会员,澳大利亚证券及投资委员会注册代理,XERO, QUICKBOOKS, MYOB等会计软件授权单位及认证顾问。

本文内容仅供参考,不构成对任何个人或团体的具体情况而形成建议。任何个人或团体应该在征求专业人士的意见后方可采取行动。由于税法的时效性,我们在发布时已致力于提供及时、准确的信息,但不能保证所称述的内容在今后任然可以适用。转发该文内容请注明出处。

By Robert Liu @ Pitt Martin Tax

Read more
Work-Related Computer Deductions: What the Hartley Case Means for Taxpayers

Work-Related Computer Deductions: What the Hartley Case Means for Taxpayers

A recent Tribunal decision highlights an important point for taxpayers claiming work-related computer deductions: using computer equipment for activities that benefit your employer does not automatically mean the related expenses are tax deductible.

Work-Related Computer Deductions: What Happened?

A recent Tribunal decision highlights an important issue for employees claiming work-related computer deductions: computer equipment and technology expenses are not automatically deductible simply because the activities benefit an employer.

In Hartley and Commissioner of Taxation [2026] ARTA 1590, the Tribunal considered whether a senior IT sales employee could claim substantial deductions for a home computer “lab”. Although the employee demonstrated that several projects undertaken at home were encouraged by and benefited his employer, the Tribunal ultimately denied the deductions in full.

The decision is a useful reminder that the connection between an expense and an employee’s actual income-earning duties is critical when determining whether a work-related deduction is available.

What Were the Work-Related Computer Deductions?

Mr Hartley was employed by Ericsson Australia as a Domain Sales Manager. He argued that his employment involved responsibilities beyond traditional sales activities. According to his evidence, his role also involved innovation, identifying new product opportunities and providing thought leadership within the industry.

During the 2022 income year, Mr Hartley claimed a substantial amount of work-related and capital allowance deductions associated with his home computer “lab”.

The total amount ultimately disputed before the Tribunal was $31,870. Most of the claim related to technology and computing expenses, including:

  • Digital storage devices
  • Computers
  • Computer monitors
  • Computer software
  • Subscriptions to various computing services

The ATO denied the claims during its audit of Mr Hartley’s tax affairs. The taxpayer subsequently objected to the decision, but the deductions remained denied. The matter was then considered by the Tribunal.

The size and nature of the claim made the case particularly relevant for taxpayers who incur significant technology costs in connection with their employment.

The computer activities benefited the employer

Mr Hartley provided evidence of several projects undertaken using his home computer lab. These included:

  • A network virtualisation project that was later developed and marketed by Ericsson;
  • Cloud infrastructure work undertaken through an industry collaboration involving Ericsson; and
  • Work on video interface technology that was featured in an Ericsson press release and later deployed in the business.

The Tribunal accepted that Mr Hartley had specialised expertise and that his senior role involved contributing to the development of marketable technologies.

However, this was not enough to establish that the expenses were deductible.

Why were the work-related computer deductions denied?

Despite that, the Tribunal denied the deductions in full. The reasoning turned on whose purpose the expenditure served:

  1. The activities weren’t required by the role. Ericsson neither mandated the work nor permitted Mr. Hartley to use company equipment to perform it.
  2. The taxpayer stood to keep the benefit. Evidence suggested the work was done at home partly so Mr. Hartley could retain ownership of any development if he left Ericsson.
  3. General professional interest isn’t enough. The Tribunal found the activities were closer to maintaining general professional standing and personal interest in IT than to discharging his actual employment duties.

Citing the High Court’s decision in Federal Commissioner of Taxation v Hatchett [1971] HCA 47, the Tribunal confirmed that employer encouragement of an activity without more does not convert it into a deductible work expense.

What Does the Hartley Case Mean for Work-Related Computer Deductions?

The ATO has repeatedly flagged work-related deductions as a compliance priority, and large or unusual claims attract particular scrutiny. Hartley is a useful reminder of where the line sits:

For businesses and taxpayers, it is not enough to demonstrate that:

  • the equipment is used at home;
  • the employer is aware of or encourages the activity;
  • the employer benefits from the work; or
  • the taxpayer uses the equipment to develop professional skills or maintain industry knowledge.

The nature of the taxpayer’s actual employment duties and the purpose for which the expenditure was incurred remain important considerations.

This is particularly relevant where an employee is claiming significant amounts for computers, monitors, storage equipment, software or online computing services.

Key takeaway for taxpayers

Before claiming a work-related computer deduction, taxpayers should consider whether the expense genuinely relates to their current income-producing duties rather than broader professional interests or personal projects.

The Hartley decision demonstrates that even substantial work that ultimately benefits an employer may not qualify for a deduction if it falls outside the employee’s actual employment responsibilities.

For significant claims, businesses and employees should retain appropriate records and carefully consider the connection between the expense, the employment duties and the income being earned.

Frequently Asked Questions

What was the outcome of Hartley and Commissioner of Taxation [2026] ARTA 1590?

The Administrative Review Tribunal upheld the ATO’s decision to deny Mr Hartley’s $31,870 claim for home computer “lab” expenses, finding the costs were not sufficiently connected to his actual employment duties.

Does employer encouragement make a work-related expense deductible?

No. The Tribunal confirmed that an employer encouraging or benefiting from an activity is not, on its own, enough to support a deduction. The expense must relate to the performance of the employee’s specific duties.

What case law did the Tribunal rely on?

The Tribunal cited Federal Commissioner of Taxation v Hatchett [1971] HCA 47, a longstanding authority on the limits of deductibility for self-education and work-related expenditure.

What should you take from this decision?

Before claiming large work-related deductions, test whether the expense was actually required to perform the client’s job not merely useful, encouraged, or professionally beneficial. Also consider who ultimately retains the benefit of any work product created.

Is the computer use directly connected to your employment duties?

A general professional interest may not be enough.

Need Help?

If you are unsure whether your computer, technology or other work-related expenses are deductible, Pitt Martin Group can help you assess the connection between the expense and your income-earning activities, determine any required apportionment, and understand the record-keeping requirements.

As Sydney tax accountants, we assist individuals and businesses with work-related deductions, tax compliance and practical tax advice.

Pitt Martin Group is a firm of Chartered Accountants, providing services including taxation, accounting, business consulting, self-managed superannuation funds, auditing and mortgage & finance. We spend hundreds of hours each year on training and researching new tax laws to ensure our clients can maximize legitimate tax benefit. Our contact information are phone +61292213345 or email info@pittmartingroup.com.au. Pitt Martin Group, Sydney tax accountants, is located in the convenient transportation hub of Sydney’s central business district. Our honours include the 2018 CPA NSW President’s Award for Excellence, the 2020 Australian Small Business Champion Award Finalist, the 2021 Australia’s well-known media ‘Accountants Daily’ the Accounting Firm of the Year Award Finalist and the 2022 Start-up Firm of the Year Award Finalist, and the 2023 Hong Kong-Australia Business Association Business Award Finalist.

Pitt Martin Group qualifications include over fifteen years of professional experience in accounting industry, Registered Australia Tax Agents, membership certification of the Chartered Accountants Australia and New Zealand (CA ANZ), certified External Examiner of the Law Societies of New South Wales, Victoria, and Western Australia Law Trust Accounts, membership certification of the Finance Brokers Association of Australia Limited (FBAA), Registered Agents of the Australian Securities and Investments Commission (ASIC), certified Advisor of accounting software such as XERO, QUICKBOOKS, MYOB, etc.

This content is for reference only and does not constitute advice on any individual or group’s specific situation. Any individual or group should take action only after consulting with professionals. Due to the timeliness of tax laws, we have endeavoured to provide timely and accurate information at the time of publication, but cannot guarantee that the content stated will remain applicable in the future. Please indicate the source when forwarding this content.

By Nora Pham @ Pitt Martin Tax

Read more

高等法院进一步明确信托分配规则

澳大利亚高等法院最近作出了一项重要判决,对于采用全权信托(discretionary trusts)和公司受益人(corporate beneficiaries)的私人商业集团具有重要影响。

在 Commissioner of Taxation v Bendel [2026] HCA 18 一案中,高等法院于2026年6月10日作出判决,否定了ATO长期以来的立场,即信托欠付公司受益人的未支付现有权利(Unpaid Present Entitlement,简称 UPE),会自动被视为 Division 7A 所规定的贷款。

Division 7A 旨在防止私人公司通过付款、贷款或债务豁免等方式向股东或其关联方提供利益,却没有产生相应的税务后果。如果 Division 7A 适用,相关利益可能会被视为未附带抵免额的股息(unfranked dividend)。

Bendel 判决对 UPE 意味着什么?

全权信托广泛应用于私人企业和投资架构中。信托可以将收入分配给公司受益人,使相关收入按照适用的公司税率纳税,同时现金仍保留在信托中,用于营运资金、投资或业务发展。

过去,ATO 认为,如果公司受益人应得的信托分配一直没有收到,该 UPE 可能构成 Division 7A 下的贷款。因此,企业通常需要建立符合 Division 7A 要求的贷款安排、按照基准利率计算利息,并进行每年的最低还款,以避免产生未附带抵免额的视同股息。

现在,高等法院已经确认,仅仅因为公司受益人没有要求信托支付款项,并不会自动使未支付的信托分配构成贷款。

对于过去将信托分配保留在信托中,而没有将现金转给公司受益人的私人商业集团而言,这是一个重要变化。这一判决可能减少部分集团将 UPE 作为 Division 7A 贷款处理的需要,并提供更大的确定性,同时可能降低行政和税务合规成本。

不过,最终结果仍然取决于每个信托具体的事实和安排。

现有的 Division 7A 贷款怎么办?

高等法院作出判决后,ATO 于2026年6月26日发布了 Decision Impact Statement,确认其通常会根据高等法院的判决执行相关税法。

需要特别注意的是,企业不能简单地认为现有的 Division 7A 贷款安排现在可以取消。

如果 UPE 已经通过某种方式被处理,并因此形成正式的 Division 7A 贷款,那么该贷款仍然具有其法律上的贷款性质。适用的利息和最低年度还款要求通常仍需继续履行,直到贷款偿还完毕或相关贷款期限结束。

因此,拥有现有 Division 7A 贷款协议的企业,在作出任何调整之前都应该仔细审查现有安排。

Bendel 是否消除了其他税务风险?

并没有。Bendel 判决虽然为 UPE 提供了重要的明确性,但并没有消除所有 Division 7A 或其他税务完整性方面的风险。

例如,如果信托将收入分配给公司受益人,但之后信托资金被用于向该公司的股东或其关联方提供付款、贷款或其他利益,其他 Division 7A 规定仍可能适用。

Section 100A 也仍然需要考虑。如果收入名义上分配给一名受益人,但根据 reimbursement agreement,该收入所产生的实际经济利益由另一方享有,那么 Section 100A 在特定情况下可能适用。

这些规定的适用高度依赖具体事实。因此,Bendel 不应被理解为对 Division 7A、Section 100A 或其他税务完整性规定提供全面豁免。

私人商业集团现在应该做什么?

Bendel 判决为私人商业集团提供了一个很好的机会,可以重新审视其信托架构以及 UPE 的处理方式。

拥有公司受益人的企业应考虑:

  • 信托分配决议是否已经正确准备并妥善记录;
  • UPE 是否已经正确记录在会计账目中;
  • 任何 UPE 是否已经在之后被转换为贷款;
  • 信托资金是否曾被用于股东或其关联方的利益;以及
  • Section 100A 或其他 Division 7A 规定是否可能适用于相关安排。

对于根据 ATO 过去关于 UPE 的处理方式建立的安排,这项审查尤其重要。

拟议中的全权信托30%最低税率

Bendel 判决还需要结合政府拟议中的全权信托税务改革来看待。

政府拟议从2028年7月1日起,对全权信托的应税收入实施30%的最低税率,但部分特定情况将被排除在外。在拟议框架下,信托层面缴纳的税款通常不会以与其他受益人相同的方式,为公司受益人提供可退还或不可退还的税务抵免。

Treasury 最近针对拟议信托税务改革进行的咨询,也讨论了是否应让 Division 7A 适用于未支付的信托分配。这些改革目前尚未成为法律,但未来可能会显著改变私人商业集团处理信托分配和 UPE 的方式。

展望未来

Bendel 判决为现行 Division 7A 规则提供了令人欢迎的明确性,尤其是对于使用全权信托和公司受益人的私人商业集团而言。

与此同时,拟议中的信托税务改革意味着企业不应仅仅根据 Bendel 判决作出长期税务安排。现在审查现有的信托分配、UPE 和 Division 7A 安排,可以帮助企业及时发现潜在问题,并为2028年7月1日之前可能发生的税务变化做好准备。

如果您希望进一步了解 Bendel 判决、Division 7A 或拟议中的全权信托30%最低税率将如何影响您的商业集团,欢迎联系我们,根据您的具体情况进行讨论。

皮特马丁会计师事务所 Pitt Martin Group 是一家提供税务,会计,生意咨询,自管养老金,审计及贷款等综合性服务的经澳洲特许会计师协会认证的注册会计师事务所。我们每年会花上几百个小时去研究新的税法,以保证我们的客户可以最大化合理避税。我们的中文联系方式是 Robert Liu +61292213345 或邮件 info@pittmartingroup.com.au。皮特马丁会计师事务所Pitt Martin Group坐落在交通便利的悉尼市市中心,是一家拥有可以说中文合伙人的会计师事务所。我们的荣誉包括2018年CPA新州首席优秀奖, 2020年澳大利亚小生意年度冠军入围奖, 2021年澳洲知名媒体《每日会计师》年度最佳会计师事务所冠军入围奖,2022年最佳会计师事务所新人入围奖和2023香港澳大利亚商业协会最佳积极生意入围奖。

皮特马丁会计师事务所 Pitt Martin Group资质包括超过十五年的从业经验,澳大利亚税务注册代理,澳大利亚与新西兰特许会计师协会(CAANZ)会员,新州、维州和西澳律师协会信托账户 (Trust Account) 认证审计师,澳大利亚金融贷款经纪人协会(FBAA)执业认证会员,澳大利亚证券及投资委员会注册代理,XERO, QUICKBOOKS, MYOB等会计软件授权单位及认证顾问。

本文内容仅供参考,不构成对任何个人或团体的具体情况而形成建议。任何个人或团体应该在征求专业人士的意见后方可采取行动。由于税法的时效性,我们在发布时已致力于提供及时、准确的信息,但不能保证所称述的内容在今后任然可以适用。转发该文内容请注明出处。

By Yvonne Shao @ Pitt Martin Tax

Read more

Bendel Division 7A Decision: High Court Clarifies UPE Rules

The High Court’s Bendel decision on Division 7A is an important development for private business groups using discretionary trusts and corporate beneficiaries.

In Commissioner of Taxation v Bendel [2026] HCA 18, decided on 10 June 2026, the High Court rejected the ATO’s longstanding position that an unpaid present entitlement (UPE) owed by a trust to a corporate beneficiary will automatically be treated as a loan for Division 7A purposes.

Division 7A is designed to prevent private companies from providing benefits to shareholders or their associates through payments, loans or debt forgiveness without appropriate tax consequences. Where Division 7A applies, the benefit may be treated as an unfranked dividend.

What does the Bendel decision mean for UPEs?

Discretionary trusts are commonly used in private business and investment structures. A trust may distribute income to a corporate beneficiary so the income is taxed at the applicable company tax rate, while the cash remains in the trust to fund working capital, investments or business growth.

Historically, the ATO considered that where the corporate beneficiary’s entitlement remained unpaid, the UPE could constitute a Division 7A loan. Businesses therefore often needed to enter into complying Division 7A loan arrangements, charge the benchmark interest rate and make minimum yearly repayments to avoid a deemed unfranked dividend.

The High Court has now confirmed that an unpaid trust distribution does not, by itself, constitute a loan merely because the corporate beneficiary has not demanded payment.

This is significant for private groups that have retained trust distributions within the trust rather than transferring the cash to the corporate beneficiary. The decision may reduce the need for some groups to treat UPEs as Division 7A loans, providing greater certainty and potentially reducing administration and compliance costs.

However, the outcome will still depend on the specific facts and arrangements of each trust.

What about existing Division 7A loans?

Following the decision, the ATO released a Decision Impact Statement on 26 June 2026, confirming that it will generally administer the law consistently with the High Court’s decision.

Importantly, businesses should not assume that existing Division 7A loan arrangements can simply be cancelled.

Where a UPE has already been dealt with in a way that created a formal Division 7A loan, the loan remains a loan according to its legal character. Any applicable interest and minimum yearly repayment requirements will generally continue until the loan is repaid or the relevant loan term ends.

Therefore, businesses with existing Division 7A loan agreements should review their arrangements carefully before making any changes.

Does Bendel remove other tax risks?

No. The Bendel decision provides important clarity on UPEs, but it does not remove all Division 7A or tax integrity concerns.

For example, where a trust distributes income to a corporate beneficiary but the trust funds are subsequently used to provide a payment, loan or other benefit to a shareholder of the company or an associate, other Division 7A provisions may still apply.

Section 100A also remains relevant. These rules can potentially apply where income is appointed to one beneficiary but, under a reimbursement agreement, the economic benefit of that income is enjoyed by another party.

The application of these provisions depends heavily on the facts. The Bendel decision should therefore not be treated as a blanket exemption from Division 7A, section 100A or other tax integrity rules.

What should private groups do now?

The Bendel decision provides a good opportunity for private groups to review their trust structures and how UPEs have been managed.

Businesses with corporate beneficiaries should consider whether:

  • trust distribution resolutions have been properly prepared and documented;
  • UPEs have been correctly recorded in the accounting records;
  • any UPEs have subsequently been converted into loans;
  • trust funds have been used for the benefit of shareholders or their associates; and
  • section 100A or other Division 7A provisions may apply.

This review is particularly important for arrangements established under the ATO’s previous approach to UPEs.

Proposed 30% minimum tax on discretionary trusts

The Bendel decision also needs to be considered alongside the Government’s proposed changes to the taxation of discretionary trusts.

The Government has proposed a 30% minimum tax rate on the taxable income of discretionary trusts from 1 July 2028, subject to certain exclusions. Under the proposed framework, tax paid at the trust level would generally not provide a refundable or non-refundable tax credit to corporate beneficiaries in the same way it may for other beneficiaries.

Treasury’s recent consultation on the proposed trust tax reforms has also considered whether Division 7A should apply to unpaid distributions. These proposals are not yet law, but they could significantly change the way private groups approach trust distributions and UPEs in the future.

Looking ahead

The Bendel decision provides welcome clarity under the current Division 7A rules, particularly for private groups using discretionary trusts and corporate beneficiaries.

At the same time, the proposed trust tax reforms mean businesses should not make long-term decisions based on Bendel alone. Reviewing existing trust distributions, UPEs and Division 7A arrangements now can help identify issues and prepare for potential changes before 1 July 2028.

Please let us know if you would like to discuss how the Bendel decision, Division 7A or the proposed 30% minimum tax on discretionary trusts may affect your group.

Pitt Martin Group is a firm of Chartered Accountants, providing services including taxation, accounting, business consulting, self-managed superannuation funds, auditing and mortgage & finance. We spend hundreds of hours each year on training and researching new tax laws to ensure our clients can maximize legitimate tax benefit. Our contact information are phone +61292213345 or email info@pittmartingroup.com.au. Pitt Martin Group is located in the convenient transportation hub of Sydney’s central business district. Our honours include the 2018 CPA NSW President’s Award for Excellence, the 2020 Australian Small Business Champion Award Finalist, the 2021 Australia’s well-known media ‘Accountants Daily’ the Accounting Firm of the Year Award Finalist and the 2022 Start-up Firm of the Year Award Finalist, and the 2023 Hong Kong-Australia Business Association Business Award Finalist.

Pitt Martin Group qualifications include over fifteen years of professional experience in accounting industry, Registered Australia Tax Agents, membership certification of the Chartered Accountants Australia and New Zealand (CA ANZ), certified External Examiner of the Law Societies of New South Wales, Victoria, and Western Australia Law Trust Accounts, membership certification of the Finance Brokers Association of Australia Limited (FBAA), Registered Agents of the Australian Securities and Investments Commission (ASIC), certified Advisor of accounting software such as XERO, QUICKBOOKS, MYOB, etc.

This content is for reference only and does not constitute advice on any individual or group’s specific situation. Any individual or group should take action only after consulting with professionals. Due to the timeliness of tax laws, we have endeavoured to provide timely and accurate information at the time of publication, but cannot guarantee that the content stated will remain applicable in the future. Please indicate the source when forwarding this content.

By Yvonne Shao @ Pitt Martin Tax

Read more
federal budget 2026-27

2026年联邦预算税务更新

2026年联邦预算税务更新对联邦政府此前公布的多项重要税务改革方案进行了调整。联邦预算于2026年5月12日公布,其中包括资本利得税(CGT)、自由裁定信托(Discretionary Trust)及自管养老金基金(SMSF)等多项重大改革。

预算公布后,政府根据企业、税务专业人士及行业团体的反馈,对部分重要提案进行了修订。因此,本次2026年联邦预算税务更新,为纳税人、投资者、企业主及信托受托人在未来税务规划方面提供了重要参考。

联邦预算税务更新:资本利得税(CGT)

本次预算中最受关注的改革之一,是拟调整现行的50%资本利得税折扣(CGT Discount)。

根据原提案,个人及信托未来将不再适用50%的CGT折扣,而改为采用资本利得指数化(Indexation)制度。同时,自2027年7月1日起(有限例外情况除外),资本利得还将适用最低30%的税率。

目前,政府已进一步宣布推出创新企业资本利得税优惠(Innovative Business CGT Concession),旨在鼓励更多资金投资澳洲初创企业。

符合资格的投资者、创始人及员工持股计划(ESS)参与者,未来仍有机会继续享有50%的CGT折扣。政府亦已发布咨询文件,就该优惠制度的具体运作方式征求意见。

此外,小型企业亦将受惠于另一项改革建议。

自2027年7月1日起,适用于**50% Active Asset Reduction(50%活跃资产减免)**的小型企业营业额门槛,将由目前的200万澳元提高至1,000万澳元。

不过,其余三项小型企业CGT优惠将维持不变,包括:

  • 15年免税优惠(15-Year Exemption)
  • 退休豁免(Retirement Exemption)
  • 小型企业递延优惠(Small Business Rollover)

这些优惠仍继续适用现行200万澳元营业额测试。不过,即使营业额超过200万澳元,只要符合现行600万澳元净资产价值测试(Net Asset Value Test),企业仍可能符合相关优惠资格。

联邦预算税务更新:自由裁定信托(Discretionary Trust)

原预算提案建议,自2028年7月1日起,自由裁定信托适用最低30%的税率。

根据原方案,许多遗嘱信托(Testamentary Trust)亦会受到新规则影响。

现时,政府已调整有关政策,计划豁免所有真正为遗产继承目的而设立的遗嘱信托(Genuine Testamentary Trust)。

不过,该豁免仅适用于来自已故人士遗产资产所产生的收入。

此外,对于2028年7月1日或之后设立的遗嘱自由裁定信托(Testamentary Discretionary Trust),若希望享有豁免资格,则其受益人仅可包括自然人及免所得税实体(Income Tax-Exempt Entities)。

联邦预算税务更新:SMSF(自管养老金基金)

政府亦宣布对自管养老金基金(SMSF)相关规定作出调整。

其中一项重要改革涉及SMSF借款规则。

根据拟议改革,SMSF未来将不得再透过**有限追索借款安排(Limited Recourse Borrowing Arrangement,LRBA)**购买住宅物业(Residential Property)。

现有的LRBA借款预计将适用祖父条款(Grandfathering Provisions),因此不会受到新规定影响。

然而,当新法正式实施后,SMSF将不能再透过LRBA为购买住宅物业进行新的借款安排。

接下来应该怎么做?

上述税务改革建议可能影响投资决策、企业架构、遗产规划以及退休金策略。

虽然政府已针对多项措施进行了修订,但在相关法案正式通过国会之前,未来仍可能进一步调整。

如果您拥有企业、通过信托进行投资,或管理自管养老金基金(SMSF),现在正是检视自身税务安排的良好时机。及早了解拟议规则,有助于提前规划并降低未来潜在影响。

我们将持续关注相关立法进展,并在有进一步消息时第一时间提供最新资讯。

如您希望了解上述改革对您个人、企业或SMSF可能产生的影响,欢迎随时联系我们的专业团队。

需要协助?

与我们这样的专业税务会计师和贷款经纪人合作,您可以放心,我们的团队可以提供针对性建议,确保贷款结构既能保护您的税务最大化扣除,同时避免错误的风险,从而让您更加安心,并更好地规划财务。

皮特马丁会计师事务所 Pitt Martin Group 是一家提供税务,会计,生意咨询,自管养老金,审计及贷款等综合性服务的经澳洲特许会计师协会认证的注册会计师事务所。我们每年会花上几百个小时去研究新的税法,以保证我们的客户可以最大化合理避税。我们的中文联系方式是 Robert Liu +61292213345 或邮件 info@pittmartingroup.com.au。皮特马丁会计师事务所Pitt Martin Group坐落在交通便利的悉尼市市中心,是一家拥有可以说中文合伙人的会计师事务所。我们的荣誉包括2018年CPA新州首席优秀奖, 2020年澳大利亚小生意年度冠军入围奖, 2021年澳洲知名媒体《每日会计师》年度最佳会计师事务所冠军入围奖,2022年最佳会计师事务所新人入围奖和2023香港澳大利亚商业协会最佳积极生意入围奖。

皮特马丁会计师事务所 Pitt Martin Group资质包括超过十五年的从业经验,澳大利亚税务注册代理,澳大利亚与新西兰特许会计师协会(CAANZ)会员,新州、维州和西澳律师协会信托账户 (Trust Account) 认证审计师,澳大利亚金融贷款经纪人协会(FBAA)执业认证会员,澳大利亚证券及投资委员会注册代理,XERO, QUICKBOOKS, MYOB等会计软件授权单位及认证顾问。

本文内容仅供参考,不构成对任何个人或团体的具体情况而形成建议。任何个人或团体应该在征求专业人士的意见后方可采取行动。由于税法的时效性,我们在发布时已致力于提供及时、准确的信息,但不能保证所称述的内容在今后任然可以适用。转发该文内容请注明出处。

By Robert Liu @ Pitt Martin Tax

Read more

个人服务收入安排:ATO加强利润分配风险审查

澳大利亚税务局(ATO)正在加强对个人通过自身技能、知识和专业能力取得收入时,其收入安排及分配方式的关注。

近期,ATO发布了实务合规指南 PCG 2025/5(Practical Compliance Guideline PCG 2025/5),明确了其对于“个人服务收入转移”(alienation of Personal Services Income, PSI)安排的合规审查方式。

这类安排通常是指个人通过自身劳动、技能或专业能力赚取的收入,并非直接作为个人收入申报,而是通过公司、信托或其他实体接收和分配。

通过公司或信托开展业务在澳大利亚非常普遍,并且在很多情况下具有合理的商业目的,例如资产保护、经营灵活性以及未来继承规划等。

但是,如果企业收入主要来自某一个人的个人服务,那么企业主需要重新审视目前的利润分配安排是否符合ATO最新的监管要求。

为什么ATO关注个人服务收入安排?

许多专业人士和企业主选择通过公司或信托结构经营业务,这通常具有合理的商业原因。

然而,ATO关注的是以下情况:收入主要来源于某个人的技能、声誉或劳动,但这些收入却被转移至其他实体或个人名下,主要目的是获得更低的整体税务结果。

个人服务收入(PSI)相关税务规则的目的,是确保主要由个人劳动和专业能力产生的收入,能够合理地归属于实际提供服务的个人进行纳税。

虽然部分企业可能符合个人服务业务(Personal Services Business, PSB)的条件,因此不适用于部分PSI收入归属规则,但这并不代表该安排一定不会受到ATO审查。

ATO同时指出,如果某项安排主要是为了获取税务利益,则一般反避税规则(Part IVA)仍可能适用。

如果Part IVA被应用,纳税人可能面临额外税务负担、罚款以及利息费用。

哪些安排通常被认为风险较低?

根据PCG 2025/5,ATO会重点考虑提供个人服务的个人,是否获得了由其工作产生的大部分经济利益。

以下类型的安排通常更可能被认为属于较低风险:

  • 个人通过工资、薪金、奖金、董事费或合理的信托分配方式获得大部分经济利益;
  • 公司保留利润具有真实且明确的短期商业目的;
  • 支付给家庭成员或关联方的金额,与其实际提供的服务相匹配,并且金额合理。

例如,公司为了购买设备、扩大业务运营或满足短期商业需求而保留利润,如果企业能够提供明确的商业依据,并且实际按照计划使用这些资金,该安排通常更容易被接受。

哪些安排可能引起ATO关注?

ATO已经指出,以下行为可能增加税务审查风险:

  • 将收入分配给对收入产生没有实际贡献或贡献很少的家庭成员或关联方;
  • 公司长期保留大量利润,但没有真实的商业目的;
  • 主要因为某些实体或受益人的税率较低,或者拥有税务亏损,而将个人服务收入产生的利润转移给这些实体或受益人。

ATO关注的核心问题,是最终获得经济利益的人,与实际创造收入的人之间是否存在合理联系。

如果提供服务的个人与最终承担税务责任的人之间存在明显差异,该安排更可能受到ATO进一步审查。

现有安排的调整机会

ATO已经为纳税人提供了一段过渡期,鼓励企业主动审查现有安排并进行必要调整。

如果企业在2027年6月30日前采取真实有效的措施,将高风险安排调整为低风险安排,那么即使之后ATO进行审查,企业通常不太可能因为这些安排而面临Part IVA相关的合规行动。

但是,这个过渡期并不代表全面豁免,也不是一次性的税务特赦。

它提供的是一个机会,让企业主能够主动评估目前的架构,并在问题出现之前进行调整。

企业主应该如何应对?

如果企业通过公司或信托经营,并且收入主要来自企业主自身的技能、专业能力或劳动,那么现在是重新审视利润分配安排的合适时机。

企业主可以考虑以下问题:

  • 公司保留利润是否有文件支持的短期商业原因?
  • 支付给家庭成员或关联方的金额是否合理,并且有真实工作作为依据?
  • 当前架构是否合理反映了创造收入个人所作出的贡献?
  • 如果ATO进行审查,目前安排是否能够经得起检验?

随着ATO进一步加强对个人服务收入安排的关注,企业主提前审查现有架构,有助于及时发现潜在风险,并降低未来税务合规问题。

皮特马丁会计师事务所 Pitt Martin Group 是一家提供税务,会计,生意咨询,自管养老金,审计及贷款等综合性服务的经澳洲特许会计师协会认证的注册会计师事务所。我们每年会花上几百个小时去研究新的税法,以保证我们的客户可以最大化合理避税。我们的中文联系方式是 Robert Liu +61292213345 或邮件 info@pittmartingroup.com.au。皮特马丁会计师事务所Pitt Martin Group坐落在交通便利的悉尼市市中心,是一家拥有可以说中文合伙人的会计师事务所。我们的荣誉包括2018年CPA新州首席优秀奖, 2020年澳大利亚小生意年度冠军入围奖, 2021年澳洲知名媒体《每日会计师》年度最佳会计师事务所冠军入围奖,2022年最佳会计师事务所新人入围奖和2023香港澳大利亚商业协会最佳积极生意入围奖。

皮特马丁会计师事务所 Pitt Martin Group资质包括超过十五年的从业经验,澳大利亚税务注册代理,澳大利亚与新西兰特许会计师协会(CAANZ)会员,新州、维州和西澳律师协会信托账户 (Trust Account) 认证审计师,澳大利亚金融贷款经纪人协会(FBAA)执业认证会员,澳大利亚证券及投资委员会注册代理,XERO, QUICKBOOKS, MYOB等会计软件授权单位及认证顾问。

本文内容仅供参考,不构成对任何个人或团体的具体情况而形成建议。任何个人或团体应该在征求专业人士的意见后方可采取行动。由于税法的时效性,我们在发布时已致力于提供及时、准确的信息,但不能保证所称述的内容在今后任然可以适用。转发该文内容请注明出处。

By Yvonne Shao @ Pitt Martin Tax

Read more

PSI: ATO Reviews Profit Distribution Risks

The Australian Taxation Office (ATO) is increasing its focus on how taxpayers who earn income from their personal skills, knowledge and expertise manage and distribute that income for tax purposes.

The ATO has recently released Practical Compliance Guideline PCG 2025/5, which outlines its compliance approach to arrangements involving the “alienation” of Personal Services Income (PSI). These arrangements generally involve income earned through an individual’s personal efforts being received by a company, trust or another entity instead of being directly recognised as the individual’s income.

Operating through a company or trust is common and can provide legitimate commercial advantages, including asset protection, business flexibility and succession planning. However, where income is mainly generated from one individual’s personal services, business owners should carefully consider whether their current arrangements remain appropriate under the ATO’s updated guidance.

Why Is the ATO Focusing on PSI Arrangements?

Many professionals and business owners use companies or trusts for valid commercial reasons. However, the ATO is concerned about arrangements where income generated from an individual’s skills, reputation or labour is redirected to other entities primarily to achieve a more favourable tax outcome.

The PSI rules aim to ensure that income generated mainly from an individual’s personal efforts is appropriately taxed. Although some businesses may qualify as a Personal Services Business (PSB) and fall outside certain PSI attribution rules, this does not mean the arrangement is automatically protected from ATO review.

The ATO has also highlighted that Part IVA general anti-avoidance provisions may apply where arrangements are implemented mainly to obtain a tax benefit. If Part IVA applies, taxpayers may face additional tax liabilities, penalties and interest charges.

What Arrangements Are Considered Lower Risk?

Under PCG 2025/5, the ATO considers whether the individual who performs the work receives an appropriate share of the financial benefits generated from those services.

An arrangement is generally more likely to be considered lower risk where:

  • The individual receives most of the economic benefit through salary, wages, bonuses, director fees or appropriate trust distributions.
  • Profits retained in a company are supported by genuine short-term commercial reasons.
  • Payments made to family members or related parties reflect reasonable amounts for actual services provided.

For example, retaining company profits to fund equipment purchases, business expansion or other short-term commercial needs may be acceptable where there is clear evidence supporting the purpose and the company follows through with those plans.

What May Attract ATO Attention?

The ATO has identified several behaviours that may increase compliance risk, including:

  • Splitting income with family members or related parties who have made little or no contribution to earning that income.
  • Retaining significant company profits without a genuine commercial purpose.
  • Allocating profits from personal services to entities or beneficiaries mainly because they have lower tax rates or available tax losses.

The key consideration is whether the person receiving the benefit has a genuine connection to the income generated.

Where there is a significant mismatch between the individual performing the work and the person ultimately taxed on the profits, the arrangement is more likely to attract ATO scrutiny.

Time to Review Existing Arrangements

The ATO has provided a transition period for taxpayers who genuinely review and adjust their arrangements.

Businesses that take genuine steps to move from higher-risk arrangements to lower-risk arrangements by 30 June 2027 are unlikely to face Part IVA compliance action in relation to those arrangements if reviewed by the ATO.

This transition period is not an automatic exemption or amnesty. Instead, it provides an opportunity for business owners to proactively assess their structures and make changes where necessary.

What Should Business Owners Do?

Business owners who operate through companies or trusts and derive income mainly from their own personal skills or efforts should review their current arrangements.

Consider the following questions:

  • Are retained profits supported by documented short-term commercial reasons?
  • Are payments to family members or related parties commercially reasonable and supported by genuine work performed?
  • Does the current structure appropriately reflect the contribution made by the individual generating the income?
  • Would the arrangement withstand ATO review?

With increased ATO attention on PSI arrangements, reviewing existing structures now can help identify potential issues early and reduce future compliance risks.

Pitt Martin Group is a firm of Chartered Accountants, providing services including taxation, accounting, business consulting, self-managed superannuation funds, auditing and mortgage & finance. We spend hundreds of hours each year on training and researching new tax laws to ensure our clients can maximize legitimate tax benefit. Our contact information are phone +61292213345 or email info@pittmartingroup.com.au. Pitt Martin Group is located in the convenient transportation hub of Sydney’s central business district. Our honours include the 2018 CPA NSW President’s Award for Excellence, the 2020 Australian Small Business Champion Award Finalist, the 2021 Australia’s well-known media ‘Accountants Daily’ the Accounting Firm of the Year Award Finalist and the 2022 Start-up Firm of the Year Award Finalist, and the 2023 Hong Kong-Australia Business Association Business Award Finalist.

Pitt Martin Group qualifications include over fifteen years of professional experience in accounting industry, Registered Australia Tax Agents, membership certification of the Chartered Accountants Australia and New Zealand (CA ANZ), certified External Examiner of the Law Societies of New South Wales, Victoria, and Western Australia Law Trust Accounts, membership certification of the Finance Brokers Association of Australia Limited (FBAA), Registered Agents of the Australian Securities and Investments Commission (ASIC), certified Advisor of accounting software such as XERO, QUICKBOOKS, MYOB, etc.

This content is for reference only and does not constitute advice on any individual or group’s specific situation. Any individual or group should take action only after consulting with professionals. Due to the timeliness of tax laws, we have endeavoured to provide timely and accurate information at the time of publication, but cannot guarantee that the content stated will remain applicable in the future. Please indicate the source when forwarding this content.

By Yvonne Shao @ Pitt Martin Tax

Read more
federal budget 2026-27

2026联邦预算税务改革:您现在应该考虑什么?

2026联邦预算案中提出的税务改革引发了广泛讨论。

房地产投资者正在重新审视自己的投资组合,企业主正在评估现有架构,而使用全权信托(Discretionary Trust)的家庭也开始关注未来可能带来的影响。

本次拟议改革主要聚焦于三个方面:

  • 负扣税(Negative Gearing)
  • 资本利得税(Capital Gains Tax,CGT)
  • 全权信托(Discretionary Trust)

需要特别注意的是,这些措施目前仍未正式成为法律,相关立法仍需经过国会审议及通过。

然而,这并不意味着可以忽视这些提案。相反,现在正是了解潜在影响并提前规划的好时机。

为什么提前规划很重要?

许多人正在等待政策最终确定后才采取行动。

但事实上,明智的规划并不需要等待所有不确定性消除。

根据目前的提案,负扣税及资本利得税改革预计将于2027年7月1日开始实施,而信托税制改革预计不会早于2028年7月1日生效。

因此,无论是投资者还是企业主,都有充分时间检视自身状况并评估各种应对方案。

您今天并不需要立即作出重大调整,但提早了解风险和机会,有助于未来作出更好的决策。

1. 检视现有房地产投资组合

本次预算案中最受关注的内容之一就是负扣税改革。

政府计划限制2026年5月12日之后购买的现有住宅物业(Established Residential Property)所适用的负扣税优惠。

现有投资者或将受益于“祖父条款”

根据目前提案,在预算案公布前已持有住宅物业的投资者,可能受到“祖父条款(Grandfathering Rules)”保护。

这意味着他们仍可继续按照现行规定享受负扣税优惠。

符合条件的出租物业亏损,仍可抵减工资收入、商业收入以及其他应税收入。

对于许多投资者而言,这项待遇未来可能成为重要的长期税务优势。

为什么这很重要?

未来不同投资物业的税务待遇可能不再相同。

因此,现在正是重新审视投资组合的好时机。

首先,识别哪些资产可能符合祖父条款保护;其次,评估这些资产是否符合您的长期投资目标。

一次简单的投资组合检视,可能让您发现过去忽略的机会。

2. 审慎考虑未来房地产投资

拟议改革可能改变投资者未来购买物业时的考量方式。

过去,许多投资者购买现有住宅物业的重要原因之一,就是能够利用负扣税带来的税务优势。

但未来投资者可能需要更加关注投资本身的基本面。

聚焦优质投资

税务优惠固然重要,但不应成为购买投资物业的主要理由。

更重要的是关注:

  • 优质地段
  • 租赁需求
  • 现金流潜力
  • 长期增值能力

这些因素通常比单纯税务扣除更能影响投资回报。

新建住宅或更具吸引力

政府亦表示,新建住宅物业未来可能继续享有较优惠的税务待遇。

部分住宅开发项目及建后出租(Build-to-Rent)项目亦可能获得相关优惠政策。

因此,未来投资者可能会更积极比较新建物业与现有物业之间的投资价值。

3. 识别可能需要进行估值的资产

拟议中的资本利得税改革可能创造新的税务规划机会。

同时,也可能带来额外的记录保存要求。

为什么资产估值很重要?

根据提案,2027年7月1日前累积的资本增值,与该日期后产生的资本增值,将可能适用不同的税务处理方式。

因此,许多投资者可能需要取得截至2027年7月1日的准确市场价值。

这可能涉及:

  • 投资房产
  • 商业地产
  • 股票投资组合
  • 企业资产

提前准备

专业估值通常需要时间安排及准备资料。

因此,在任何截止日期到来之前提早规划是明智之举。

完善的记录保存不仅能节省时间,也能降低未来税务争议和合规风险。

4. 检视资本利得税策略

政府同时计划调整现行资本利得税折扣制度。

这也是本次预算案最重大的税务改革之一。

过去多年,投资者普遍依赖50% CGT折扣来降低出售资产时的税务负担。

然而,拟议改革可能改变部分投资者对于未来资产出售时机的考量。

检视未来退出计划

现在正是重新审视长期规划的好时机。

例如:

  • 哪些资产可能在未来五年内出售?
  • 现行制度下的税务结果如何?
  • 拟议改革后又会产生什么变化?

这些问题有助于提早识别潜在风险。

保持整体视角

税务固然重要,但不应主导所有决策。

投资目标、退休规划及现金流需求,仍应是决策过程中的核心考虑因素。

5. 检视您的信托架构

拟议中的信托改革受到高度关注。

根据提案,全权信托未来可能需要按最低30%的税率纳税。

了解潜在影响

许多家庭利用全权信托在受益人之间分配收入。

政府希望减少部分与此类安排相关的税务优势。

因此,在新制度下,部分家庭的整体税负可能会上升。

不要忽略信托的非税务优势

信托的价值并不仅限于节税。

信托还可协助实现:

  • 资产保护
  • 遗产规划
  • 传承安排
  • 家族财富管理

因此,即使税务结果发生变化,信托在许多家庭和企业架构中仍可能继续发挥重要作用。

6. 考虑其他架构选择

部分纳税人可能希望重新评估现有持有架构。

但重组并不一定适合所有人。

比较不同选择

根据您的具体情况,可以考虑比较:

  • 私人有限公司(Private Company)
  • 固定信托(Fixed Trust)
  • 公司受益人(Corporate Beneficiary)
  • 其他商业架构

每种架构均有其优缺点。

避免仓促决定

不要仅根据尚未通过的提案作出重大结构调整。

应综合考虑税务结果、资产保护需求、商业目标及传承规划等因素后再作决定。

7. 持续关注政策发展

这可能是最重要的一项行动。

截至目前,这些提案仍未正式成为法律。

重视准备,而非恐慌

在法案正式通过前,许多细节仍有可能发生变化。

因此,提前准备远比猜测政策走向更有价值。

检视自身状况、模拟不同情境、了解各种选择。

当更多细节公布时,您便能够更有信心地采取行动。

常见问题

负扣税会被取消吗?

不会。

目前提案主要限制部分亏损的使用方式,并非全面取消负扣税制度。

现有物业是否受到保护?

根据目前提案,许多现有物业持有人将受到祖父条款保护。

我现在应该重组信托吗?

未必。

在最终立法内容更明确之前,通常建议保持谨慎并持续关注政策发展。

信托未来还有价值吗?

有。

在许多情况下,信托仍可提供资产保护、遗产规划及财富传承等重要功能。

在作出重大决定前寻求专业意见

每位纳税人的情况都不同。

例如,有些投资者可能从祖父条款中获益,而另一些投资者则需要重新规划未来购置策略。

同样地,有些企业主可能适合进行架构重组,而另一些则未必如此。

专业意见能够帮助您了解各种选择,并避免因仓促决策而产生不必要的成本和风险。

下一步应该做什么?

拟议中的2026联邦预算税务改革,可能在未来多年影响投资者、企业主及家庭的税务安排。

但目前仍有充足时间进行准备。

现在正是检视自身状况、了解潜在影响并制定未来规划的理想时机。

通过提早行动,您能够在政策逐步明朗的过程中,作出更明智的决定,并从容应对未来变化。

需要协助?

与我们这样的专业税务会计师和贷款经纪人合作,您可以放心,我们的团队可以提供针对性建议,确保贷款结构既能保护您的税务最大化扣除,同时避免错误的风险,从而让您更加安心,并更好地规划财务。

皮特马丁会计师事务所 Pitt Martin Group 是一家提供税务,会计,生意咨询,自管养老金,审计及贷款等综合性服务的经澳洲特许会计师协会认证的注册会计师事务所。我们每年会花上几百个小时去研究新的税法,以保证我们的客户可以最大化合理避税。我们的中文联系方式是 Robert Liu +61292213345 或邮件 info@pittmartingroup.com.au。皮特马丁会计师事务所Pitt Martin Group坐落在交通便利的悉尼市市中心,是一家拥有可以说中文合伙人的会计师事务所。我们的荣誉包括2018年CPA新州首席优秀奖, 2020年澳大利亚小生意年度冠军入围奖, 2021年澳洲知名媒体《每日会计师》年度最佳会计师事务所冠军入围奖,2022年最佳会计师事务所新人入围奖和2023香港澳大利亚商业协会最佳积极生意入围奖。

皮特马丁会计师事务所 Pitt Martin Group资质包括超过十五年的从业经验,澳大利亚税务注册代理,澳大利亚与新西兰特许会计师协会(CAANZ)会员,新州、维州和西澳律师协会信托账户 (Trust Account) 认证审计师,澳大利亚金融贷款经纪人协会(FBAA)执业认证会员,澳大利亚证券及投资委员会注册代理,XERO, QUICKBOOKS, MYOB等会计软件授权单位及认证顾问。

本文内容仅供参考,不构成对任何个人或团体的具体情况而形成建议。任何个人或团体应该在征求专业人士的意见后方可采取行动。由于税法的时效性,我们在发布时已致力于提供及时、准确的信息,但不能保证所称述的内容在今后任然可以适用。转发该文内容请注明出处。

By Robert Liu @ Pitt Martin Tax

Read more
Understanding the Tax Implications of Property Subdivision Projects

了解土地分割项目的税务影响

随着澳大利亚主要城市的城市扩张不断推进,越来越多的房产持有者开始考虑进行土地分割项目。尽管这类项目可能带来可观的经济回报,但在投入之前,充分了解相关税务影响至关重要。若误解了分割项目的税务处理方式,可能会带来高昂的代价,并严重影响项目的整体收益。

一个常见的误区是认为土地分割所得的税负非常低。然而,事实远比这复杂,多个关键税务因素可能大幅影响您项目的整体盈利能力。

例如,如果您购买房产的目的是为了分割并短期出售地块以获取利润,澳大利亚税务局(ATO)很可能会将此类行为视为营利性活动。在这种情况下,您的利润将按普通收入纳税,而不是适用资本利得税(CGT)规则。这意味着,原本适用于持有资产超过12个月的50% CGT折扣将无法使用,您也不能利用资本亏损来抵减应纳税额。

除了所得税之外,土地分割出售所得还可能适用商品及服务税(GST)。这两项税种都会大幅压缩您的税后利润。

很多个人低估了自己在所得税和GST方面的义务。当他们意识到真实的财务影响时,往往为时已晚,整个项目的可行性也可能因此陷入危机。

为协助纳税人,ATO更新了其有关房产交易税务处理的指南。更新后的指南包含一系列真实案例,展示了在不同房产情境下,如土地分割、房产倒卖和开发等,所得税和GST规则可能如何适用。

其中一个案例讲述了一位纳税人反复购买、翻新并出售房产的情形。此人会进行全面的市场调研,寻求专业建议,获得商业贷款,并以结构化、商业化的方式进行翻修。ATO将其视为一种经营行为,其主要目的在于通过转售房产获取利润。因此,其所得将被视为普通收入征税。由于这些房产被视为交易存货而非资本资产,CGT规则及折扣将不适用。

然而,除非房产进行了“实质性翻修”,否则GST可能并不适用。这里的“实质性翻修”是一个具有技术性的定义,每个案例都必须进行仔细评估。

ATO的另一个示例展示了另一种情况。在该案例中,纳税人由于个人困境(健康恶化和债务增加)而进行土地分割。该分割活动仅限于获得市政批准,并未进行进一步开发,也无明确意图获取利润,仅是出售部分土地来缓解财务压力。ATO将此类交易视为对资本资产的“单纯变现”。这意味着所得将按照CGT规则征税,并且如果该土地持有时间超过12个月,将可享受50%的CGT折扣。

不过,尽管被分割出售的地块属于纳税人主要住所所在的土地范围,但由于它是与住宅本身分开出售的,因此不符合主要住宅豁免的条件。

这些案例强调了从项目一开始就准确识别土地分割目的和规模的重要性。意图、结构或执行方式的细微差异,都可能导致完全不同的税务结果。 在启动任何土地分割项目前,务必寻求专业税务建议,以全面了解自己的税务义务。充分的信息准备有助于避免意外的税务账单,并确保您的项目在财务上保持可行性。

皮特马丁会计师事务所 Pitt Martin Group 是一家提供税务,会计,生意咨询, 自管养老金及审计的贷款等综合性服务的经澳洲会计师公会认证的注册会计师事务所。我们每年会花上几百个小时去研究新的税法,以保证我们的客户可以最大化合理避税。我们的中文联系方式是 Robert Liu +61292213345 或邮件 info@pittmartingroup.com.au。皮特马丁会计师事务所Pitt Martin Group坐落在交通便利的悉尼市市中心,是一家拥有可以说中文合伙人的会计师事务所。我们的荣誉包括2018年CPA新州首席优秀奖, 2020年澳大利亚小生意年度冠军入围奖, 2021年澳洲知名媒体《每日会计师》年度最佳会计师事务所冠军入围奖,2022年最佳会计师事务所新人入围奖和2023香港澳大利亚商业协会最佳积极生意入围奖。

皮特马丁会计师事务所 Pitt Martin Group资质包括超过十五年的从业经验,澳大利亚与新西兰特许会计师协会(CAANZ)会员,澳大利亚注册会计师协会(CPA)执业认证会员,澳大利亚税务注册代理,新州、维州和西澳律师协会信托账户 (Trust Account) 认证审计师,澳大利亚金融贷款经纪人协会(FBAA)执业认证会员,澳大利亚证券及投资委员会注册代理,XERO, QUICKBOOKS, MYOB等会计软件授权单位及认证顾问。

本文内容仅供参考,不构成对任何个人或团体的具体情况而形成建议。任何个人或团体应该在征求专业人士的意见后方可采取行动。由于税法的时效性,我们在发布时已致力于提供及时、准确的信息,但不能保证所称述的内容在今后任然可以适用。转发该文内容请注明出处。

By Robert Liu @ Pitt Martin Tax

Read more